
Wet Chemicals For Electronics and Semiconductor Applications Market Size and Share
Market Overview
| Study Period | 2021 - 2031 |
|---|---|
| Market Size (2026) | USD 4.89 Billion |
| Market Size (2031) | USD 6.93 Billion |
| Growth Rate (2026 - 2031) | 7.23 % |
| Fastest Growing Market | Asia-Pacific |
| Largest Market | Asia-Pacific |
| Market Concentration | Medium |
Major Players *Disclaimer: Major Players sorted in no particular order Image © Mordor Intelligence. Reuse requires attribution under CC BY 4.0. | |
Wet Chemicals For Electronics and Semiconductor Applications Market Analysis by Mordor Intelligence
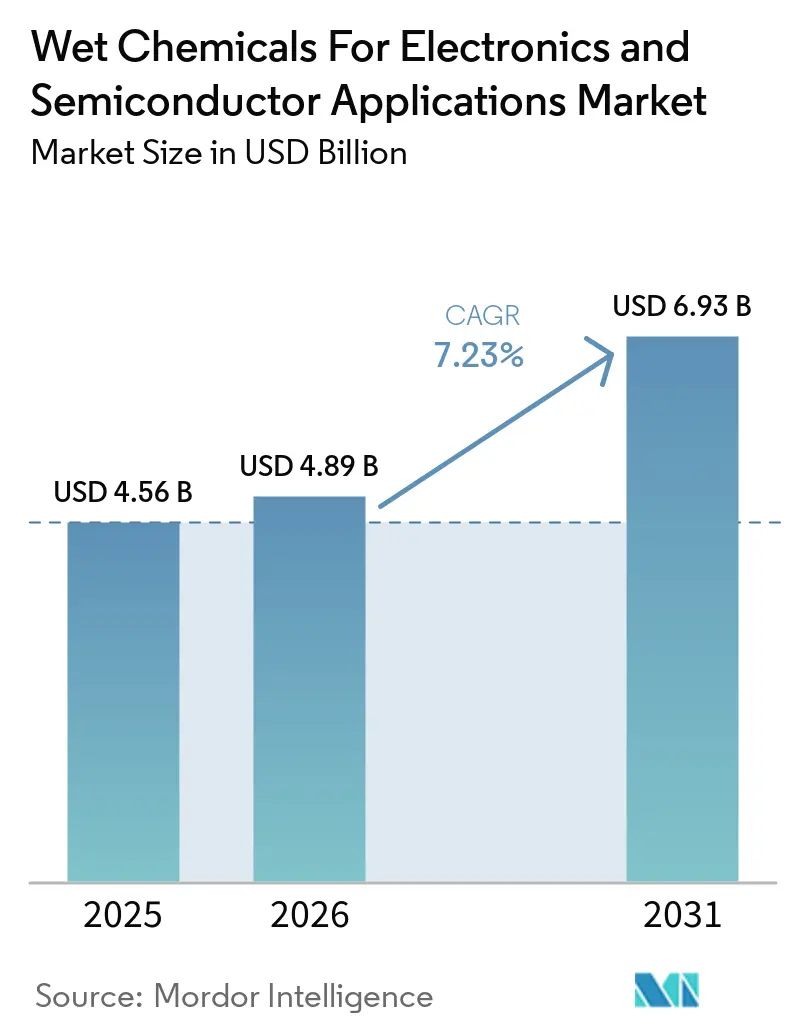
The Wet Chemicals for Electronics and Semiconductor Applications Market size was valued at USD 4.56 billion in 2025 and is estimated to grow from USD 4.89 billion in 2026 to reach USD 6.93 billion by 2031, at a CAGR of 7.23% during the forecast period (2026-2031). The wet chemicals for electronics and semiconductor applications market is supported by more cleaning, etching, and surface-preparation steps at advanced semiconductor nodes. Wet processing represented 35%-59% of chemical consumption across technology-node flows from N90 to A14, which keeps this category central to chip manufacturing even as process designs change. Demand is also shaped by the move toward 3D structures and advanced packaging, where chemical purity and process control affect yield. Suppliers are responding through capacity additions near major fabrication clusters and through products qualified for specific process steps. Long qualification periods and tighter wastewater rules favor established suppliers, while they also raise the cost of expanding supply in the wet chemicals for electronics and semiconductor applications market.
Key Report Takeaways
- By product type, hydrogen peroxide held 27.18% of the wet chemicals for electronics and semiconductor applications market share in 2025, while sulfuric acid is projected to advance at an 8.05% CAGR through 2031.
- By application, semiconductor held 51.56% of the wet chemicals for electronics and semiconductor applications market share in 2025 and is projected to advance at an 8.43% CAGR through 2031.
- By geography, Asia-Pacific held 40.32% of the wet chemicals for electronics and semiconductor applications market share in 2025 and is projected to advance at an 8.27% CAGR through 2031.
Note: Market size and forecast figures in this report are generated using Mordor Intelligence’s proprietary estimation framework, updated with the latest available data and insights as of January 2026.
Market Trends and Insights
Drivers Impact Analysis of Wet Chemicals For Electronics and Semiconductor Applications Market*
| Driver | (~) % Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
|---|---|---|---|
| Expansion of Advanced-Node and 3D Semiconductor Fabrication | +2.0% | Global (APAC core, spillover to North America & EU) | Medium term (2–4 years) |
| AI, High-Performance Computing, 5G and Automotive Semiconductor Demand | +1.7% | Global | Long term (≥ 4 years) |
| Higher Wet-Chemical Intensity per Wafer at Sub-7 nm Nodes | +1.4% | Global (APAC & North America) | Medium term (2–4 years) |
| Fab Localization and Government Semiconductor Incentives | +1.0% | North America & EU | Long term (≥ 4 years) |
| Advanced Packaging, Hybrid Bonding and Heterogeneous Integration | +0.7% | Global (APAC core) | Medium term (2–4 years) |
| Source: Mordor Intelligence | |||
Expansion of Advanced-Node and 3D Semiconductor Fabrication
The wet chemicals for electronics and semiconductor applications market benefits from 3D NOT AND (NAND) and gate-all-around logic architectures, which add process steps to each wafer rather than merely reducing feature sizes. A 3 nm wafer moves through more than 600 process steps, with 15%-20% involving dedicated cleaning stages using dilute hydrofluoric acid, ammonium hydroxide-peroxide, and hydrochloric acid-peroxide formulations. Leading memory producers have moved beyond 200 stacked layers in 3D NAND, so each additional layer adds etching cycles and associated cleaning needs. Taiwan Semiconductor Manufacturing Company (TSMC) provided 2026 capital expenditure guidance of USD 52 billion-USD 56 billion for 2 nm capacity and advanced packaging facilities in Taiwan, Arizona, and Japan. Each new sub-7 nm fab can therefore become a larger recurring chemicals customer even when wafer output does not rise at the same rate as chemical use. Hybrid bonding adds surface preparation, post-bond cleaning, and through-silicon-via fill needs, broadening the role of wet chemistry beyond front-end wafer manufacturing.
AI, High-Performance Computing, 5G and Automotive Semiconductor Demand
The wet chemicals for electronics and semiconductor applications market gains support from artificial intelligence (AI) accelerators, high-performance computing processors, 5G equipment, and automotive chips. TSMC reported that AI accelerators and high-performance computing processors accounted for 58% of its USD 122.42 billion revenue in 2025, while advanced nodes represented 77% of second-quarter 2026 wafer revenue by value. AI-chip production requires very low metallic impurity levels, additional chemical processing steps per die, and consistent defect control across complex process flows. Semiconductor lines for 5G base stations and automotive advanced driver-assistance systems use less advanced nodes, but they need wet chemicals with selectivity suited to demanding reliability requirements. This creates demand for ultra-high-purity grades alongside application-specific products, which reduces dependence on one chemical grade and one end-use pattern. Automotive compliance frameworks, including AEC-Q100 and IATF 16949, also reinforce traceability and purity expectations across the production flows used by component manufacturers.
Higher Wet-Chemical Intensity per Wafer at Sub-7 nm Nodes
The wet chemicals for electronics and semiconductor applications market is affected by rising chemical use for each wafer as nodes move below 7 nm and process sequences become more complex. Wet processing accounted for 35%-59% of total chemical use in full technology-node flows from N90 to A14, and it remained the largest chemical-use category at advanced nodes. Multi-patterning and the interface requirements of gate-all-around transistors increase cleaning and wet-etch needs at several points in the manufacturing sequence. At advanced nodes, tighter contamination specifications can restrict the reuse of processed chemicals and increase purchases of new, qualified material. Metallic impurity requirements at parts-per-trillion levels make chemical purity a production issue rather than a procurement preference for fab operators. The SEMI C1 framework for liquid chemicals further supports consistent purity requirements across qualified supply chains and established material specifications.
Fab Localization and Government Semiconductor Incentives
The wet chemicals for electronics and semiconductor applications market is expanding into new production locations as governments encourage local chip manufacturing and more resilient supply chains. The European Commission adopted its proposal for the EU Chips Act 2.0 in June 2026, including provisions for direct European Union investment in semiconductor manufacturing and new chip technologies[1]. Intel committed EUR 5 billion (approximately USD 5.7 billion) to expand its Leixlip campus in Ireland in July 2026. Infineon opened its Smart Power Fab in Dresden in July 2026, expanding local manufacturing for power semiconductor and analog products. Local chemical production can help fabs meet approval and waste-management requirements under the European Union Registration, Evaluation, Authorisation and Restriction of Chemicals (REACH) regulation and the Industrial Emissions Directive.
Restraints Impact Analysis of Wet Chemicals For Electronics and Semiconductor Applications Market*
| Restraint | (~) % Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
|---|---|---|---|
| Hazardous-Chemical Compliance and Waste-Treatment Costs | -0.9% | Global | Short term (≤ 2 years) |
| Qualification Cycles and Switching Costs at Leading-Edge Fabs | -0.6% | Global (APAC & North America) | Long term (≥ 4 years) |
| Feedstock, Logistics and Regional Supply-Chain Disruptions | -0.4% | Global | Short term (≤ 2 years) |
| Source: Mordor Intelligence | |||
Hazardous-Chemical Compliance and Waste-Treatment Costs
The wet chemicals for electronics and semiconductor applications market faces additional costs from hazardous-chemical discharge rules and increasingly complex waste treatment. The U.S. Environmental Protection Agency set out actions for perfluoroalkyl and polyfluoroalkyl substances (PFAS), including work on discharge controls, in its PFAS Strategic Roadmap[2]. Until January 2025, the maximum civil penalty for a Clean Water Act violation was USD 68,445 per day per violation under 40 CFR 19.4. Semiconductor facilities may need activated-carbon, ion-exchange, or Zero Liquid Discharge (ZLD) systems to manage wastewater and meet tighter discharge expectations. More process steps at advanced nodes raise effluent volumes and make hydrofluoric acid, tetramethylammonium hydroxide, and heavy-metal waste streams more difficult and more costly to manage.
Qualification Cycles and Switching Costs at Leading-Edge Fabs
The wet chemicals for electronics and semiconductor applications market has a high barrier to entry because a new supplier normally needs 12-18 months to qualify at a leading-edge fab. Qualification is node specific, so a formulation approved for a 3 nm process does not automatically qualify for a 2 nm process with different yield requirements. TSMC, Samsung Electronics, and SK Hynix typically maintain 3-6 approved suppliers for a critical chemical step, which provides operational redundancy without creating easy supplier substitution. A potential supplier must complete defect analysis, line-edge roughness work, and process-integration testing before it can receive volume authorization for a production line. This process makes the new supply slower to reach the market than capital-investment announcements can suggest and requires resources from both the supplier and the fab. It also supports incumbent pricing power because chemical buyers avoid formulation changes that could reduce yield, even when price differences exist.
*Our forecasts treat driver/restraint impacts as directional, not additive. The impact forecasts reflect baseline growth, mix effects, and variable interactions.
Wet Chemicals For Electronics and Semiconductor Applications Market Segment Analysis
By Product Type:
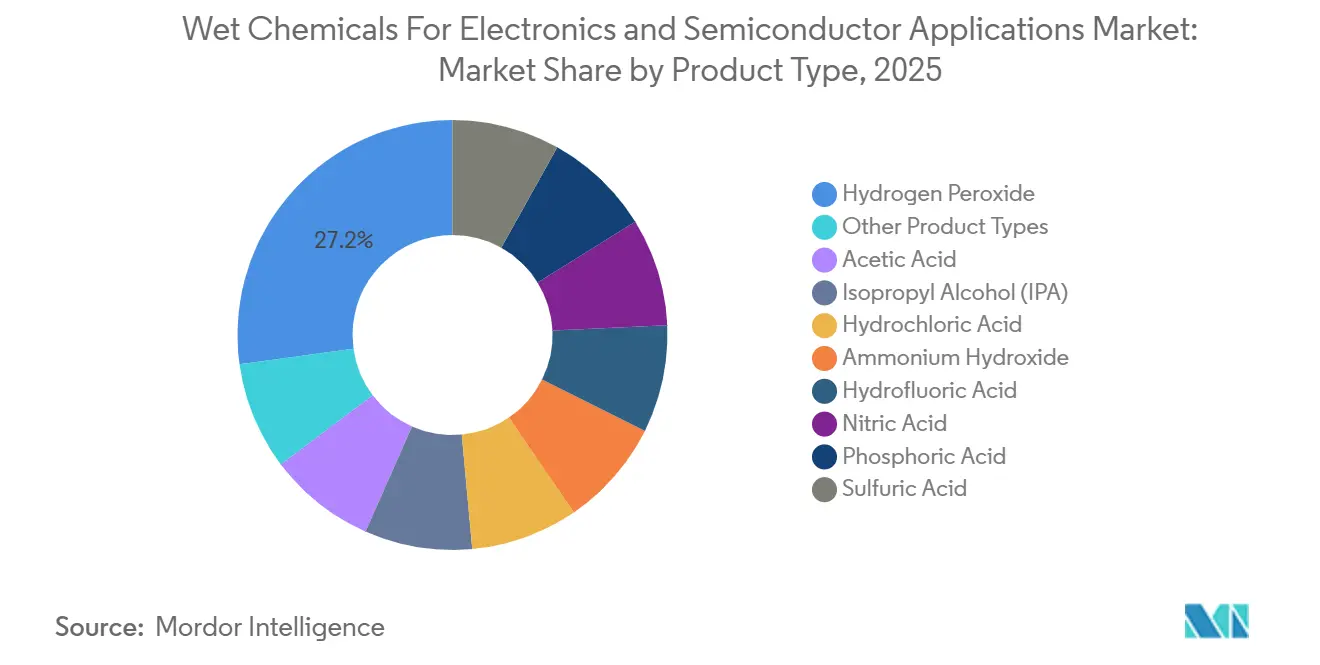
Hydrogen Peroxide Leads While Sulfuric Acid Sets the PaceHydrogen peroxide held 27.18% of the wet chemicals for electronics and semiconductor applications market share in 2025. Its role in SC-1 cleaning and sulfuric acid-peroxide mixture stripping supports repeated use in leading-edge logic and memory production. These cleaning sequences remove particles, organic residues, and trace contamination before later process steps. The same cleaning step requires tighter trace-metal control at 2 nm than at 28 nm, which raises the importance of product consistency. This requirement can increase material volume and the value of qualified grades as manufacturers seek stable process results across high-volume wafer runs.
Sulfuric acid is projected to advance at an 8.05% CAGR through 2031, the fastest rate among product types in the wet chemicals for electronics and semiconductor applications industry. Its growth reflects more frequent sulfuric acid-peroxide mixture cleaning at sub-7 nm nodes, where photoresist removal and surface condition affect later processing. BASF announced in April 2025 that it would build a semiconductor-grade sulfuric acid facility at Ludwigshafen, Germany, with operations expected in 2027. Hydrofluoric acid supports oxide and nitride etching, while phosphoric acid supports selective silicon-nitride etching in high-aspect-ratio 3D NAND structures. Nitric acid and acetic acid serve passivation and precision-cleaning uses, while post-chemical mechanical planarization cleaners are gaining importance as fabs pursue yield improvement.

By Application:
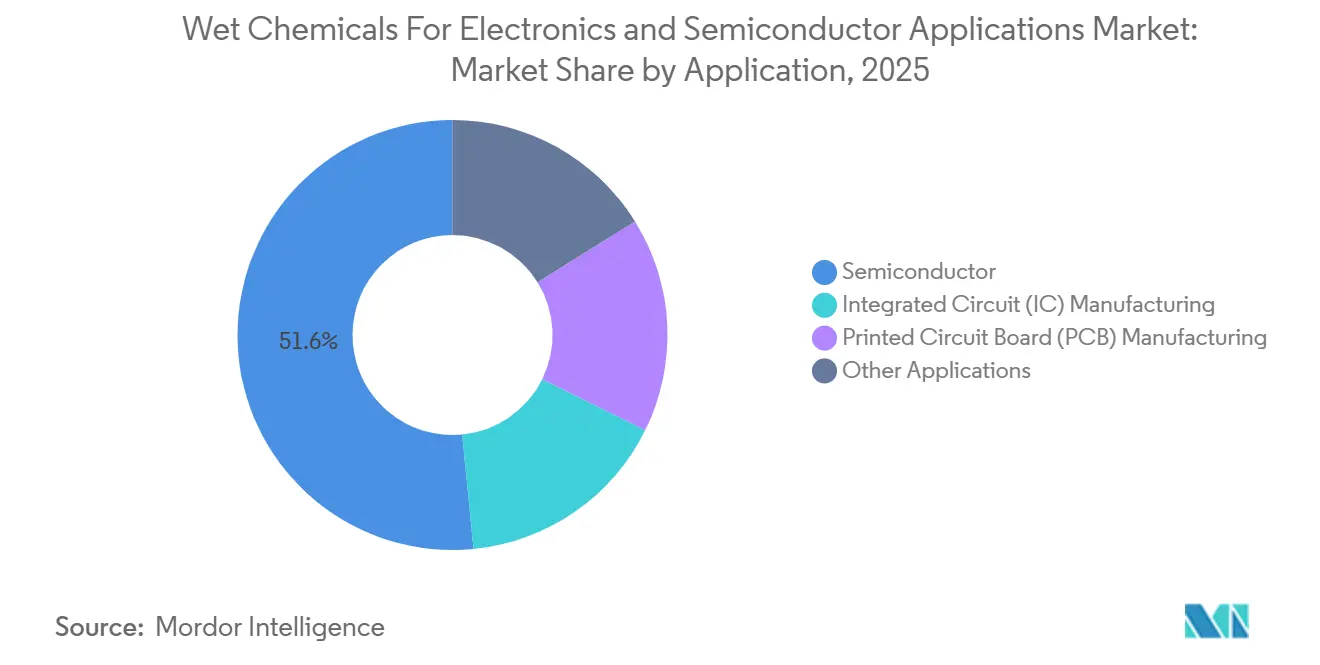
Semiconductor Commands Both Scale and GrowthSemiconductor held 51.56% of the wet chemicals for electronics and semiconductor applications market share in 2025. It uses wet chemicals for cleaning and etching across logic, memory, and foundry production, making it the largest demand center among applications. Cleaning represents the larger part of demand because advanced facilities increasingly use single-wafer processing rather than batch methods. This approach uses more chemistry for each wafer, but it supports the yield and contamination-control requirements of nodes below 7 nm. Etching is the faster-moving activity within semiconductor fabrication as 3D architectures add cycles and extend the time spent on material removal.
The semiconductor is projected to advance at an 8.43% CAGR through 2031. Growth in the wet chemicals for electronics and semiconductor applications market size for this application is tied more closely to node migration and process complexity than to wafer volumes alone. Integrated circuit manufacturing adds back-end and packaging demand for underbump metallization cleaning, redistribution-layer preparation, and post-bond cleaning for increasingly complex chip assemblies. Printed circuit board manufacturing provides a steadier base through copper etching and inner-layer processing for electronics, automotive, and industrial end uses.
Geography Analysis
APAC Wet Chemicals for Electronics and Semiconductor Applications Market
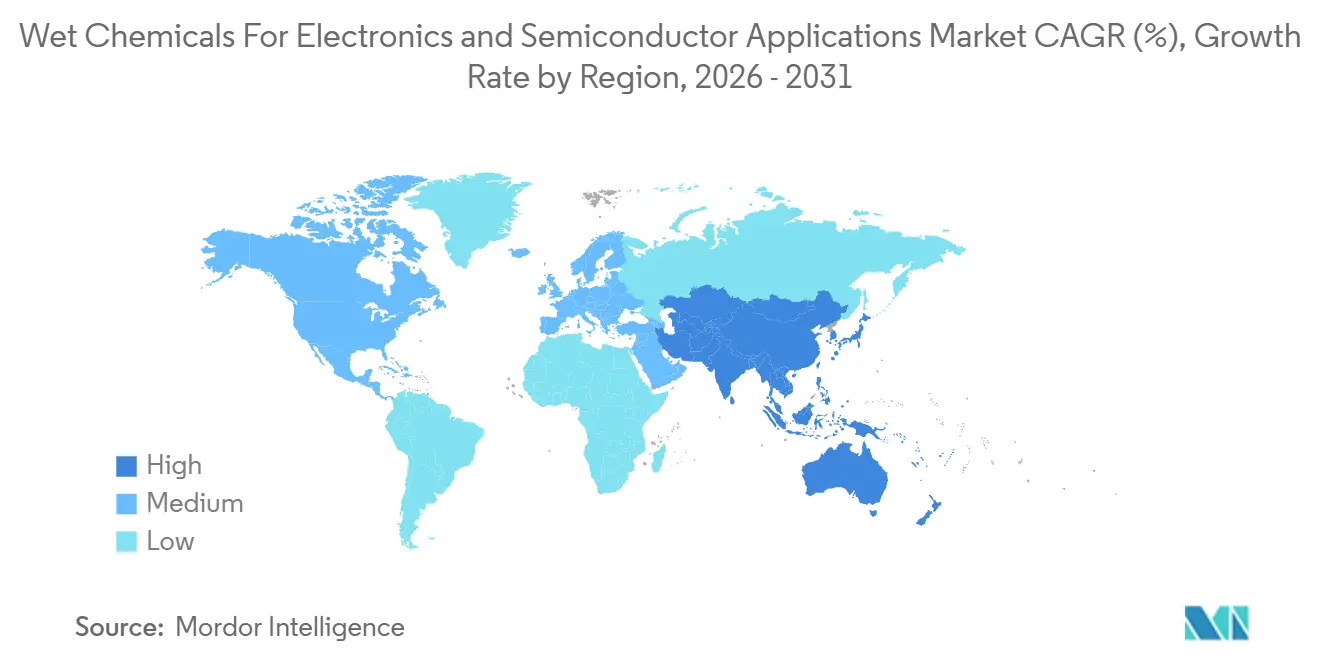
Asia-Pacific held 40.32% of the wet chemicals for electronics and semiconductor applications market share in 2025 and is projected to advance at an 8.27% CAGR through 2031. Taiwan, South Korea, Japan, and China concentrate much of the region’s semiconductor capacity and ultra-high-purity chemical demand. TSMC’s 2026 capital expenditure guidance of USD 52 billion-USD 56 billion supports demand from 2 nm production and advanced packaging additions. China’s fab expansion focuses more on mature and mid-range nodes, which creates substantial demand at different purity and price levels. India is an emerging location, and FUJIFILM Corporation signed a memorandum of understanding with Tata Electronics in September 2026 to support the semiconductor-materials ecosystem for the Dholera fab.
North America Wet Chemicals for Electronics and Semiconductor Applications Market
In North America, New fabs in Arizona, Ohio, and Texas are expected to create further demand as they move toward production through 2027-2030. Worldwide 300 mm fab equipment spending reached USD 107 billion in 2025, passing USD 100 billion for the first time. The region has historically depended on wet-chemical production in Japan, Germany, and Taiwan, while domestic-content provisions support local supply options. U.S. electronics wastewater requirements and perfluoroalkyl and polyfluoroalkyl substances discharge controls encourage facilities designed with Zero Liquid Discharge capability.
EMEA and South America Wet Chemicals for Electronics and Semiconductor Applications Market
In Europe, Infineon opened its Smart Power Fab in Dresden in July 2026, adding demand for power semiconductor and analog process chemistries. GlobalFoundries’ planned Dresden expansion targets more than 1 million wafers annually by 2028, while BASF announced sulfuric acid and ammonium hydroxide investments in Ludwigshafen in 2025. South America and the Middle East and Africa remain smaller demand areas, with demand linked primarily to printed circuit boards, assembly, testing, and integrated circuit packaging.
Competitive Landscape
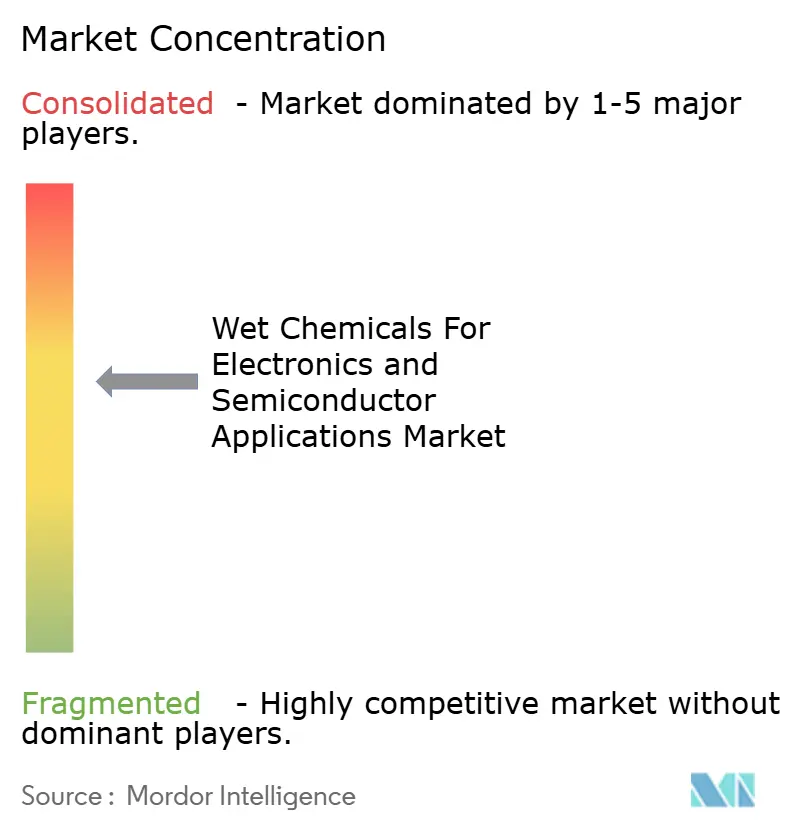
The wet chemicals for electronics and semiconductor applications market is moderately concentrated, with the top five players including Entegris, BASF, Avantor, Inc., Honeywell International Inc., and KANTO KAGAKU. Competition depends on qualified formulations, ultra-high-purity grades, and application fit rather than price alone. FUJIFILM Corporation disclosed 20% average annual growth in its semiconductor materials business from fiscal year 2021 through fiscal year 2025. Established suppliers benefit when their products are integrated into yield-sensitive steps, and long qualification periods limit rapid supplier changes.
Strategic activity in the wet chemicals for electronics and semiconductor applications market is centered on capacity, local access, and lower-impact formulations. FUJIFILM Corporation completed its Oita facility for post-chemical mechanical planarization cleaners in August 2026 and tripled production capacity at the site. BASF announced semiconductor-grade sulfuric acid capacity in April 2025 and an electronic-grade ammonium hydroxide plant in October 2025, both in Ludwigshafen. These investments position the supply closer to the expanding German semiconductor cluster. Suppliers are developing formulations for hybrid bonding and heterogeneous integration, while environmentally reformulated products can gain importance as restrictions on fluorinated materials tighten.
The wet chemicals for electronics and semiconductor applications market has room for suppliers focused on local manufacturing in North America and Europe. Specialty cleaning formulations for displays and advanced packaging may offer a more accessible entry point than leading-edge wafer fabrication. Suppliers that provide validated purity, logistics reliability, and local technical support may gain a position as fab capacity spreads geographically. The wet chemicals for electronics and semiconductor applications market remains less open to price-based switching, where a chemical change could threaten production yield.
Wet Chemicals For Electronics and Semiconductor Applications Industry Leaders
-
Entegris
-
Honeywell International Inc.
-
KANTO KAGAKU
-
BASF
-
Avantor, Inc.
- *Disclaimer: Major Players sorted in no particular order
Wet Chemicals For Electronics and Semiconductor Applications Market Companies Covered in this Report
- Air Products and Chemicals, Inc.
- Avantor, Inc.
- BASF
- Eastman Chemical Company
- Entegris
- FUJIFILM Corporation
- Honeywell International Inc.
- JSR Corporation
- KANTO KAGAKU
- Merck KGaA
- Mitsubishi Chemical Corporation
- Shin-Etsu Chemical Co., Ltd.
- Solvay
- TOKYO OHKA KOGYO CO., LTD.
Recent Industry Developments in Wet Chemicals For Electronics and Semiconductor Applications Market
- September 2026: Solvay announced plans to more than double its ultra-pure hydrogen peroxide capacity in Taiwan from 35,000 to more than 70,000 metric tons per year by the end of 2026 through its Shinsol Advanced Chemicals joint venture. The expansion responds to rising semiconductor demand and strengthens the supply of electronic-grade hydrogen peroxide used for wafer cleaning.
- October 2025: BASF announced construction of a new electronic-grade ammonium hydroxide plant at its Ludwigshafen site in Germany, with operations expected to start in 2027. The high-purity chemical will support wafer cleaning, etching, and other precision semiconductor processes, strengthening local supply for Europe’s expanding semiconductor manufacturing base.
Global Wet Chemicals For Electronics and Semiconductor Applications Market Report Scope
Wet chemicals are high-purity chemical formulations used to clean, etch, remove contaminants, and prepare surfaces during electronics and semiconductor manufacturing processes. They support precision processing by enabling controlled removal of materials and residues from wafers, components, and electronic substrates.
The Wet Chemicals for Electronics and Semiconductor Applications Market is segmented by product type, application, and geography. By product type, the market is segmented into hydrogen peroxide, acetic acid, isopropyl alcohol (IPA), hydrochloric acid, ammonium hydroxide, hydrofluoric acid, nitric acid, phosphoric acid, sulfuric acid, and other product types. By application, the market is segmented into semiconductor, including cleaning and etching, integrated circuit (IC) manufacturing, printed circuit board (PCB) manufacturing, and other applications. The report also covers the market size and forecasts for wet chemicals for electronics and semiconductor applications across 15 countries. For each segment, the market sizing and forecasts have been done on the basis of value (USD).
Segmentation Overview
| Hydrogen Peroxide |
| Acetic Acid |
| Isopropyl Alcohol (IPA) |
| Hydrochloric Acid |
| Ammonium Hydroxide |
| Hydrofluoric Acid |
| Nitric Acid |
| Phosphoric Acid |
| Sulfuric Acid |
| Other Product Types |
| Semiconductor | Cleaning |
| Etching | |
| Integrated Circuit (IC) Manufacturing | |
| Printed Circuit Board (PCB) Manufacturing | |
| Other Applications |
| Asia-Pacific | China |
| India | |
| Japan | |
| South Korea | |
| ASEAN Countries | |
| Rest of Asia-Pacific | |
| North America | United States |
| Canada | |
| Mexico | |
| Europe | Germany |
| United Kingdom | |
| France | |
| Italy | |
| NORDIC Countries | |
| Rest of Europe | |
| South America | Brazil |
| Argentina | |
| Rest of South America | |
| Middle East and Africa | Saudi Arabia |
| South Africa | |
| Rest of Middle East and Africa |
| By Product Type | Hydrogen Peroxide | |
| Acetic Acid | ||
| Isopropyl Alcohol (IPA) | ||
| Hydrochloric Acid | ||
| Ammonium Hydroxide | ||
| Hydrofluoric Acid | ||
| Nitric Acid | ||
| Phosphoric Acid | ||
| Sulfuric Acid | ||
| Other Product Types | ||
| By Application | Semiconductor | Cleaning |
| Etching | ||
| Integrated Circuit (IC) Manufacturing | ||
| Printed Circuit Board (PCB) Manufacturing | ||
| Other Applications | ||
| By Geography | Asia-Pacific | China |
| India | ||
| Japan | ||
| South Korea | ||
| ASEAN Countries | ||
| Rest of Asia-Pacific | ||
| North America | United States | |
| Canada | ||
| Mexico | ||
| Europe | Germany | |
| United Kingdom | ||
| France | ||
| Italy | ||
| NORDIC Countries | ||
| Rest of Europe | ||
| South America | Brazil | |
| Argentina | ||
| Rest of South America | ||
| Middle East and Africa | Saudi Arabia | |
| South Africa | ||
| Rest of Middle East and Africa | ||
Key Questions Answered in the Report
What is the size of the wet chemicals for electronics and semiconductor applications market?
The wet chemicals for electronics and semiconductor applications market stands at USD 4.89 billion in 2026 and is projected to reach USD 6.93 billion by 2031.
Which product type led demand in 2025?
Hydrogen peroxide led product demand with 27.18% share in 2025 because it is used in critical cleaning and stripping formulations.
Which application is projected to advance fastest through 2031?
Semiconductor is projected to advance at an 8.43% CAGR through 2031 as cleaning and etching needs rise with node complexity.
Which region is projected to advance fastest through 2031?
Asia-Pacific is projected to advance at an 8.27% CAGR through 2031.