
United States Home Decor Market Analysis by Mordor Intelligence
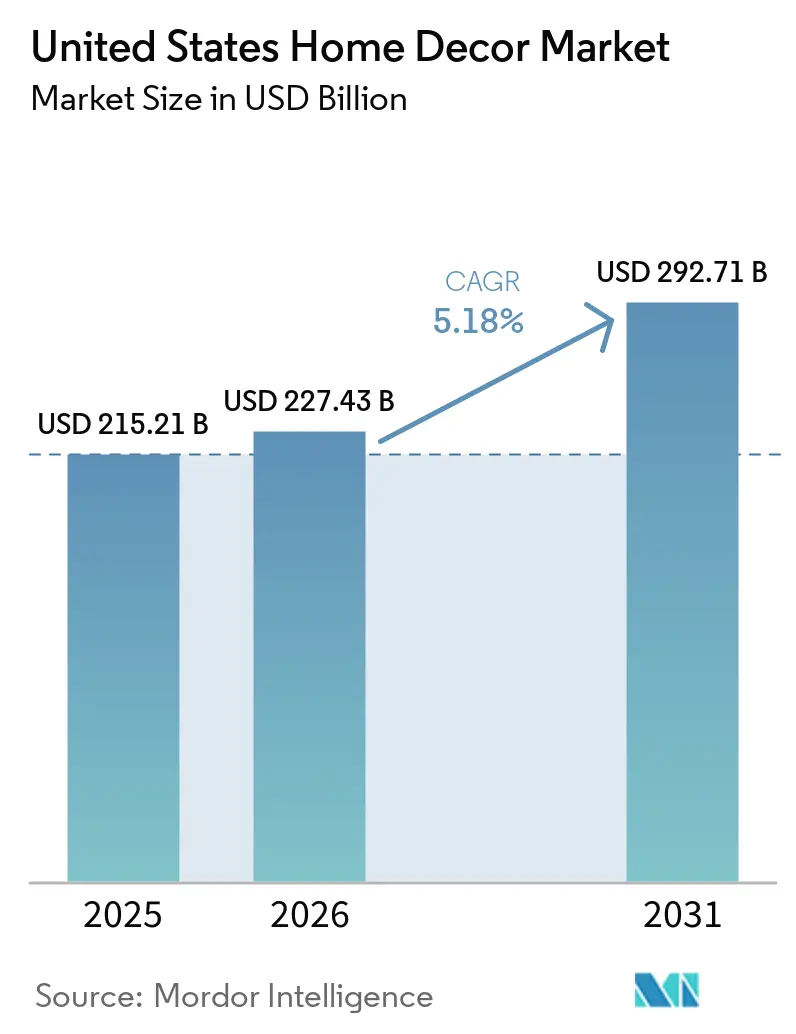
The United States home decor market size was valued at USD 227.4 billion in 2026 and estimated to grow from USD 239.2 billion in 2027 to reach USD 303.3 billion by 2032, at a CAGR of 4.86% during the forecast period (2027-2032).
In the United States, renovation and home-based work create décor purchase occasions that can persist when moving-related furniture spending is constrained. Online selling, local showrooms and assisted ordering give retailers several routes from room selection to a completed purchase. For furniture and lighting suppliers, that combination favors clear room applications and execution across those channels. U.S. tariff actions affecting imported furnishings and materials, which began in April 2025, have added cost pressure for furniture suppliers, so fulfillment and cost control matter as much as range breadth.
Key Report Takeaways
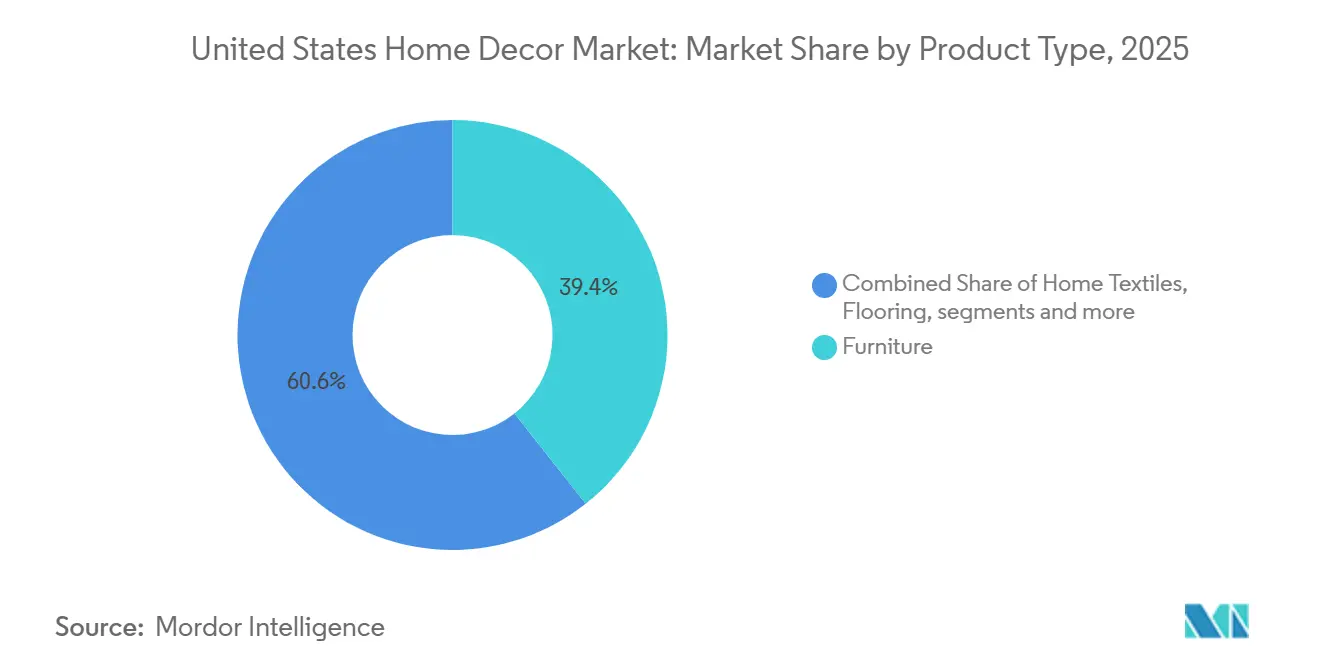
- By product type, furniture held a 39.64% United States home decor market share in 2026 and is also forecast to grow fastest, at a 5.7% CAGR during 2027-2032.
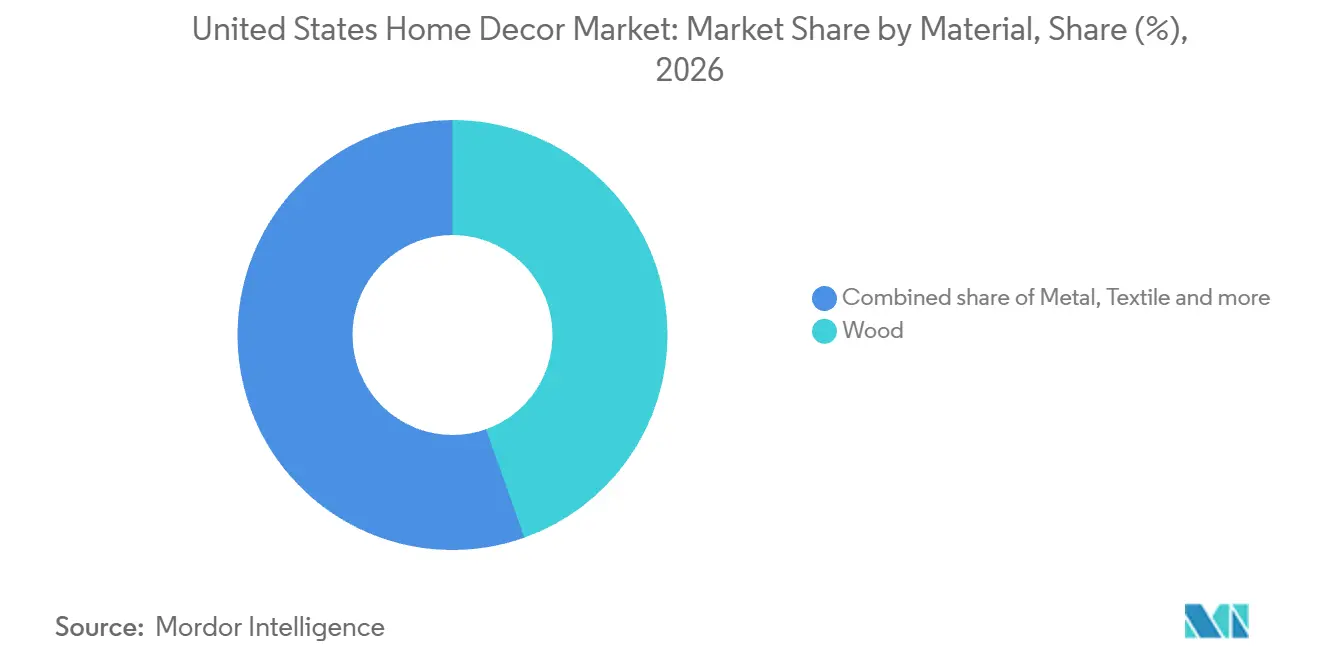
- Among materials, wood led with a 44.57% share of the United States home decor market size in 2026 and is forecast to grow fastest, at a 5.2% CAGR during 2027-2032.
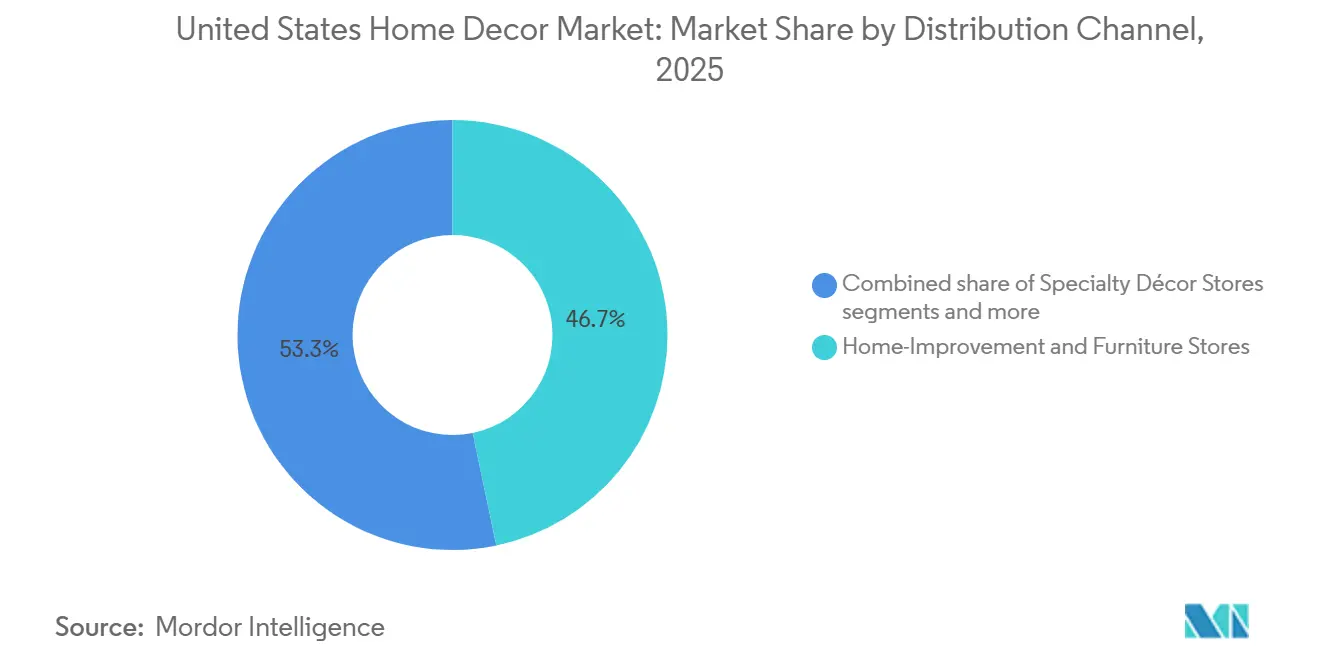
- Distribution channels were led by home-improvement and furniture stores with a 45.97% market share in 2026, while online retail is forecast to grow fastest, at a 12.2% CAGR during 2027-2032.
- By price range, mass-priced products held a 68.34% market share in 2026, while premium and luxury products are forecast to grow fastest, at an 8.8% CAGR during 2027-2032.
- Living rooms led room-based demand with a 30.17% market share in 2026, whereas home offices are forecast to grow fastest, at a 10.9% CAGR during 2027-2032.
- Across geographies, the Southeast led with a 24.43% market share in 2026, and the West is forecast to grow fastest, at an 8% CAGR during 2027-2032.
Note: Market numbers in this report are based on Mordor Intelligence's proprietary estimation framework, which combines nine months of actuals with Q4 projections for base year 2026.
Market Trends and Insights
Drivers Impact Analysis of United States Home Decor Market*
| Driver | (~) % Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
|---|---|---|---|
| Aging United States Housing Stock Supporting Renovation-Driven Décor Spending | +2.4% | Nationwide | Long term (≥ 4 years) |
| Expansion in Single-Family Housing Starts and Existing Home Sales | +1.8% | Nationwide | Medium term (2-4 years) |
| Remote Work Driving Increased Home Office Décor Investment | +1.3% | Nationwide | Medium term (2-4 years) |
| Social Media–Influenced Trends Accelerating Décor Purchase Cycles | +0.9% | Nationwide | Short term (≤ 2 years) |
| Omnichannel and AR Shopping Enhancing the Customer Experience | +0.7% | Nationwide | Medium term (2-4 years) |
| Sustainability and Eco-Conscious Preferences Driving Green Décor Demand | +0.4% | Nationwide | Long term (≥ 4 years) |
| Source: Mordor Intelligence | |||
Aging United States Housing Stock Supporting Renovation-Driven Décor Spending
The décor opportunity around an aging housing base lies in refreshes that preserve the dwelling while changing a room's appearance and use. NAHB's analysis of 2024 American Community Survey data found that the median age of U.S. owner-occupied homes reached 42 years, up from 31 years in 2005, and 47% were at least 45 years old. Against that older base, Houzz found that 52% of surveyed U.S. Houzz-user homeowners decorated in 2025, down from 54% in 2024. That participation level supplies a substantial customer base even as the share undertaking decoration eases. Within a renovation, replacement finishes and furnishings can become connected decisions for the same room. Winning the finishing stage of a room project can therefore matter more than encouraging a household to redecorate more often.
Expansion in Single-Family Housing Starts and Existing Home Sales
Existing-home turnover creates furnishing occasions even when annual sales run slightly below the prior year. Existing-home sales reached a seasonally adjusted annual rate of 3.99 million in September 2026, up 1.5% from August but down 2.2% from September 2025. That series includes single-family homes, condominiums and co-ops, giving décor suppliers several types of potential move-related demand. A home transfer can create a reason to reconsider furniture placement, lighting and room finishes. Converting a moving occasion into a specific room purchase determines how much turnover translates into décor demand. September's monthly improvement supports that opportunity, while the annual decline argues against treating it as a broad replacement boom.
Remote Work Driving Increased Home Office Décor Investment
Home-office demand can extend beyond a dedicated study when paid work occupies part of a domestic room. In the Federal Reserve's 2025 survey, 39% of U.S. workers reported working from home at least some of the preceding week, similar to 2024. This established user base gives task seating, work surfaces and related lighting a use case independent of moving house. For a household using a room for both work and relaxation, an office purchase also becomes a décor decision. Suppliers can address that overlap through coordinated work and living-room furnishings. Upgrading a workspace already used at home can support furnishing demand even without an expanding remote-work population.
Social Media–Influenced Trends Accelerating Décor Purchase Cycles
Social shopping puts the commercial emphasis on turning a style encounter into a clearly specified furniture offer. In KPMG's August to September 2025 U.S. survey, 8% of 1,024 social-shopping respondents selected furniture among their top 3 categories purchased or planned for purchase on Instagram, Facebook and TikTok. For a furniture supplier, that creates a potential acquisition route alongside conventional retail search. The combination of purchases and plans gives suppliers reason to address prospective buyers as well as existing social furniture customers. Furniture's minority position among respondents' selections favors testing a focused social assortment before committing a full range.
Restraints Impact Analysis of United States Home Decor Market*
| Restraint | (~) % Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
|---|---|---|---|
| Fluctuating Lumber and Textile Costs Pressuring Margins | -0.8% | Nationwide | Short term (≤ 2 years) |
| Higher Mortgage Rates Constraining Home Turnover and Spending | -1.1% | Nationwide | Medium term (2-4 years) |
| Supply Chain Bottlenecks Elevating Lead Times and Inventory Expenses | -0.4% | Nationwide | Short term (≤ 2 years) |
| Rising Inflation Reducing Consumer Discretionary Purchases | -0.3% | Nationwide | Short term (≤ 2 years) |
| Source: Mordor Intelligence | |||
Fluctuating Lumber and Textile Costs Pressuring Margins
United States tariff actions beginning in April 2025 raised Hooker Furnishings' costs for imported fabrics and other raw materials.[1] The furniture maker warned that sales and margins could suffer if it could not offset those costs. For an upholstered-furniture supplier, fabric cost exposure affects the economics of a finished item before any change in retail demand. Absorbing an increase reduces the room available for margin, while passing it through can make the purchase harder to justify. In the quarter ended August 2, 2026, Hooker reported lower imported-material costs and partial tariff recoveries, but said recoveries did not make it whole. That incomplete recovery leaves a cost burden even after the immediate input pressure eases.
Higher Mortgage Rates Constraining Home Turnover and Spending
Consumer Edge reported that the average 30-year mortgage rate moved above 7% in the week of September 29, 2026, the first time since early 2025. Consumer Edge found that elevated interest rates, limited turnover and affordability concerns weighed on broader home and garden spending in 2025, postponing major investments. Its September 2026 analysis found furniture-led retailers lagging décor- and housewares-oriented retailers relative to the broader category in data through August.[2] The same analysis warned that higher mortgage rates could further constrain turnover and major furnishing purchases. This makes a retailer's exposure to moving occasions commercially significant even without an absolute fall in its sales. Smaller refreshes may remain feasible, while a retailer can lose a larger furnishing occasion when a move is deferred.
*Our forecasts treat driver/restraint impacts as directional, not additive. The impact forecasts reflect baseline growth, mix effects, and variable interactions.
United States Home Decor Market Segment Analysis
By Product Type:
Furniture Links Order Growth With FulfillmentFurniture accounted for a 39.64% share of the United States home decor market size in 2026, making it the largest segment, and is forecast to be the fastest-growing segment at a 5.7% CAGR during 2027-2032. Smith Leonard reported that new orders among its residential furniture survey participants rose 5% through July 2026 from the same period in 2025. New orders can give manufacturers a view of demand ahead of the eventual shipment. Order growth ahead of shipments can therefore raise the importance of scheduling and delivery promises in the customer offer. The value of stronger intake depends on the supplier's ability to turn it into furniture delivered to the buyer.
Smith Leonard also reported that shipments among its residential furniture survey participants rose 1% through July 2026 from the same period in 2025, a smaller gain than new orders. Within flooring and carpets, Floor & Decor's Retail segment sells hard-surface flooring to homeowners, installers and commercial businesses through U.S. stores and its website. Its homeowner customers include do-it-yourself buyers and those selecting products for professional installation. That split makes product selection and installation separate potential points of influence. For residential flooring suppliers, supporting the homeowner's choice alongside professional installation requirements can keep an offer relevant across both buying routes.

By Material:
Wood Combines Established Scale With Planned IntegrationWood represented a 44.57% United States home decor market share in 2026, making it the largest segment, and is forecast to be the fastest-growing segment at a 5.2% CAGR during 2027-2032. U.S. hardwood flooring sales at the first point of distribution totaled USD 1.77 billion in 2025, down 3.8% from 2024. That flooring result makes application exposure an important qualification to the broader material outlook. A flooring-focused supplier therefore has to win business within a pressured application, even when the broader wood category retains a strong position.
In July 2026, James & James LLC announced development of a hardwood furniture facility in Heber Springs, Arkansas. The planned expansion combines its existing direct-to-consumer solid wood furniture manufacturing with lumber milling and expanded business serving interior designers and other design professionals. That integration could give the furniture maker closer control over the connection between material preparation and a designer's specification. Design professionals can become the connection between an integrated wood manufacturer and a coordinated residential furnishing order.
By Distribution Channel:
Broad Retail Reach Meets Online ExpansionHome-improvement and furniture stores were the largest segment, with a 45.97% market share in 2026. NRF ranked The Home Depot fifth and Lowe's Companies ninth among U.S. retailers for 2025, with U.S. sales of USD 154.7 billion and USD 83.96 billion. Those broad retail businesses connect décor distribution with a wider home-improvement selling occasion. For a décor supplier, placement within such a business can bring individual room products into a larger household project.
Online retail is forecast to be the fastest-growing segment, at a 12.2% CAGR during 2027-2032. Bob's Discount Furniture reported e-commerce channel revenue of USD 107.3 million for the fiscal quarter ended June 28, 2026, up 24.1% year over year. Its result shows an online business developing within an omnichannel furniture retailer. Participation in digital growth can therefore include selling through an established retailer's online channel.
By Price Range:
Mass Reach Coexists With Premium GrowthMass-priced products were the largest segment, with a 68.34% market share in 2026. Bob's Discount Furniture, a national omnichannel retailer of value home furnishings, operated 218 showrooms across 27 U.S. states as of June 28, 2026. That footprint illustrates the broad geographic reach available through a seller explicitly positioned around value. A manufacturer serving this tier can use that reach to offer repeatable furniture designs across many local selling locations. Access to many showrooms through one account makes the retailer's range decision more consequential than a single local placement.
Premium and luxury décor is forecast to be the fastest-growing segment, at an 8.8% CAGR during 2027-2032. Arhaus, a premium home-furnishings brand, reported company-wide second-quarter 2026 net revenue of USD 385 million, up 7.4% from the second quarter of 2025. During the quarter it completed 4 showroom projects, comprising 2 new showrooms, one relocation and one expansion. The mix combines additional locations with changes to existing selling space, giving a premium retailer several ways to develop physical access.
By Room:
Living-Room Projects Anchor Spending as Workspaces DevelopThe living room was the largest segment, with a 30.17% market share in 2026. Houzz's survey of U.S. homeowner users put median living-room renovation project spending at USD 5,000 in 2025, up from USD 4,000 in 2024. That higher project median points to a room-level selling occasion with several possible levels of completion. A furniture retailer can build an offer around a core seating purchase and let the household choose complementary elements within the project.
The home office is forecast to be the fastest-growing segment, at a 10.9% CAGR during 2027-2032. Houzz reported median home-office renovation project spending of USD 2,000 among surveyed U.S. renovating homeowners in 2025, up from USD 1,300 in 2024. That increase creates a room-specific setting for work-oriented furnishings within residential improvement. Kitchen and dining have a separate upgrade occasion, as 78% of surveyed U.S. Houzz-user homeowners who completed, were undertaking or planned kitchen renovations in 2025-2026 upgraded lighting fixtures. These distinct project needs favor offers organized around the room's task, connecting workplace function or kitchen lighting with a defined residential use.
Geography Analysis
Southeast Home Decor Market
The Southeast was the largest region, accounting for 24.43% of the United States home decor market size in 2026. In September 2026, 1915 South, an independent Ashley licensee, opened its 41st Ashley showroom in Harvey, Louisiana. It was the company's ninth Louisiana store and its first in the Greater New Orleans area. That combination illustrates how an established regional retailer can add local access while retaining a common furniture brand. For suppliers pursuing this channel, the licensed showroom operator can be a distinct commercial relationship from the national brand, making local retail execution relevant to the region's furnishing distribution.
West Home Decor Market
The West is forecast to be the fastest-growing region, at an 8% CAGR during 2027-2032. Sundays Furniture opened a 2,100-square-foot showroom in Santa Monica, California, in late June 2026, its second Southern California showroom after Pasadena. Residential-style settings presented living-room, dining-room and bedroom furnishings alongside lighting, linens and other décor, bringing several product categories into a compact local selling space. Phoenix authorities authorized 10,395 new privately owned housing units in 2025, 1,398 more than in 2024, identifying a potential pipeline for furnishing newly built homes.
The Northeast includes IKEA's small-format Syracuse store in New York, where accessories are available for same-day takeaway and larger furniture is available through delivery or pick-up. In the Midwest, Gardner White opened GW HOME in downtown Detroit in June 2025, combining furniture, décor, art and accessories with local artist and brand collaborations. In the Southwest, IKEA U.S. opened a small-format store in Webster, Texas, in June 2026 with 4,800 products available for immediate takeaway. These examples show different ways of connecting a local furnishing encounter with the eventual purchase. Takeaway in Syracuse and Webster makes local stock availability central to the offer, while Detroit's artist collaborations give locally differentiated décor a route into the assortment.
Regulatory Framework and Outlook
Selected jurisdictions are compared from the perspective of an upholstered-furniture manufacturer, including composite-wood obligations where applicable. Product construction and material choice determine which safety and emissions requirements apply. Beginning January 1, 2027, California will prohibit manufacturing, selling, offering or distributing new, previously unowned upholstered furniture containing textile fiberglass, excluding mattress stitching thread or fiber and specified corespun or sheathed yarns.[3] The restriction also covers replacement components used by custom upholsterers.
Regulatory Table of United States Home Decor Market
| Decision factor | United States | California |
|---|---|---|
| Primary authority | Consumer Product Safety Commission; Environmental Protection Agency | Bureau of Household Goods and Services |
| Key instruments or direction | 16 CFR Part 1640 and incorporated TB 117-2013; TSCA Title VI and 40 CFR Part 770 | Business and Professions Code §§ 19101 and 19101.5 |
| Commercial effect | Smolder-resistance compliance for covered upholstered furniture; emissions controls for covered composite-wood products | Covered flame retardants restricted above 1,000 ppm, subject to statutory component and fiber exceptions; adopted textile-fiberglass restriction |
| Current policy attractiveness | Medium | Low |
| Future direction of policy attractiveness | No change | Hardening |
| Source: Mordor Intelligence | ||
The federal Medium rating reflects a defined compliance baseline for smolder resistance and emissions from covered composite wood. EPA's February 2026 proposal would update incorporated test standards and add a small-scale quality-control method without tightening emission limits. That technical focus supports No change for manufacturers' underlying product obligations. California's 1,000 ppm limit on covered flame-retardant chemicals, in force since January 1, 2020, supports its Low rating, while the January 2027 textile-fiberglass restriction on new upholstered furniture and replacement components supports Hardening.
Value Chain Stages
Value capture differs across product manufacturing, wholesale distribution, retail selection and delivery to the home. Integrated producers such as Mohawk and Ethan Allen connect several of these activities, allowing commercial control to extend beyond making the product. That structure makes the handoff between production availability and local fulfillment a strategic choice for suppliers serving residential buyers.
Value Chain Analysis Table of United States Home Decor Market
| Primary activity | Key participants | Value capture | Bottleneck | Resilience response |
|---|---|---|---|---|
| Product manufacturing | Flooring manufacturers such as Mohawk Industries Inc.; furniture manufacturers such as Ethan Allen Interiors Inc. | Sales of manufactured flooring and furniture | Tariff-related cost exposure | Price increases and supply-chain optimization, as used by Mohawk in 2025 |
| Wholesale distribution | Integrated distributors such as Mohawk Industries Inc. and Ethan Allen Interiors Inc. | Wholesale merchandise sales | Coordination between distribution points and downstream delivery centers | Match replenishment to the receiving channel's product and delivery requirements |
| Retail selection and sale | Store and online retailers such as The Home Depot Inc. | Retail merchandise sales | Coordinating product availability across physical and digital channels | Align channel assortment with replenishment and fulfillment capacity |
| Home delivery | Retail fulfillment operators such as The Home Depot Inc.; furniture delivery operators such as Ethan Allen Interiors Inc. | Fulfilled merchandise sales | Delivery-speed requirements across stocking locations | Route orders from the best shipping location, as practiced by The Home Depot |
| Source: Mordor Intelligence | ||||
In fiscal 2025, The Home Depot invested in inventory, technology and nearly 200 last-mile assets, with more than half of stocked-product deliveries arriving the same day or next day. That performance connects the delivery proposition to an operating network rather than to the online storefront alone. For smaller suppliers, coordinating access to such a network can matter as much as extending the product range.
Competitive Landscape
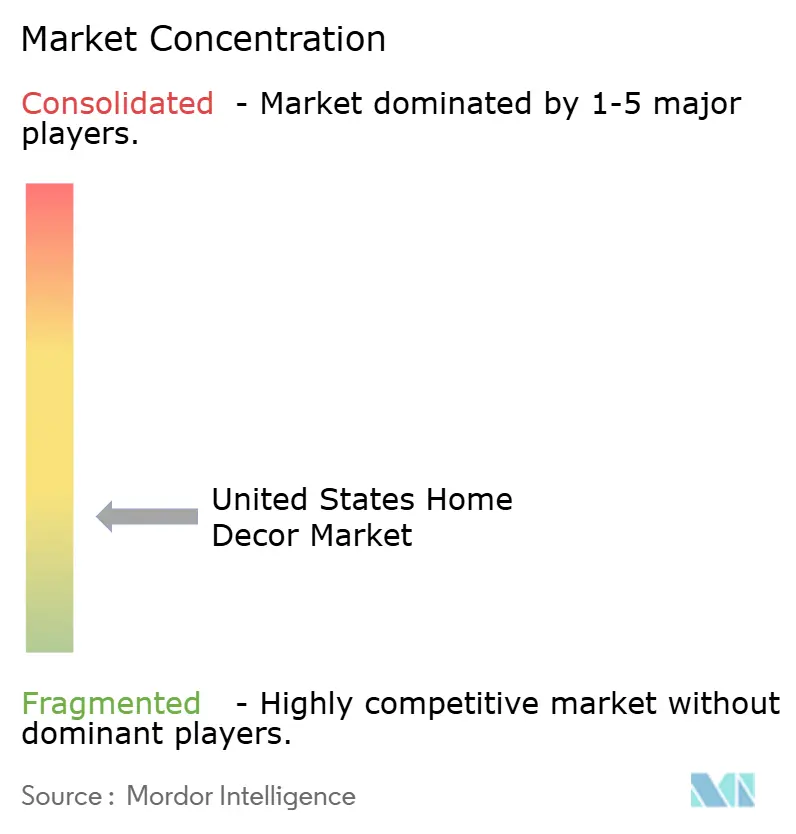
Competition is fragmented across broad home improvement chains, furnishing specialists and online home retailers with different ways of reaching the household. The Home Depot Inc. and Lowe’s Companies Inc. operate broad home improvement retail businesses. IKEA USA (Ingka Holding), Williams-Sonoma Inc. and Wayfair Inc. extend the field across home-furnishings retail, furnishing and housewares brands, and online home-product sales. Williams-Sonoma reported company-wide fiscal 2025 net revenues of USD 7.81 billion, showing the scale of a furnishings specialist. The Home Depot sells décor alongside building materials and installation services, making access to a broader household project a competitive channel advantage.
In fiscal 2025, IKEA U.S.'s Remote Customer Meeting Point supported more than 3 million people and generated more than USD 100 million in remote sales. Its phone, chat, social media and specialized services connect customer assistance with an operating sales channel. That combination gives a shopper a route from discussion to ordering without requiring the entire interaction to take place in a store. Connecting advice with an order can give service staff a role in selling furnishings, making customer assistance an operating capability alongside product selection and remote order completion.
Wayfair reported U.S. home-product net revenue of USD 3.1 billion in the second quarter of 2026, up 8.7% year over year. That performance keeps an online home retailer commercially relevant alongside store-based and assisted selling formats. California's adopted textile-fiberglass restriction will cover retailers, importers and online sellers as well as manufacturers of new, previously unowned upholstered furniture sold into California. It reaches constituent components, subject to exceptions for mattress stitching thread or fiber and corespun or sheathed yarns. For an online retailer, checking covered components before offering furniture can prevent a supplier's material choice from becoming a California sales restriction.
United States Home Decor Industry Leaders
-
The Home Depot Inc.
-
Lowe’s Companies Inc.
-
IKEA USA (Ingka Holding)
-
Williams-Sonoma Inc.
-
Wayfair Inc.
- *Disclaimer: Major Players sorted in no particular order
United States Home Decor Market Companies Covered in this Report
- The Home Depot Inc.
- Lowe’s Companies Inc.
- IKEA USA (Ingka Holding)
- Williams-Sonoma Inc.
- Wayfair Inc.
- Target Corporation
- TJX Companies (HomeGoods)
- Amazon.com Inc.
- Ashley Furniture Industries LLC
- Ethan Allen Interiors Inc.
- La-Z-Boy Inc.
- RH (Restoration Hardware)
- Crate & Barrel Holdings Inc.
- At Home Group Inc.
- Haverty Furniture Companies Inc.
- Bob’s Discount Furniture LLC
- Lamps Plus Inc.
- Floor & Decor Holdings Inc.
- Mohawk Industries Inc.
- Pier 1 Imports Omni, Inc.
Key Opportunities for Market Participants
Household refresh purchases offer home-decor suppliers a route to consumers who are improving existing rooms. Consumer Edge reported decor-, housewares- and smaller-purchase-oriented retailers outperforming the broader home-furnishings category through August 2026, while furniture-led retailers fell behind. That relative performance supports testing smaller residential purchases alongside large furniture offers.
Market Opportunities Table of United States Home Decor Market
| Opportunity | Why now | Buyer / lead segment | Recommended play | Main barrier | Likely beneficiaries |
|---|---|---|---|---|---|
| Room-refresh decor assortments | Relative strength in retailers focused on smaller home purchases | Households refreshing existing rooms | Offer coordinated decorative accents at accessible purchase sizes | Converting relative category strength into sales for a particular range | Home-decor brands and residential retailers |
| Decor additions to existing furniture | Furniture-led retailers lagged smaller-purchase-oriented retailers | Residential buyers retaining their furniture | Merchandise decor that complements existing room settings | Matching household style and available spending | Decor manufacturers and home-furnishings retailers |
| Phased household refresh offers | Housing-turnover pressure may favor improvements to existing homes | Households planning incremental home updates | Organize coordinated decor purchases by room and care task | The spending shift depends on household conditions | Retailers with repeat-purchase residential decor ranges |
| Source: Mordor Intelligence | |||||
The central opening is a sequence of smaller household decor purchases that refresh an existing home. A retailer can organize coordinated ranges by room so buyers can update one space before committing to another. Consumer Edge identified a potential shift toward refreshing existing homes if higher mortgage rates continue to constrain housing turnover. Suppliers can test these ranges through residential retail channels while treating that spending shift as conditional.
Recent Industry Developments in United States Home Decor Market
- Sep 2026: 1915 South, an independent Ashley licensee, opened its 41st Ashley showroom in Harvey, Louisiana.
- Jul 2026: James & James LLC announced development of a hardwood furniture facility in Heber Springs, Arkansas, with an investment of more than USD 9.4 million. The planned expansion combines solid wood furniture manufacturing with lumber milling and expanded trade business.
- Jun 2026: IKEA U.S. opened a small-format store in Webster, Texas, showcasing more than 7,000 products, including 4,800 available for immediate takeaway.
United States Home Decor Market Report Scope and Research Methodology
Market Definition and Coverage
The United States home decor market measures annual retail spending on home decor products purchased for residential use in the United States. Value is counted at the first retail sale across physical and online channels, including products used throughout the home and in outdoor living areas.
Scope exclusions: Major appliances, consumer electronics, core building materials sold separately, second-hand or rental items, and separately sold installation or interior-design services are excluded.
Segments Covered in This Report
- By Product Type
- Furniture
- Home Textiles
- Flooring & Carpets
- Wall Décor (Paintings, Wallpapers)
- Lighting Fixtures
- Decorative Accessories (Vases, Candles, Clocks)
- By Material
- Wood
- Metal
- Textile
- Glass
- Plastic & Other Synthetics
- Stone & Ceramic
- By Distribution Channel
- Home-Improvement & Furniture Stores
- Specialty Décor Stores
- Supermarkets & Hypermarkets
- Online / E-commerce
- Others (Boutiques, Art Galleries)
- By Price Range
- Mass
- Premium / Luxury
- By Room
- Living Room
- Bedroom
- Kitchen & Dining
- Bathroom
- Home Office
- Outdoor & Patio
- By Geography
- Northeast
- Midwest
- Southeast
- Southwest
- West
Data Sources, Market Sizing, and Validation
Desk Research
Illustrative public sources include the U.S. Census Bureau's Monthly Retail Trade data for store sales and inventories, its Quarterly Retail E-Commerce Report for online retail trends, its Building Permits Survey for residential construction indicators, and the Bureau of Economic Analysis's consumer spending series for household expenditure context. The Census Bureau notes that sales by store type do not measure all sales of a commodity, so those figures serve as channel signals rather than a complete home decor total.
Company filings, investor materials, earnings releases and reputable business press can add product, channel, pricing and operating context and help cross-check broader public indicators. These sources are not exhaustive, and further sources inform collection, validation and clarification.
Primary Interviews and Surveys
Primary research is structured around interviews and surveys with United States home decor manufacturers, retailers, distributors and relevant industry specialists, including senior executives, functional leaders and managers. Respondents assess the product, channel, material, price, room and regional assumptions drawn from secondary research and identify changes in purchasing, fulfillment and costs. Analysts investigate gaps through focused follow-up questions and compare responses with independent public indicators and sampled supplier or channel evidence before incorporating them into the estimate.
Distribution of primary research fieldwork respondents
| Company type | Respondent position | Region |
|---|---|---|
| Top tier: 30% | CXOs: 20% | |
| Mid tier: 50% | Functional/Unit leaders: 35% | |
| Smaller Players: 20% | Managers: 45% |
Market-Sizing & Forecasting
The estimate starts with a top-down view of United States retail spending on residential home decor, expressed in retail value, then checks whether product and channel evidence supports the resulting total. Housing starts and existing home sales indicate new-home and moving-related purchase occasions, renovation activity indicates refresh demand, household spending and retail sales indicate the capacity and timing of purchases, and e-commerce trends help assess channel shifts. Furniture and material input prices help distinguish price movement from changes in units sold. A multivariate regression can relate these indicators to historical market movement, with scenario analysis used where housing, inflation or input-cost paths remain uncertain.
Product, material, distribution channel, price range, room and United States regional shares are built from category sales evidence, retailer and supplier disclosures, trade data and qualified expert input, with each classification assigned once within its axis. Selective bottom-up checks use sampled average selling prices multiplied by estimated unit volumes or supplier and retailer roll-ups to test category and channel totals, rather than replace the top-down estimate. Where sampled coverage or unit data are missing, analysts retain a documented range, test alternative assumptions against the market total and avoid extending a partial sample as if it covered the full market. Experts can review the selected drivers and forecast assumptions at variable level, while analysts reconcile their input with the time series and independent indicators before adopting a change.
Data Validation & Update Cycle
Analysts triangulate retail sales, household spending, housing activity, company disclosures and primary research, checking that the measures align with the first-retail-sale boundary and do not count wholesale sales or services. They review anomalies, year-over-year shifts, share totals and differences between top-down estimates and selective supplier or channel checks, then resolve material variances through source review, assumption testing or targeted respondent re-contact before sign-off. The model is refreshed annually, revisited between cycles after material housing, price, trade or retail events, and given a fresh source and calculation review immediately before delivery. Re-contact is triggered when new evidence conflicts with a respondent's earlier explanation or leaves a material gap unresolved.
Mordor Intelligence's US Home Decor Market Estimate Compared With Other Published Estimates
The United States home decor market measures annual retail spending on home decor products purchased for residential use in the United States. Product, material, distribution channel, price range, room and United States regional shares are built from category sales evidence, retailer and supplier disclosures, trade data and qualified expert input, with each classification assigned once within its axis.
Key Gap Drivers are addressed through a consistent transaction boundary, market-specific demand inputs and cross-checks across the study. Analysts triangulate retail sales, household spending, housing activity, company disclosures and primary research, checking that the measures align with the first-retail-sale boundary and do not count wholesale sales or services.
Benchmark comparison
| Source | Market Size | Gaps in Research Methodology |
|---|---|---|
| Mordor Intelligence | USD 239.2 B (2027) | |
| Global Consultancy A | USD 191.5 B (2025) | At its 2025 base, this estimate is 19.9% below this report's 2027 value of USD 239.2 B, 2 years later. Its 2025 base and 3.23% projected annual growth through 2034 place its published series below a later-year estimate. |
| Industry Publisher B | USD 145.52 B (2025) | At its 2025 base, this estimate is 39.2% below this report's 2027 value of USD 239.2 B, 2 years later. Its 2025 base and 4.32% projected annual growth through 2034 place its published series below a later-year estimate. |
Mordor Intelligence ties the estimate to the study’s defined coverage and demand model. Analysts triangulate retail sales, household spending, housing activity, company disclosures and primary research, checking that the measures align with the first-retail-sale boundary and do not count wholesale sales or services.
Key Questions Answered in the Report
What is the United States home decor market size and growth outlook?
The size is estimated at USD 239.2 billion in 2027 and projected to reach USD 303.3 billion by 2032, at a 4.86% CAGR during 2027-2032.
What supports demand for home décor in the United States?
Renovation and home-based work support purchase occasions. In the Federal Reserve's 2025 survey, 39% of U.S. workers worked from home at least part of the preceding week.
Which product category leads home décor sales?
Furniture led with a 39.64% market share in 2026 and is forecast to grow at a 5.7% CAGR during 2027-2032.
Which companies are major competitors in home décor?
Major competitors include The Home Depot Inc., Lowe’s Companies Inc., IKEA USA (Ingka Holding), Williams-Sonoma Inc. and Wayfair Inc.
What is a major constraint on furniture-led décor spending?
Consumer Edge warned in September 2026 that higher mortgage rates could further constrain housing turnover and major furnishing purchases.
Which U.S. region leads home décor sales, and where is growth fastest?
The Southeast held a 24.43% market share in 2026. The West is forecast to grow fastest, at an 8% CAGR during 2027-2032.