
United States Freight And Logistics Market Analysis by Mordor Intelligence
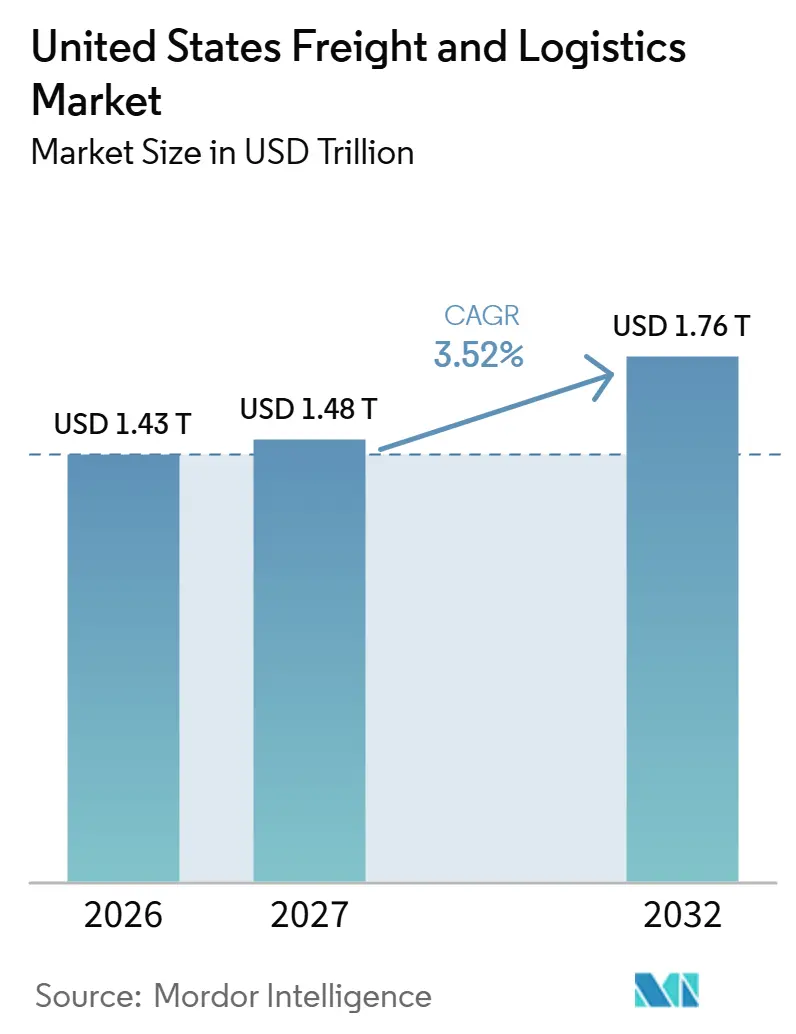
The United States freight and logistics market size was valued at USD 1.43 trillion in 2026 and estimated to grow from USD 1.48 trillion in 2027 to reach USD 1.76 trillion by 2032, at a CAGR of 3.52% during the forecast period (2027-2032).
In the United States, parcel demand and domestic production shifts underpin opportunities to serve additional delivery and industrial freight flows. Broader logistics offerings connect palletized freight with fulfillment, expanding the customer tasks a single provider can contest. Driver compensation and highway bottlenecks limit how efficiently that work can be served, placing pressure on service economics. Carriers' commercial gains consequently depend on adding service commitments where parcel and pallet flows can be handled within usable route capacity.
Key Report Takeaways
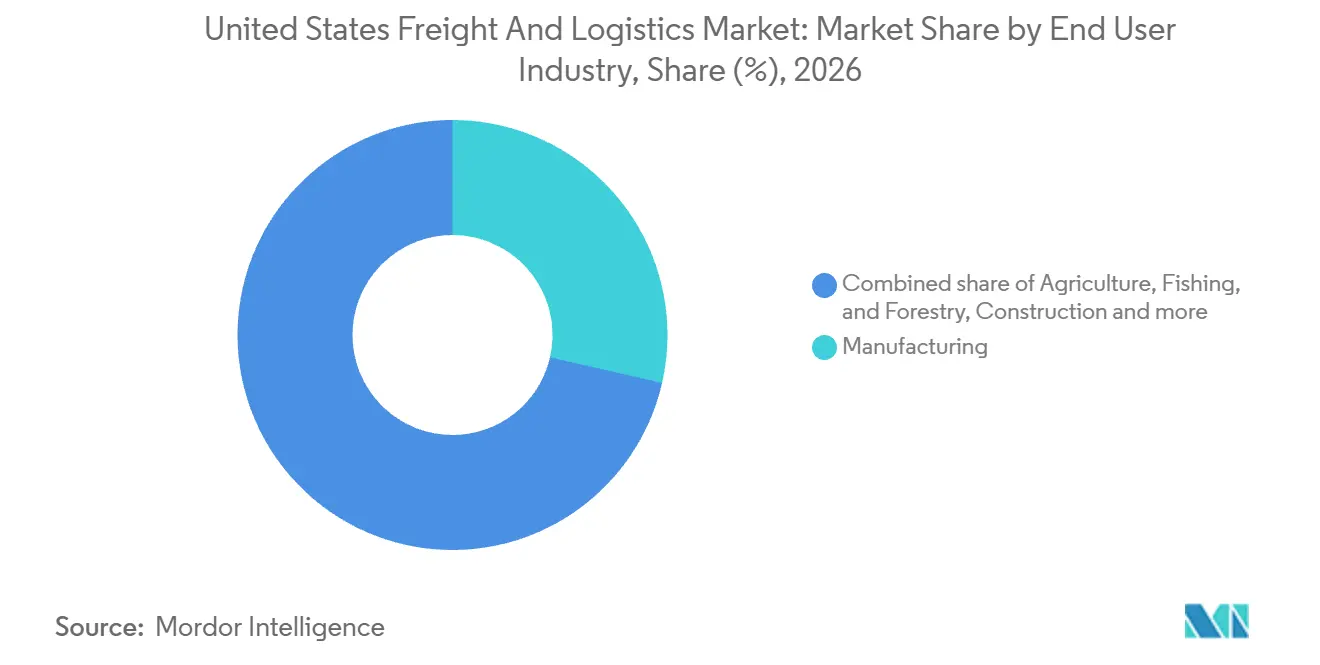
- By end user industry, manufacturing held a 28.58% United States freight and logistics market share in 2026, while wholesale and retail trade is the fastest-growing segment at a CAGR of 3.82% during 2027-2032.
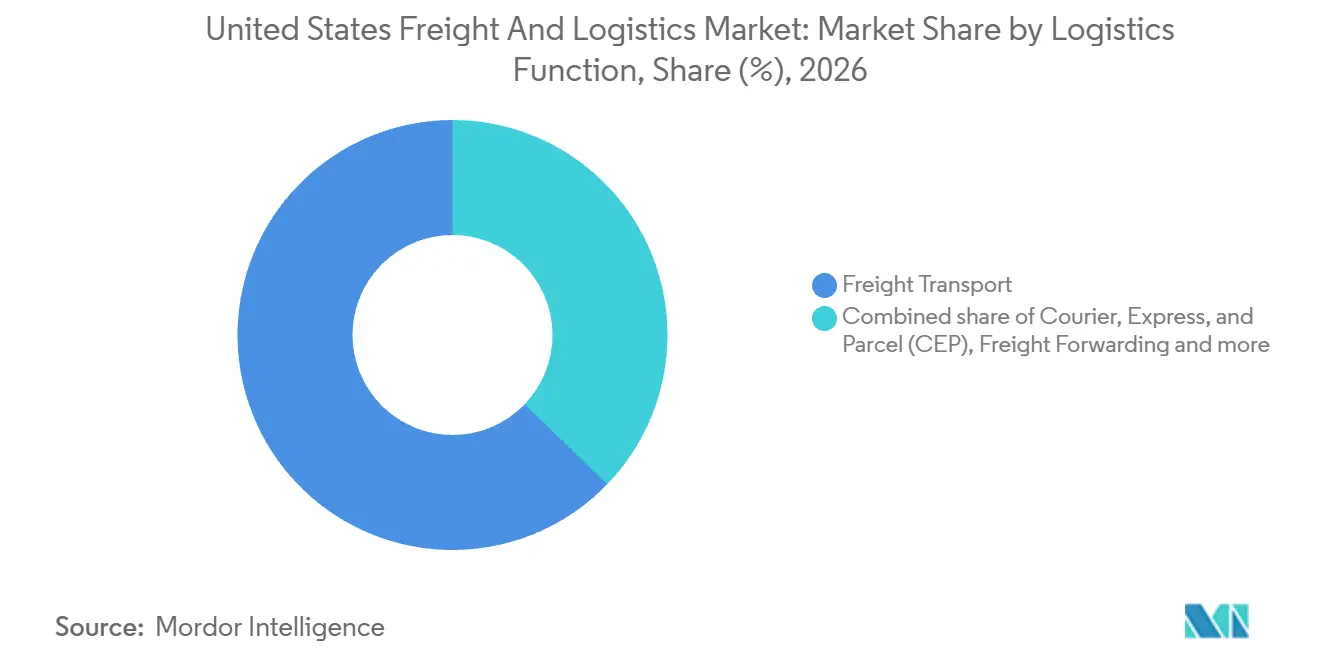
- Across logistics functions, freight transport accounted for a 62.8% share of the United States freight and logistics market size in 2026, and courier, express, and parcel services are forecast to grow fastest at a CAGR of 4.12% during 2027-2032.
- Geographically, California, Texas, and the Great Lakes together account for the largest share of U.S. freight and logistics activity, anchored by gateway and freight-network scale.
Note: Market numbers in this report are based on Mordor Intelligence's proprietary estimation framework, which combines nine months of actuals with Q4 projections for base year 2026.
Market Trends and Insights
Drivers Impact Analysis of United States Freight And Logistics Market*
| Driver | (~) % Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
|---|---|---|---|
| Explosive B2C E-Commerce Parcel Volumes | +1.8% | Nationwide | Short term (≤ 2 years) |
| Reshoring-Driven Domestic Manufacturing Freight Flows | +1.3% | Nationwide | Long term (≥ 4 years) |
| Expansion of 3PL/4PL Outsourcing Across Mid-Market Shippers | +1.1% | New York and Chicago | Medium term (2-4 years) |
| Infrastructure Investment and Jobs Act (IIJA) Funding | +0.8% | DeSoto County, Mississippi | Medium term (2-4 years) |
| Digital Freight Marketplaces and API-Based Capacity Aggregation | +0.5% | Nationwide | Short term (≤ 2 years) |
| Zero-Emission Truck Corridor Pilots (Hydrogen / BEV) | +0.15% | Southern California freight corridors | Long term (≥ 4 years) |
| Source: Mordor Intelligence | |||
Explosive B2C E-Commerce Parcel Volumes
Consumer-oriented parcel growth creates a demand opportunity at the operating-day level, where additional packages require handling and delivery capacity. FedEx's U.S. ground home delivery/economy average daily volume increased 5.7% in fiscal 2026, from 7.04 million packages in fiscal 2025 to 7.44 million. The company calculated that combined category's volumes using 5 days per week. The increase therefore describes a higher average processing requirement, making daily parcel throughput a relevant basis for matching service capacity to demand. The commercial opening lies in executing the extra home delivery/economy workload, with operating-day averages guiding the scale of the capacity response.
Reshoring-Driven Domestic Manufacturing Freight Flows
For freight providers, reshoring makes production location a commercial variable alongside the amount of goods produced. In the 2026 U.S. reshoring survey, 36% of OEM respondents reported having reshored or being actively engaged in additional reshoring, up from 29% in 2025.[1] The survey covered 118 OEMs and 131 contract manufacturers among 249 respondents. Its combination of completed moves and active projects points toward service opportunities unfolding at different stages of implementation. Relocated production can therefore give carriers a route-development opportunity centered on the new industrial location and its supply and delivery connections.
Expansion of 3PL/4PL Outsourcing Across Mid-Market Shippers
A growing outsourced-logistics revenue pool gives service providers a route to expand through customers’ fulfillment and transport requirements. U.S. third-party logistics and contract-logistics gross revenue reached USD 323.4 billion in 2025, up 5.0% year over year. That value increase supports a larger commercial service pool without establishing how much came from volumes, pricing or service mix. New York Puzzle Company selected Mochila Fulfillment as it sought to streamline and modernize fulfillment processes. Providers can compete for these outsourced assignments by connecting the customer’s fulfillment requirements with their delivery capabilities.
Infrastructure Investment and Jobs Act (IIJA) Funding
Federal infrastructure awards support logistics expansion by financing the access capacity on which commercial freight services depend. On October 1, 2026, USDOT awarded USD 426.7 million in FY 2026 INFRA Track 1 grants to 12 highway projects in 12 states. That pool included USD 44 million for Mississippi DOT's planned I-55/I-69 Freight Corridor Expansion in DeSoto County. The project would widen about 3 miles from 4 lanes to 10, improving access to Memphis International Airport and the FedEx World Hub. Completing the planned widening can enable more freight movement through the gateway's connecting road, making construction delivery the condition for translating the award into usable freight-service capacity.
Restraints Impact Analysis of United States Freight And Logistics Market*
| Restraint | (~) % Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
|---|---|---|---|
| Acute Long-Haul Driver Shortage and Wage Inflation | -0.9% | Nationwide | Short term (≤ 2 years) |
| Port, Rail-Ramp and Urban Congestion Bottlenecks | -0.65% | Nationwide | Medium term (2-4 years) |
| Cyber-Risk Insurance and Compliance Costs | -0.25% | Nationwide | Medium term (2-4 years) |
| “Nuclear” Jury Verdicts Driving Motor-Carrier Insurance Spikes | -0.4% | Nationwide | Short term (≤ 2 years) |
| Source: Mordor Intelligence | |||
Acute Long-Haul Driver Shortage and Wage Inflation
Driver compensation places a cost hurdle between truckload service expansion and commercially sustainable freight rates. For-hire truckload carriers paid dry van irregular-route employee drivers median annual compensation of USD 73,639 in 2025, 8.3% higher than in 2023.[2] The carrier sample varied between the studies, and the measure covers total compensation for that specific driver category. A higher compensation bill raises the revenue needed to sustain service, limiting carriers' room to reduce freight prices. On October 1, 2026, Schneider announced a 26% increase in driver-instructor positions to expand training and onboarding capacity across its U.S. training locations. That proposed capacity response would leave carriers bearing the compensation costs associated with the drivers they employ.
Port, Rail-Ramp and Urban Congestion Bottlenecks
Highway bottlenecks can separate the size of a truck fleet from the transport capacity it can actually deliver on affected lanes. In 2025, average peak-hour truck speeds across ATRI's top 100 U.S. highway bottlenecks were 33.2 mph, down 2.8% from 2024. A slower trip through one of these locations ties up both vehicle and driver time for a given cargo movement. Additional vehicles committed to the same route can therefore raise the asset and labor capacity required to complete that work without removing the location-specific delay. For carriers serving these lanes, the constraint is usable trip time, which limits how readily additional shipper demand can become additional freight-service output.
*Our forecasts treat driver/restraint impacts as directional, not additive. The impact forecasts reflect baseline growth, mix effects, and variable interactions.
United States Freight And Logistics Market Segment Analysis
By End User Industry:
Manufacturing Scale Meets Retail ConsolidationManufacturing accounted for a 28.58% share of the United States freight and logistics market size in 2026, making it the largest segment. U.S. manufacturers shipped USD 7.24 trillion in goods in 2025, up 1.7% from 2024.[3] Toyota Battery Manufacturing North Carolina, Toyota's in-house battery plant, began shipping batteries in April 2025. That shipment start provides an operating milestone for a manufactured product, linking production readiness to goods available for movement. Manufactured-goods shipments can create service revenue for logistics providers that secure movement contracts around an operating production flow and its delivery needs.
Wholesale and retail trade is forecast to grow at a CAGR of 3.82% during 2027-2032, making it the fastest-growing segment. In May 2026, Walmart announced a phased Prepaid Consolidation Program combining supplier shipments before distribution across its 42 U.S. regional distribution centers. Suppliers retain prepaid freight terms and arrange transportation, while Walmart manages consolidation and approved third-party logistics providers may participate. Eligibility prioritizes volume alignment and capacity expansion, requiring suppliers to explore whether they qualify. The opportunity for logistics suppliers lies in coordinating eligible inbound flows across that distribution network while preserving the supplier's responsibility for transportation.

By Logistics Function:
Transport Scale Supports Specialized Service ModelsFreight transport represented a 62.8% United States freight and logistics market share in 2026, making it the largest segment. U.S. railroads reported 11,508,797 carloads and 14,055,633 intermodal units in 2025, weeks 1-52, with each measure up 1.5% from 2024. ATA's advanced seasonally adjusted For-Hire Truck Tonnage Index showed tonnage up 0.9% in January-September 2026 versus the same 2025 period. The latter is a provisional survey-based measure dominated by contract freight, giving a distinct operating reference for road carriers. For road carriers, this combination places the commercial emphasis on serving established flows efficiently while the broader transport function retains its large revenue base.
Courier, express, and parcel (CEP) services are forecast to grow at a CAGR of 4.12% during 2027-2032, making this the fastest-growing segment. U.S. parcel volume reached 23.1 billion shipments in 2025, up 3.3% from 2024. That scale gives parcel operators a large pool of individual shipments over which to organize collection, handling, and delivery services. Freight forwarding has a different role, with U.S.-based ocean freight forwarders arranging international cargo movement, booking carrier space, and processing shipment documentation for shippers. The distinction leaves parcel operators competing over repeated shipment execution and ocean forwarders over international transport coordination, separating the services buyers commission.
Geography Analysis
California, Texas, and the Great Lakes Freight And Logistics Market
California, Texas, and the Great Lakes together account for the largest share of United States freight and logistics market activity. FHWA recorded 3,760.53 National Highway Freight Network miles in California, 3,801.71 in Texas, and 2,771.82 in Illinois, one Great Lakes state example. The snapshot combines 2024 road-network data with state-reported freight connector mileage as of August 1, 2025. Port Houston's public terminals handled 40,176,436 short tons of containerized cargo in Texas in 2025. These road and terminal assets place substantial freight infrastructure within the leading geography, giving service providers physical points for connecting gateway cargo with inland routes.
Coastal logistics opportunities differ between California's container gateways and Texas's Gulf export channels, where service requirements follow the cargo flow around a specific port. The Port of Los Angeles in California handled 10.24 million twenty-foot equivalent units (TEUs) in calendar 2025. Houston Ship Channel Region exports totaled 19.84 million short tons in April 2026, up 28% from April 2025, according to U.S. Census Bureau data. For providers, the Gulf export increase points to a localized capacity-matching opportunity in coordinating loads toward waterborne departure, alongside the substantial container-handling base supporting port-linked transport services in California.
Inland highway access can constrain otherwise valuable regional freight positions, especially at the individual interchange level. ATRI ranked Chicago's I-294 at I-290/I-88 interchange the top U.S. truck bottleneck for 2025 in its 2026 report. Atlanta's I-285 at I-85 North interchange ranked third in the same 2025 assessment, providing a Southeast example. These rankings focus the commercial decision on access through particular nodes and the transport commitments that depend on them. Providers routing loads through these interchanges need usable road access to support additional service commitments, making nearby freight facilities alone an incomplete basis for regional expansion.
Regulatory Framework and Outlook
The comparison covers selected jurisdictions from the perspective of private property-carrying motor carriers. Federal hours-of-service limits affect the working window for covered drivers, while Texas registration rules apply to qualifying intrastate carriers. These obligations enter the service model at different points, affecting the capacity a carrier can schedule and its authority to conduct covered operations.
Regulatory Table of United States Freight And Logistics Market
| Decision factor | United States | Texas |
|---|---|---|
| Primary authority | Federal Motor Carrier Safety Administration | Texas Department of Motor Vehicles |
| Key instruments or direction | 49 CFR Part 395, including exceptions | 43 TAC Chapter 218 registration; sole-proprietor SSN clarification effective October 29, 2026 |
| Commercial effect | Generally 11 driving hours within a 14-hour window after 10 consecutive off-duty hours, subject to exceptions | Registration triggers include gross or registered weight or gross-weight rating above 26,000 pounds |
| Current policy attractiveness | Medium | Medium |
| Future direction of policy attractiveness | No change | Easing |
| Source: Mordor Intelligence | ||
The federal Medium rating reflects the scheduling requirements that carriers must build into covered property-carrying services. FMCSA's October 2026 proposal would study conditional pauses at cargo pickup or delivery locations without changing the generally applicable limits, supporting No change. Texas's Medium rating reflects registration duties, while the SSN amendment scheduled to take effect October 29, 2026, codifies existing practice for sole-proprietor applicants. Texas's Easing direction reflects the August 2026 proposal for discretionary self-insurance approval without a Texas Department of Public Safety or FMCSA safety rating, retaining satisfactory-rating requirements for already-rated carriers.
Value Chain Stages
The value-chain comparison follows freight arrangement, physical transport, and warehouse fulfillment, showing where providers capture billed service revenue. J.B. Hunt's Integrated Capacity Solutions combines non-asset and asset-light solutions with third-party carriers and company-owned equipment. Dedicated Contract Services uses employee drivers and company-owned or customer-owned equipment in customer-specific operations, usually under longer-term written agreements. That distinction separates earnings for arranging a movement from earnings for executing it, even when both sit within the same logistics group.
Value Chain Analysis Table of United States Freight And Logistics Market
| Primary activity | Key participants | Value capture | Bottleneck | Resilience response |
|---|---|---|---|---|
| Freight arrangement | Transportation arrangers such as J.B. Hunt's Integrated Capacity Solutions | Revenue from arranging transportation | Capacity, pricing, and service-level volatility | Maintain alternative carriers and align quote validity with capacity exposure |
| Freight transportation | Dedicated carriers such as J.B. Hunt's Dedicated Contract Services | Contracted freight-movement service revenue | Customer-specific driver and equipment commitments limit redeployment | Confirm service commitments before assigning additional dedicated capacity |
| Warehousing and fulfillment | Contract-logistics providers such as GXO Logistics, Inc. and Ryder System, Inc. | Integrated warehouse and fulfillment service revenue | Bundled services create coordination requirements across operating tasks | Assign clear responsibility and service measures across the bundled operation |
| Source: Mordor Intelligence | ||||
J.B. Hunt described capacity, pricing, and service-level volatility as a risk for its 2025 brokerage and transactional truckload operations. GXO's warehouse and fulfillment contracts generally bundle services, giving the provider revenue from an integrated operation. Coordination across stages can therefore support value capture when the provider accepts clear responsibility for execution and the associated risks. Further integration can shift commercial leverage toward managed service packages while preserving the distinct earnings logic of arrangement, movement, and fulfillment.
Competitive Landscape
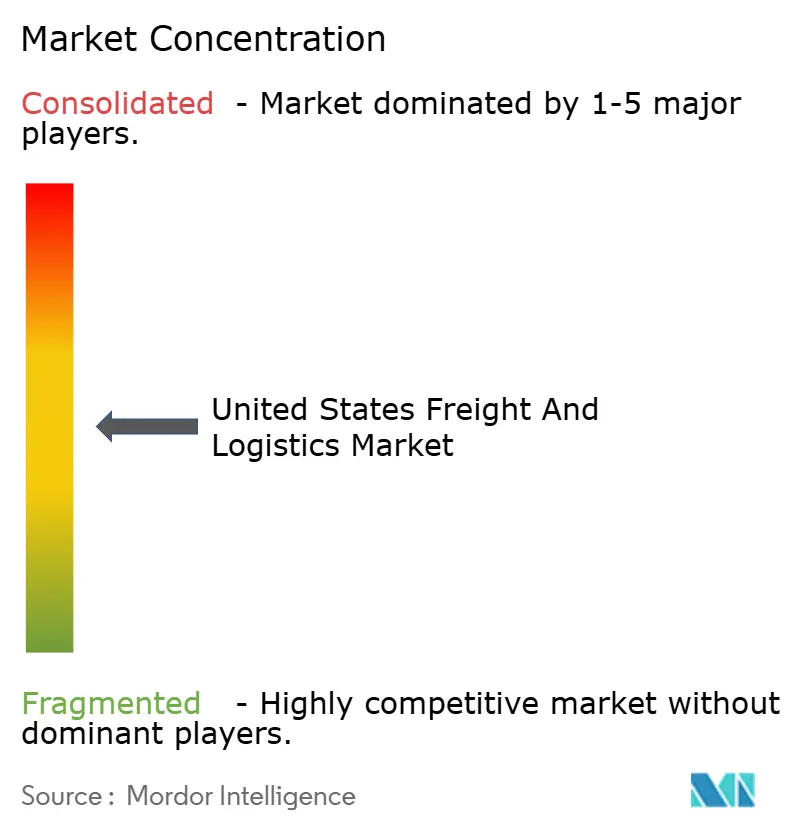
Competition combines a broad provider base with large networks and specialized service portfolios across parcel, surface freight, and forwarding. United Parcel Service of America, Inc. (UPS) provides integrated logistics solutions, while FedEx serves express and small-package customers through Federal Express. Other major participants include Amazon Logistics, C.H. Robinson in surface transport and forwarding, and J.B. Hunt Transport, Inc., a wholly owned J.B. Hunt Transport Services, Inc. subsidiary offering intermodal and dedicated services. On May 4, 2026, Amazon launched Amazon Supply Chain Services, offering freight, distribution, fulfillment, and parcel shipping to businesses of all types and sizes. That service breadth allows an integrated provider to contest multiple parts of a shipper's logistics operation, increasing the importance of coordination between freight movement and fulfillment execution.
FedEx's restructuring changes how shippers identify the counterparty behind LTL service within a previously combined corporate portfolio. On June 1, 2026, FedEx completed the spin-off of FedEx Freight, establishing an independent, publicly traded North American LTL carrier while retaining 19.9% of its shares. After the separation, FedEx's retained portfolio covered express and small-package delivery through Federal Express and supply-chain and specialty transportation services through FedEx Logistics. The separation makes corporate affiliation an insufficient guide to provider coverage, so a shipper combining parcel and LTL services must distinguish the independent freight carrier from FedEx's retained operating businesses.
Growth within a particular freight channel can sustain competitive momentum alongside the restructuring of broader logistics portfolios. J.B. Hunt's intermodal volume increased 8% year over year in Q3 2026. Its Eastern network loads increased 18%, compared with 1% in the transcontinental network, relative to Q3 2025. FedEx Logistics' global customs brokerage and forwarding services also place border-facing capability within the competitive offering. Challengers have room to contest specific lanes and trade-handling needs, where operating reach and the ability to handle border formalities can matter more than breadth across other logistics functions.
United States Freight And Logistics Industry Leaders
-
United Parcel Service of America, Inc. (UPS)
-
FedEx
-
Amazon Logistics
-
C.H. Robinson
-
J.B. Hunt Transport, Inc.
- *Disclaimer: Major Players sorted in no particular order
United States Freight And Logistics Market Companies Covered in this Report
- Amazon Logistics
- C.H. Robinson
- DHL Group
- DSV A/S (Including DB Schenker)
- Expeditors International of Washington, Inc.
- FedEx
- GXO Logistics, Inc.
- J.B. Hunt Transport, Inc.
- Kuehne+Nagel
- Landstar System, Inc.
- Lineage, Inc.
- A.P. Moller - Maersk
- NFI Industries
- Old Dominion Freight Line
- Penske Logistics
- Ryder System, Inc.
- Schneider National, Inc.
- SEKO Logistics
- United Parcel Service of America, Inc. (UPS)
- XPO, Inc.
Recent Industry Developments in United States Freight And Logistics Market
- Oct 2026: USDOT awarded USD 426.7 million in FY 2026 INFRA Track 1 grants to 12 highway projects in 12 states on October 1, providing funding for corridor improvements.
- Sep 2026: CJ Logistics began full-scale operations at the Elwood Logistics Center near Chicago in Elwood, Illinois, following development in partnership with the Korea Ocean Business Corporation.
- Jul 2026: DAT Freight & Analytics and Tai Software announced an available integration on July 23 that gave freight brokers using Tai TMS access to Convoy Platform automated matching and qualified truckload carriers.
Scope and Methodology
By End User Industry
| Agriculture, Fishing, and Forestry |
| Construction |
| Manufacturing |
| Oil and Gas, Mining and Quarrying |
| Wholesale and Retail Trade |
| Others |
By Logistics Function
| Courier, Express, and Parcel (CEP) | By Destination Type | Domestic |
| International | ||
| Freight Forwarding | By Mode of Transport | Air |
| Sea and Inland Waterways | ||
| Others | ||
| Freight Transport | By Mode of Transport | Air |
| Pipelines | ||
| Rail | ||
| Road | ||
| Sea and Inland Waterways | ||
| Warehousing and Storage | By Temperature Control | Non-Temperature Controlled |
| Temperature Controlled | ||
| Other Services | ||
| By End User Industry | Agriculture, Fishing, and Forestry | ||
| Construction | |||
| Manufacturing | |||
| Oil and Gas, Mining and Quarrying | |||
| Wholesale and Retail Trade | |||
| Others | |||
| By Logistics Function | Courier, Express, and Parcel (CEP) | By Destination Type | Domestic |
| International | |||
| Freight Forwarding | By Mode of Transport | Air | |
| Sea and Inland Waterways | |||
| Others | |||
| Freight Transport | By Mode of Transport | Air | |
| Pipelines | |||
| Rail | |||
| Road | |||
| Sea and Inland Waterways | |||
| Warehousing and Storage | By Temperature Control | Non-Temperature Controlled | |
| Temperature Controlled | |||
| Other Services | |||
Market Definition
- Agriculture, Fishing, and Forestry (AFF) - This end user industry segment captures the external (outsourced) logistics expenditure incurred by the AFF industry players. The end user players considered are the establishments primarily engaged in growing crops, raising animals, harvesting timber, harvesting fish & other animals from their natural habitats and providing related support activities. Herein, Logistics Service Providers (LSPs) play a crucial role in acquisition, storage, handling, transportation, and distribution activities for the optimal & continuous flow of inputs (seeds, pesticides, fertilizers, equipment, and water) from manufacturers or suppliers to the producers and smooth flow of output (produce, agro-goods) to distributors/ consumers. This includes both termperature controlled and non-temperature controlled logistics, as and when required according to the shelf life of goods being transported or stored.
- Construction - This end user industry segment captures the external (outsourced) logistics expenditure incurred by the construction industry players. The end user players considered are the establishments primarily engaged in constructing, repairing and renovating residential & commercial buildings, infrastructure, engineering works, subdividing and developing land. Logistics Service Providers (LSPs) play a crucial role in increasing profitability of construction projects by maintaing the inventory of raw materials & equipment, time-critical supplies and by providing other value added services for effective project management.
- Courier, Express, and Parcel - The Courier, Express, and Parcel services, often called as CEP Market, refers to the logistics and postal service providers which specialize in moving small goods (parcels/packages). It captures the overall market size (USD) and market volume (number of parcels) of (1) the shipments/parcels/packages which are under 70kgs/ 154lbs weight, (2) Business Customer packages viz. Business-to-Business (B2B) & Business-to-Consumer (B2C) as well as private customer packages (C2C), (3) non-express parcel delivery services (Standard and Deferred) as well as express parcel delivery services (Day-Definite-Express and Time-Definite-Express), (4) domestic as well as international parcels.
- Demographics - To analyse total addressable market demand, population growth & forecasts have been studied and presented in this industry trend. It represents population distribution across categories like gender (male/female), development area (urban/rural), major cities among other key parameters like population density and final consumption expenditure (growth and share % of GDP). This data has been used for assessing the fluctations in demand & consumption expenditure, and the major hotspots (cities) of potential demand.
- Export Trends and Import Trends - Overall logistics performance of an economy is positively and significantly (statistically) correlated to its trade performance (exports and imports). Hence, in this industry trend, total value of trade, major commodities/ commodity groups and the major trade partners, for the studied geography (country or region as per the scope of report) have been analysed alongside the impact of major trade/logistics infrastructure investments & regulatory environment.
- Freight Forwarding - Freight forwarding which herein refers to the freight transportation arrangement (FTA) industry includes establishments primarily engaged in arranging & tracking transportation of freight between shippers and carriers. Logistics Service Providers (LSPs) considered are freight forwarders, NVOCCs, custom brokers and marine shipping agents. Others segment under Freight Forwarding captures the revenue earned through value added services of FTA like custom brokerage/clearance activities, preparation of freight related documentation, consolidation-deconsolidation of goods, cargo insurance & compliance, arrangement of warehousing & storage, liasing with shippers, and freight forwarding through other modes of transport viz. road and rail.
- Freight Pricing Trends - Freight pricing by mode of transport (USD/tonkm), over the review period, has been presented in this industry trend. The data has been used in assessing the inflationary environment, impact on trade, freight turnover (tonkm), freight and logistics market demand by mode of transport segments and hence the overall freight and logistics market size.
- Freight Tonnage Trends - Freight tonnage (weight of goods in tons) handled by mode of transport, over the review period, has been presented in this industry trend. The data has been used as one of the parameters apart from average distance per shipment (km), freight volume (tonkm), and freight pricing (USD/tonkm) to assess the freight transport market size.
- Freight Transport - Freight Transport refers to the hiring of a logistics service provider (outsourced logistics) for the transport of commodities (raw materials/final/intermediate/finished goods including both solids and fluids) from the origin to a destination within the country (domestic) or cross-border (international).
- Freight and Logistics - External expenditure on (or outsourced) facilitation of freight transport (freight transportation), arrangement of freight transport through an agent (freight forwarding), warehousing and storage (temperature controlled or non-temperature controlled), CEP (domestic or international courier, express and parcel) and other value-added logistics services involved in the transportation of commodities (raw materials or finished goods including both solids and fluids) from the origin to a destination within the country (domestic) or cross-border (international), through one or more modes of transportation viz. road, rail, sea, air and pipelines constitute freight and logistics market.
- Fuel Price - Fuel price spikes can cause delays and diruption for logistics service providers (LSPs), while drops in the same can result in higher short-term profitability and increased market rivalry to offer consumers with the best deals. Hence, the fuel price variations have been studied over the review period and presented along with the causes as well as market impacts.
- GDP Distribution by Economic Activity - Nominal Gross Domestic Product and distribution of the same, across major economic sectors in the geography studied (country or region as per scope of the report) have been studied and presented in this industry trend. As GDP is positively related to the profitability and growth of logistics industry, this data has been used in adjunction to the input-output tables/ supply-use tables for analyzing the potential major contributing sectors towards the logistics demand.
- GDP Growth by Economic Activity - Growth of Nominal Gross Domestic Product across major economic sectors, for the geography studied (country or region as per scope of the report) have been presented in this industry trend. This data has been utilized for assessing the growth of logistics demand from all the market end users (economic sectors considered here).
- Inflation - Variations in both Wholesale Price Inflation (YoY change in producer price index) and Consumer Price Inflation have been presented in this industry trend. This data has been used to assess the inflationary environment as it plays a vital role in smooth functioning of the supply chain, directly impacting the logistics operational cost components e.g., pricing of tyres, driver wages & benefits, energy/fuel prices, maintenace costs, toll charges, warehousing rents, custom brokerage, forwarding rates, courier rates etc. hence impacting the overall freight and logistics market.
- Infrastructure - As infrastructure plays a vital role in an economy's logistics performance, variables like length of roads, distribution of road length by surface category (paved v/s unpaved), distribution of road length by road classification (expressways v/s highways v/s other roads), rail length, volume of containers handled by major ports and tonnage handled by major airports have been analysed and presented in this industry trend.
- Key Industry Trends - The report section named "Key Industry Trends" include all the key variables/parameters studied to better analyze the market size estimates and forecasts. All the trends have been presented in the form of data points (time series or latest available data points) along with analysis of the paramter in the form of concise market relevant commentary, for the geography studied (country or region as per the scope of report).
- Key Strategic Moves - The action taken by a company to differentiate from its competitor or used as a general strategy is referred to as a key strategic move (KSM). This includes (1) Agreements (2) Expansions (3) Financial Restructuring (4) Mergers and Acquisitions (5) Partnerships, and (6) Product Innovations. Key players (Logistics Service Providers, LSPs) in the market have been shortlisted, their KSM have been studied and presented in this section.
- Liner Shipping Bilateral Connectivity Index - It indicates a country pair's integration level into global liner shipping networks and plays a crucial role in determining bilateral trade, which in turn potentially contributes toward the prosperity of a country and its surrounding region. Hence the major economies connected to the country/ region as per scope of the report, have been analyzed and presented in "Liner Shipping Connectivity" industry trend.
- Liner Shipping Connectivity - This industry trend analyses the state of connectivity to the global shipping networks based on the status of maritime transport sector. It includes the analysis of liner shipping connectivity, bilateral shipping connectivity, and port liner shipping connectivity indices for the geography (country/ region as per scope of the report) over the review period.
- Liner Shipping Connectivity Index - It indicates how well countries are connected to global shipping networks based on the status of their maritime transport sector. It is based on five components of the maritime transport sector: (1) The number of shipping lines servicing a country, (2) The size of the largest vessel used on these services (in TEUs), (3) The number of services connecting a country to the other countries, (4) The total number of vessels deployed in a country, (5) The total capacity of those vessels (in TEUs).
- Logistics Performance - Logistics Performance and Logistics Costs are the backbone of trade, and influences trade costs, making countries compete globally. Logistics performance is influenced by market wide adopted supply chain management strategies, government services, investments & policies, fuel/ energy costs, inflationary environment etc. Hence, in this industry trend, the logistics performance of the geography studied (country/ region as per the scope of report) has been analysed and presented over the review period.
- Major Truck Suppliers - Market share of truck brands is influenced by factors like geographical preferences, portfolio of truck types, truck prices, local production, truck repair & maintenance service peneteration, customer support, technological innovations (like electric vehicles, digitalization, autonomous trucks), fuel efficiency, financing options, annual maintenance costs, availability of substitutes, marketing startegies etc. Hence, the distribution (share % for base year of the study) of truck sales volume for leading truck brands and commentary on current market scenario & market anticipation over the forecast period have been presented in this industry trend.
- Manufacturing - This end user industry segment captures the external (outsourced) logistics expenditure incurred by the Manufacturing industry players. The end user players considered are the establishments primarily engaged in the chemical, mechanical or physical transformation of materials or substances into new products. Logistics Service Providers (LSPs) play a crucial role in maintaining a smooth flow of raw materials across the supply chain, enabling timely delivery of finished goods to distributors or end customers and storing & supplying the raw materials to clients for just-in-time manufacturing.
- Maritime Fleet Load Carrying Capacity - Maritime fleet load carrying capacity depicts the development state of an economy's maritime infrastructure & trade. It is influenced by factors like volume of production, international trade, major end user industries, maritime connectivity, environmental regulations, investments in port infrastructure development, port container cargo handling capacity etc. This industry trend represents the maritime fleet load carrying capacity by type of ship viz. container ships, oil tankers, bulk carriers, general cargo, among other types alongwith the influencing factors for the geography studied (country/ region as per scope of the report), over the review period.
- Modal Share - Freight Modal Share is influenced by factors like modal productivity, government regulations, containerization, distance of shipment, temperature control requirements, type of goods, international trade, terrain, speed of delivery, shipment weight, bulk shipments, etc. Also, modal share by tonnage (tons) and modal share by freight turnover (ton-km) differ as per average distance of shipments, weight of major commodity groups transported in the economy and number of trips. This industry trend represents the distribution of freight transported by mode of transport (tons as well as ton-km), for the study base year.
- Oil and Gas, Mining and Quarrying - This end user industry segment captures the external (outsourced) logistics expenditure incurred by the extraction industry players. The end user players considered are the establishments that extract naturally occurring mineral solids, such as coal and ores; liquid minerals, such as crude petroleum; and gases, such as natural gas. Logistics Service Providers (LSPs) covers entire phases from upstream to downstream and plays a crucial role in the transportation of machinery, drilling equipments, extracted minerals, crude oil & natural gas and refined/ processed products from one place to another.
- Other End Users - Other end user segment captures the external (outsourced) logistics expenditure incurred by the financial services (BFSI), real estate, educational services, healthcare, and professional services (administrative, waste management, legal, architectural, engineering, design, consulting, scientific R&D). Logistics Service Providers (LSPs) plays a crucial role in the reliable movement of supplies and documents to/from these industries such as transporting any equipment or resources required, shipping confidential documents and files, movement of medical goods & supplies (surgical supplies and instruments, including gloves, masks, syringes, equipment) to name a few.
- Other Services - Other Services segment captures revenue earned through (1) Value added services (VAS) for freight transportation by road, rail, air and sea & inland waterways, (2) VAS for marine cargo transportation (operation of terminal facilities such as harbours and piers, operation of waterway locks, navigation, pilotage and berthing activities, lighterage, salvage activities, lighthouse activities, among other miscellaneous support activities), (3) VAS for land freight transportation (operation of terminal facilities such as railway stations, stations for the handling of goods, operation of railroad infrastructure, switching and shunting, towing and road side assistance, liquefaction of gas for transportation purposes, among other miscellaneous support activities), (4) VAS for air cargo transportation (operation of terminal facilities such as airway terminals, airport and air-traffic-control activities, ground service activities on airfields, runway maintenance, inspection/ ferrying/ maintenance/ testing of aircrafts, aircraft fuelling services, among other miscellaneous support activities), (5) VAS for warehousing and storage service (operation of grain silos, general merchandise warehouses, refrigerated warehouses, storage tanks etc., storage of goods in foreign trade zones, blast freezing, crating goods for shipping, packing and preparing goods for shipping, labelling and/or imprinting the package, kit assembling and packaging services, among other miscellaneous support activities), and (6) VAS for courier, express and parcel service (pickup, sorting).
- Port Calls and Performance - The performance of ports is key to an economy's freight movement, trade, global connectivity, successful growth strategies, investment attractiveness for production & distribution systems, and thus affects GDP, employment, per capita income and industrial growth. Hence, the port perfomance parameters like median time spent by vessels in the ports; average age, size, cargo carrying capacity, container carrying capacity, of vessels entering the ports, port calls, and container port throughput have been analysed and presented in this industry trend.
- Port Liner Shipping Connectivity Index - It reflects a port's position in the global liner shipping network, wherein a higher value of index is associated with better connectivity. Efficient and well-connected ports (1) contribute towards minimizing transport costs, linking supply chains and supporting international trade, (2) pave the way for economies of scale and development of expertise by permitting producers to better exploit possibilities in domestic as well as foreign markets. Hence the major ports of strategic importance, in the country/ region as per scope of the report, have been analyzed and presented in "Liner Shipping Connectivity" industry trend.
- Port Throughput - It reflects the amount of cargo or number of vessels a port handles annually. It can be related to (1) cargo tonnage, (2) container TEU, and (3) vessel calls. Port throughput in terms of total containers handled (TEU's), has been presented in the "Port Calls and Performance" industry trend.
- Producer Price Inflation - It indicates inflation from viewpoint of the producers viz. the average selling price received for their output over a period of time. Annual change (YoY) of producer price index is reported as wholesale price inflation in the "Inflation" industry trend. As WPI captures dynamic price movements in most comprehensive way, it is widely used by governments, banks, industry, business circles and is deemed important in formulation of trade, fiscal and other economic policies. The data has been used in adjunction to consumer price inflation for better understanding the inflationary environment.
- Segmental Revenue - Segmental Revenue has been triangulated or computed and presented for all the major players in the market. It refers to the freight and logistics market specific revenue earned by the company, over the base year of study, in the geography studied (country or region as per the scope of report). It is computed through the study and analysis of major parameters like financials, service portfolio, employee strength, fleet size, investments, number of countries present in, major economies of concern, etc. that have been reported by the company in its annual reports, webpage. For companies having scarce financial disclosures, paid databases like D&B Hoovers, Dow Jones Factiva have been resorted to and verified through industry/expert interactions.
- Transport and Storage Sector GDP - Value and growth of Transport and Storage Sector GDP has a direct relation to the freight and logistics market size. Hence, this variable has been studied and presented over the review period, in value terms (USD) and as share % of total GDP, in this industry trend. The data has been supported by concise and relevant commentary around the investments, developments, and current market scenario.
- Trends in E-Commerce Industry - Enhanced internet connectivity and boom in smartphone penetration, coupled with increasing disposable incomes, has led to a phenomenal growth in the e-commerce market globally. Online shoppers require fast and efficient delivery of their orders leading to an increase in the demand for logistics services especially e-commerce fulfilment services. Hence, the Gross Merchandise Value (GMV), historial and projected growth, breakup of major commodity groups in e-commerce industry for the studied geography (country or region as per scope of the report) have been analysed and presented in this industry trend.
- Trends in Manufacturing Industry - Manufacturing industry involves the transformation of raw materials into finished products, while logistics industry ensures the efficient flow of raw materials to the factory, and the transport of manufactured products to the distributors & consumers. Demand-Supply of both industries are highly cross-linked and critical for a seamless supply chain. Hence, the Gross Value Added (GVA), breakup of GVA into major manufacturing sectors, and growth of manufacturing industry over the review period have been analysed and presented, in this industry trend.
- Trucking Fleet Size By Type - Market share of truck types is influenced by factors like geographical preferences, major end user industries, truck prices, local production, truck repair & maintenance service peneteration, customer support, technological disruptions (like electric vehicles, digitalization, autonomous trucks) etc. Hence, the distribution (share % for base year of study) of truck parc volume by type of truck, market disruptors, truck manufacturing investments, truck specifications, truck use & import regulations, and market anticipation over the forecast period have been presented in this industry trend.
- Trucking Operational Costs - The prime reasons for measuring/ benchmarking logistics performance of any trucking company are to reduce operational costs and increase profitability. On the other hand, measuring operational costs helps to identify whether and where to make operational changes to control expenses and identify areas for improved performance. Hence, in this industry trend, trucking operational costs and the variables involved viz. driver wages & benefits, fuel prices, repairs & maintenance costs, tyre costs etc. have been studied over the base year of study, and presented for the geography studied (country or region as per the scope of report).
- Warehousing and Storage - Warehousing and storage segment captures revenue earned through the operation of general merchandise, refrigerated and other types of warehousing & storage facilities. These establishments take responsibility for storing the goods and keeping them secure in lieu of charges. Value added services (VAS) they may provide are considered to be a part of the "other services" segment. Here VAS refer to a range of services, related to the distribution of a customer's goods and can include labelling, breaking bulk, inventory control & management, light assembly, order entry & fulfillment, packaging, pick & pack, price marking & ticketing and transportation arrangement.
- Wholesale and Retail Trade - This end user industry segment captures the external (outsourced) logistics expenditure incurred by the wholesalers and retailers. The end user players considered are the establishments primarily engaged in wholesaling or retailing merchandise, generally without transformation, and rendering services incidental to the sale of merchandise. Logistics Service Providers (LSPs) plays a crucial role in the reliable movement of supplies to and finished products from production houses to the distributors and finally to the end customer covering activites like material sourcing, transportation, order fulfillment, warehousing & storage, demand forecasting, inventory management etc.
| Keyword | Definition |
|---|---|
| Axle Load | The axle load of a wheeled vehicle is the total weight bearing on the roadway for all wheels connected to a given axle. |
| Back Haul | Backhaul is the return movement of a transport vehicle from its original destination to its original point of departure. |
| Bill of Lading | A bill of lading is a legal document issued by a carrier to a shipper that details the type, quantity, and destination of the goods being carried. |
| Bunkering | Bunkering is the process of supplying fuel and/or gasoil to be used to power the propulsion system of a ship (such fuel is referred to as bunker). It includes the logistics of loading and distributing the fuel among available shipboard tanks. A person dealing in trade of bunker (fuel) is called a bunker trader. |
| Bunkering Service | Bunkering service is the supply of a requested quality and quantity of bunkers to a ship. |
| C-commerce | C-commerce (Collaborative commerce) describes electronically enabled business interactions among an enterprise’s internal personnel, business partners and customers throughout a trading community. The trading community could be an industry, industry segment, supply chain or supply chain segment. |
| Cabotage | Transport by a vehicle registered in a country performed on the national territory of another country. |
| Cartage Agent | A ground transportation service that provides pickup and delivery of freight in locations not served directly by an air or ocean carrier. |
| Contract logistics | Contract logistics refers to the outsourcing of resource management tasks by one company to a third-party company specializing in logistical matters, such as transportation, warehousing, and order fulfillment. |
| Courier | A business that is used to send messages, packages, etc. Courier service refers to the fast or quick, door to door pickup and delivery service for goods or documents. It can be local or international. A company that provides such delivery services is called a courier company. A courier company hires people to provide their services. Such a person hired by the courier service company is called a courier. |
| Cross docking | Cross docking is a practice in logistics management that includes unloading incoming delivery vehicles and loading the materials directly into outbound delivery vehicles, omitting traditional warehouse logistical practices and saving time and money. |
| Cross Trade | International transport between two different countries performed by a vehicle registered in a third country. A third country is a country other than the country of loading/embarkation and than the country of unloading/disembarkation. |
| Customs Clearance | The procedures involved in getting cargo released by Customs through designated formalities such as presenting import license/permit, payment of import duties and other required documentations by the nature of the cargo such as FCC or FDA approval. |
| Customs seal | Customs seal means a seal, stamp or any other preventive means affixed by customs officials to ensure the inviolability of goods, commercial means of transport or warehouses. |
| Dangerous Goods | Dangerous goods (or hazardous materials or HAZMAT) include flammable liquids/solids, gases, compressed, liquified, dissolved under pressure, corrosives, oxidising substances, explosive substances and articles, substances, which on contact with water, emit flammable gasses, organic peroxides, toxic substances, infectious substances, radioactive materials, miscellaneous dangerous goods and articles. |
| Direct Shipment | Direct shipment is a method of delivering goods from the supplier or the product owner to the customer directly. In most cases, the customer orders the goods from the product owner. This delivery scheme reduces transportation and storage costs, but requires additional planning and administration. |
| Drayage | A drayage is a form of trucking service that connects the different modes of shipping (intermodal), such as ocean freight or air freight. It’s a short-haul trip that transports goods from one place to another, usually before or after its long-haul shipping process. Drayage trucks move cargo to and from various destinations, such as container ships, storage lots, order fulfillment warehouses, and rail yards. Typically, drayage only transports goods in short distances and operates only in one metropolitan area. It also requires only one trucker in a single shift. |
| Dry Docking | Dry docking is a term used for repairs or when a ship is taken to the service yard. During dry docking, the whole ship is brought to a dry land so that the submerged portions of the hull can be cleaned or inspected. |
| Dry van | A dry van is a type of semi-trailer that's fully enclosed to protect shipments from outside elements. Designed to carry palletized, boxed or loose freight, dry vans aren't temperature-controlled (unlike refrigerated “reefer” units) and can't carry oversized shipments (unlike flatbed trailers). |
| Feedering | Transport service whereby loaded or empty containers in a regional are transferred to a “mother ship” for a long-haul ocean voyage. |
| Final Demand | Final demand includes all types of commodities (goods as well as services) consumed as final use and might include personal consumption, or consumption by government, by businesses as capital investment, and as exports. includes all types of commodities (goods as well as services) consumed as final use and might include personal consumption, or consumption by government, by businesses as capital investment, and as exports. |
| First mile Delivery | First mile delivery refers to the first stage of the transportation. This is when the parcel leaves the seller’s warehouse and is taken by the courier pick up agent to process it or take it to the warehouse. Once the package reaches the post office or the courier’s hub, it is then sorted and transported further until it reaches the customer’s doorstep. |
| Fiscal storage services | It means a facility, clearly separated from other premises, where the excise goods are produced, processed, held, received or dispatched under a duty suspension arrangement by an authorized depositor, in the course of his business, under conditions laid down by the customs authorities. |
| Flat Bed | It has a back body that is flatly shaped for easy loading and unloading of goods. The flatbed truck is mostly used to transport heavy, oversized, wide and indelicate goods. |
| Flatbed Truck | A flatbed truck is a type of truck with rigid design. It has a back body that is flatly shaped for easy loading and unloading of goods. The flatbed truck is mostly used to transport heavy, oversized, wide and indelicate goods such as machinery, building supplies or equipment. Due to the truck open body, the goods transported with it must not be vulnerable to rain. By functionality, the flatbed truck is comparable to a flatbed trailer. |
| Freight Transit Time | Transit time is how long it takes for a shipment to be delivered to its final destination after being picked up from a designated pick up point. |
| Halal Logistics | It refers to the process of managing the logistics operations such as fleet management, storage/warehousing, and materials handling according to the principles of Shariah law in ensuring the integrity of the halal products at the point of consumption. |
| Haulage | The commercial transport of goods. |
| Inbound Logistics | Inbound logistics is the way materials and other goods are brought into a company. This process includes the steps to order, receive, store, transport and manage incoming supplies. Inbound logistics focuses on the supply part of the supply-demand equation. |
| Intermediate Demand | Intermediate demand includes goods, services, and maintenance and repair construction sold to businesses, excluding capital investment. |
| International Loaded | Place of loading of goods in reporting country (i.e., country in which the vehicle performing the transport is registered) and place of unloading in a different country. |
| International Unloaded | Place of unloading of goods in reporting country (i.e., country in which the vehicle performing the transport is registered) and place of loading in a different country. |
| Last Mile Delivery | Last mile delivery refers to the very last step of the delivery process when a parcel is moved from a transportation hub to its final destination—which, usually, is a personal residence or retail store. |
| Less than-Truck-Load (LTL) | Less-than-truckload, also known as less-than-load (LTL), is a shipping service for relatively small loads or quantities of freight. An LTL provider combines the loads and shipping requirements of several different companies on their trucks, using a hub-and-spoke system to get goods to their destinations. |
| Locomotives Haluage | The transport of coal, ore, workers, and materials underground by means of locomotive-hauled mine cars. The locomotive may be powered by battery, diesel, compressed air, trolley, or some combination such as battery-trolley or trolley-cable reel. |
| Milkrun | A Milk Run is a delivery method used to transport mixed loads from various suppliers to one customer. Instead of each supplier sending a truck every week to meet the needs of one customer, one truck (or vehicle) visits the suppliers to pick up the loads for that customer. This method of transport got its name from the dairy industry practice, where one tanker used to collect milk from several dairy farms for delivery to a milk processing company. |
| Multi country consolidation | Multi-Country Consolidation (MCC) is a cost-effective solution that consolidates ones cargo from different countries of origin to build Full Container Loads (FCL). MCC is most suitable for companies that import light volumes of goods from multiple countries but want to take advantage of the more economic FCL freight rates. |
| Multi-Modal Logistics | Multimodal transportation or multimodal shipping refers to logistics and freight processes that require multiple modes of transportation. |
| Omni Channel Logistics | Omnichannel distribution is a multichannel approach taken by companies to give customers a way to purchase and receive orders from several sales channels with one-touch seamless integration. Some of the ways include- 1. Buy online, then pick-up at the brick and mortar store; 2. Buy online, then have it delivered to the home or another location; 3.In store purchase, with the delivery either to the home or another location; 4. Drop ship from a warehouse or manufacturing center to store, home or other location; 5.Buy online, then return at store or online; 6. Buy online, then return online. |
| OOG cargo | Out of Gauge (OOG) cargo is any cargo that can not be loaded into six-sided shipping containers simply because it is too large. The term is a very loose classification of all cargo with dimensions beyond the maximum 40HC container dimensions. That is a length beyond 12.05 meters – a width beyond 2.33 meters – or a height beyond 2.59 meters. |
| Other ships | Other ships include: Liquefied petroleum gas carriers, liquefied natural gas carriers, parcel (chemical) tankers, specialized tankers, reefers, offshore supply vessels, tugboats, dredgers, cruise, ferries, other non-cargo ships |
| Other Specialised Cargo | Other specialised goods include pre-slung goods (Goods, one or more items, supplied with a sling or slings), mobile units (Mobile Self Propelled Units, Non Self Propelled Units, unrolled vehicles), oversized equipment load (light and heavy machinery that is often too big or too heavy), high value freight that needs extra protection like electronics, financial services road freight. |
| Outsourced Freight Transport | Transport for hire or reward; The carriage for remuneration of goods. |
| Pallets | Raised platform, intended to facilitate the lifting and stacking of goods. |
| Part load | A part load describes goods which only fills a truck partially. In essence, the quantity of the shipment is bigger than the Less Than Truckload (LTL) shipment. Also, the shipment cannot fully occupy a truck i.e. its capacity is much lower than a Full Truckload (FTL) shipment. |
| Paved Road | Road surfaced with crushed stone (macadam) with hydrocarbon binder or bituminized agents, with concrete or with cobblestone. |
| Q-commerce | Q-commerce, also referred to as quick commerce, is a type of e-commerce where emphasis is on quick deliveries, typically in less than an hour. |
| Quay | A stone or metal platform lying alongside or projecting into water for loading and unloading ships. |
| Recommerce | Recommerce is the selling of previously owned items through online marketplaces to buyers who reuse, recycle or resell them. |
| ReverseLogistics | Reverse logistics is a type of supply chain management that moves goods from customers back to the sellers or manufacturers. |
| Road Freight Transport Service | Hiring a trucking agency for transport of commodities (raw materials or manufactured goods including both solids and liquids) form the origin to a destination within the country (domestic) or cross-border (international) constitutes road freight transport market. The service might be Full-Truck-Load or Less than-Truck-Load, containerized or non-containerized, temperature controlled or non temperature controlled, short haul or long haul. |
| Roll-on/roll-off cargo | Roll-on/roll-off (RORO or ro-ro) ships are cargo ships designed to carry wheeled cargo, such as cars, motorcycles, trucks, semi-trailer trucks, buses, trailers, and railroad cars, that are driven on and off the ship on their own wheels or using a platform vehicle, such as a self-propelled modular transporter. |
| Swap bodies | A swap body, swop body, exchangeable container or interchangeable unit, is one of the types of standard freight containers for road and rail transport. |
| Tank Barge | A non-self-propelled vessel constructed or adapted primarily to carry liquid, solid or gaseous commodities or cargos in bulk in cargo spaces (or tanks) through rivers and inland waterways, and may occasionally carry commodities or cargos through oceans and seas when in transit from one inland waterway to another. The commodities or cargos transported are in direct contact with the tank interior. |
| Tautliner vehicle | Tautliner and curtainsider are used as generic names for curtain sided trucks/trailers. The curtains are permanently fixed to a runner at the top and detachable rails/poles at front and rear, allowing the curtains to be drawn open and forklifts used all along the sides for easy and efficient loading and unloading. When closed for travel, vertical load restraint straps are attached to a rope rail beneath the truck bed, connecting the truck bed and curtain along both sides. Winches at either end of the curtain tension it, hence the 'Tautliner' name. This stops the curtain from flapping or drumming in the wind and can also help retain light loads from slipping sideways. |
| Transloading | Transloading is a shipping term that refers to the transfer of goods from one mode of transportation to another en route to their ultimate destination. |
| Tsubo | A Japanese unit of area equal to 35.58 square feet. |
| Unpaved Road | Road with a stabilized base not surfaced with crushed stone, hydrocarbon binder or bituminized agents, concrete or cobblestone. |
| Vessel Husbandry Services | It includes ship maintenance, repairs, cleaning, upkeep of the hull and rigging and equipment. |
Research Methodology
Mordor Intelligence follows a four-step methodology in all our reports.
- Step-1: Identify Key Variables: In order to build a robust forecasting methodology, the variables and factors identified in Step-1 are tested against available historical market numbers. Through an iterative process, the variables required for market forecast are set and the model is built on the basis of these variables.
- Step-2: Build a Market Model: Market-size estimations for the forecast years are in nominal terms. Inflation is not a part of the pricing, and the average selling price (ASP) is kept constant throughout the forecast period for each country.
- Step-3: Validate and Finalize: In this important step, all market numbers, variables and analyst calls are validated through an extensive network of primary research experts from the market studied. The respondents are selected across levels and functions to generate a holistic picture of the market studied.
- Step-4: Research Outputs: Syndicated Reports, Custom Consulting Assignments, Databases & Subscription Platforms


