
Thailand Data Center Processor Market Size and Share
Market Overview
| Study Period | 2022 - 2031 |
|---|---|
| Base Year For Estimation | 2025 |
| Forecast Data Period | 2026 - 2031 |
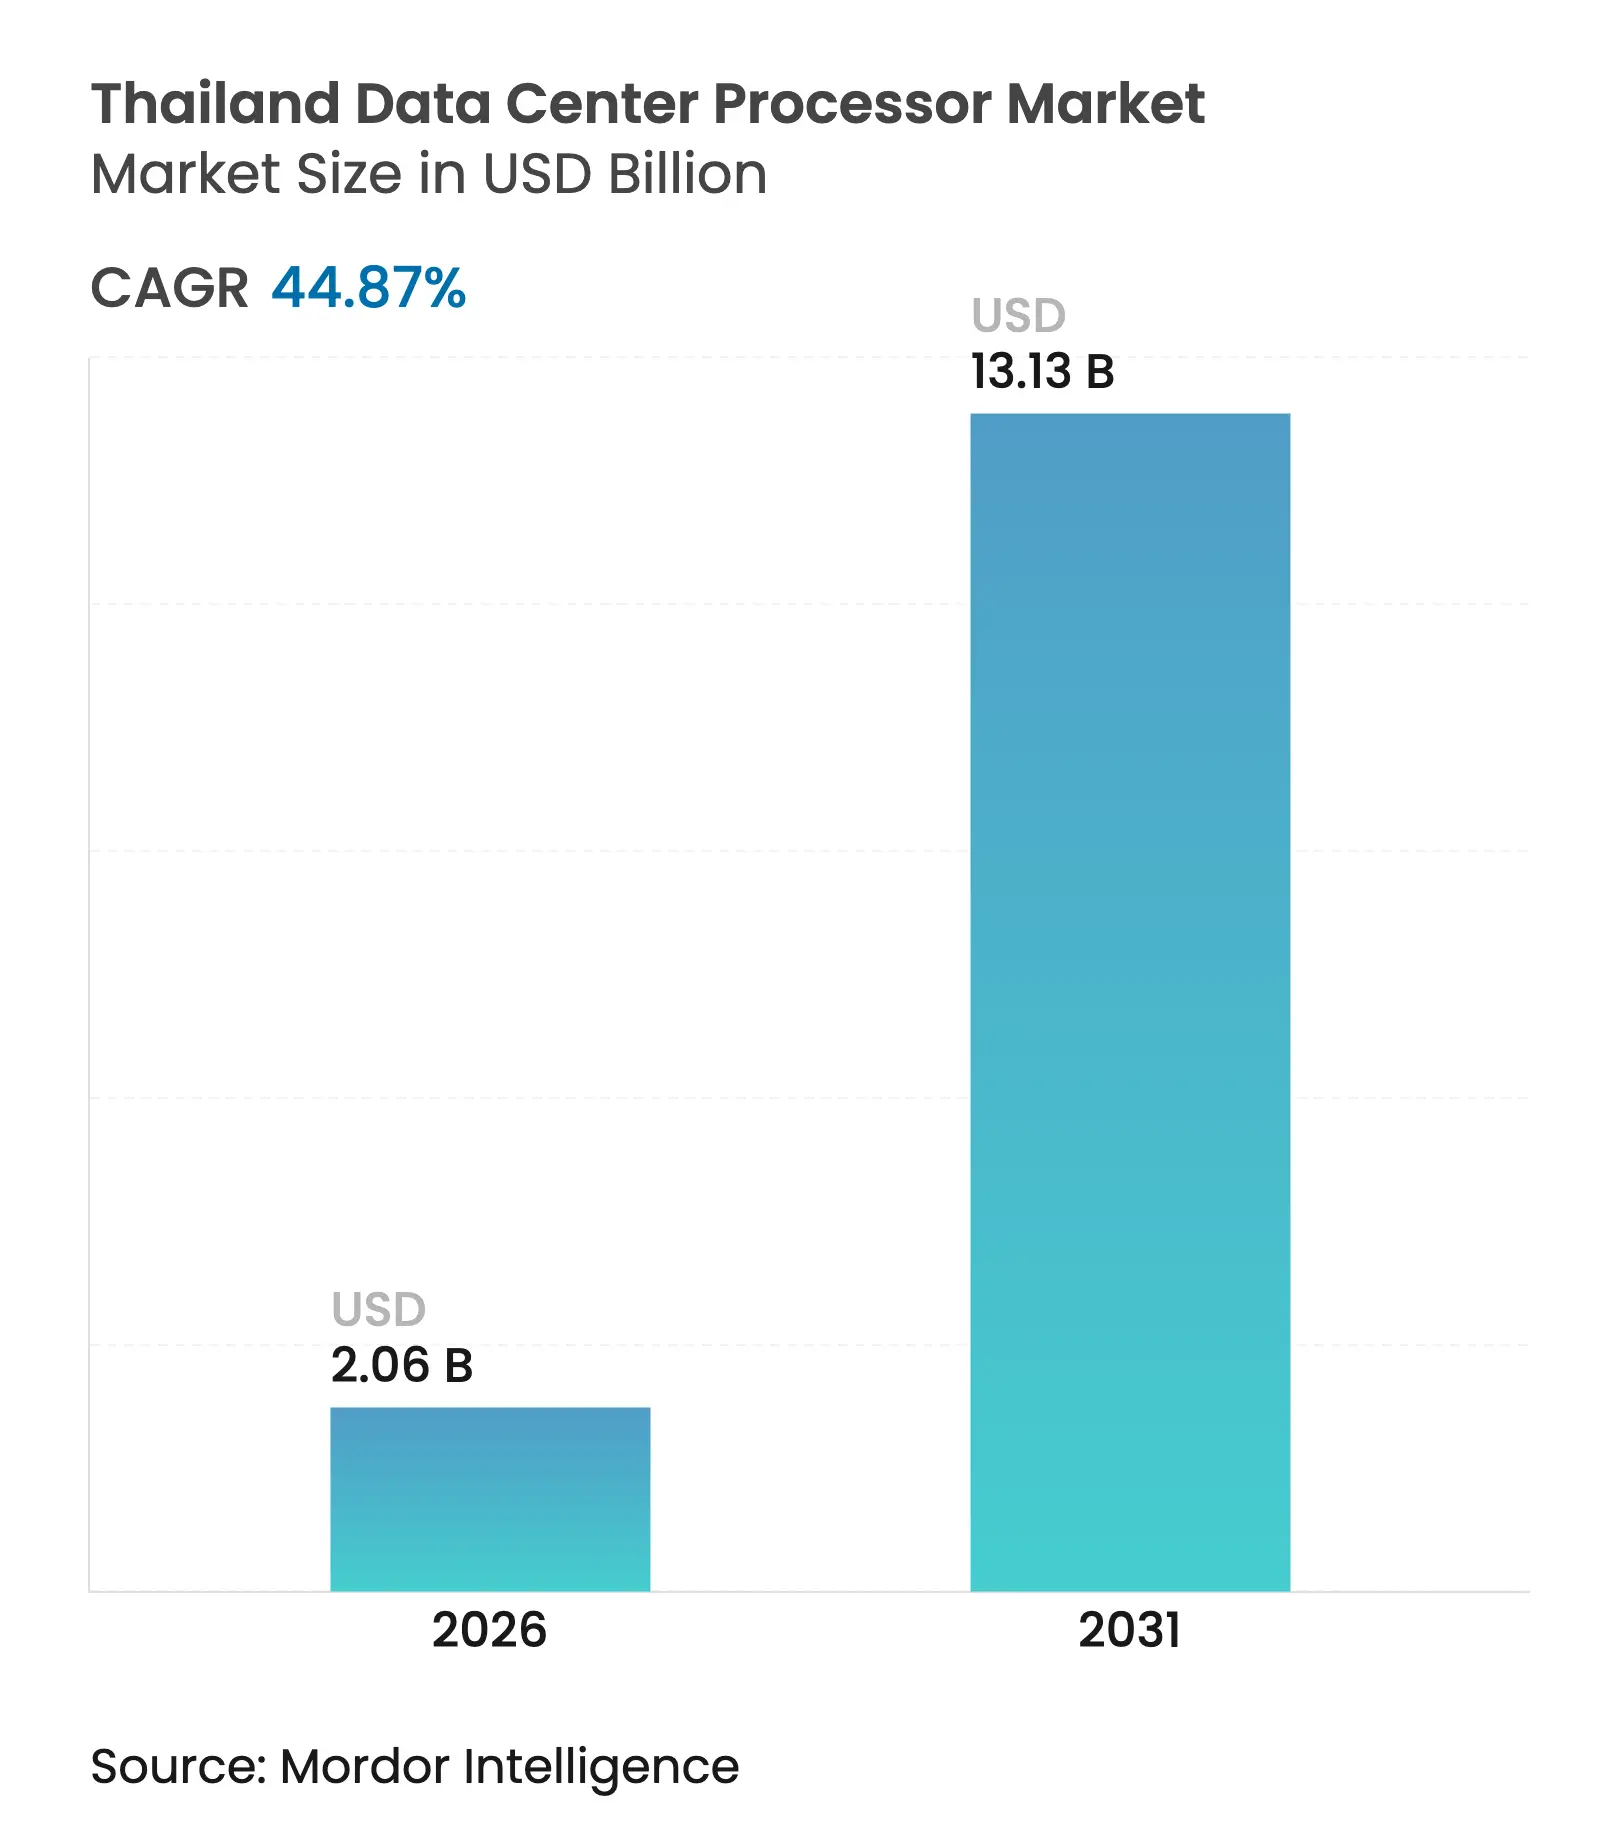
| Market Size (2026) | USD 2.06 Billion |
| Market Size (2031) | USD 13.13 Billion |
| Growth Rate (2026 - 2031) | 44.87 % CAGR |
| Market Concentration | High |
Major Players *Disclaimer: Major Players sorted in no particular order. Image © Mordor Intelligence. Reuse requires attribution under CC BY 4.0. |

Thailand Data Center Processor Market Analysis by Mordor Intelligence
Thailand data center processor market size in 2026 is estimated at USD 2.06 billion, growing from 2025 value of USD 1.42 billion with 2031 projections showing USD 13.13 billion, growing at 44.87% CAGR over 2026-2031. Momentum comes from hyperscale cloud cap-ex, rapid 5G rollout, and the National AI Action Plan. Edge deployments are shifting processor selection toward energy-efficient architectures, while tax incentives in the Eastern Economic Corridor (EEC) shorten upgrade cycles. Competitive pressure among Intel, AMD, NVIDIA, and emerging RISC-V suppliers is stimulating continuous innovation, keeping prices in check despite supply constraints. Demand resilience mirrors global expectations that data-center AI chips will exceed USD 400 billion by 2030
Key Report Takeaways
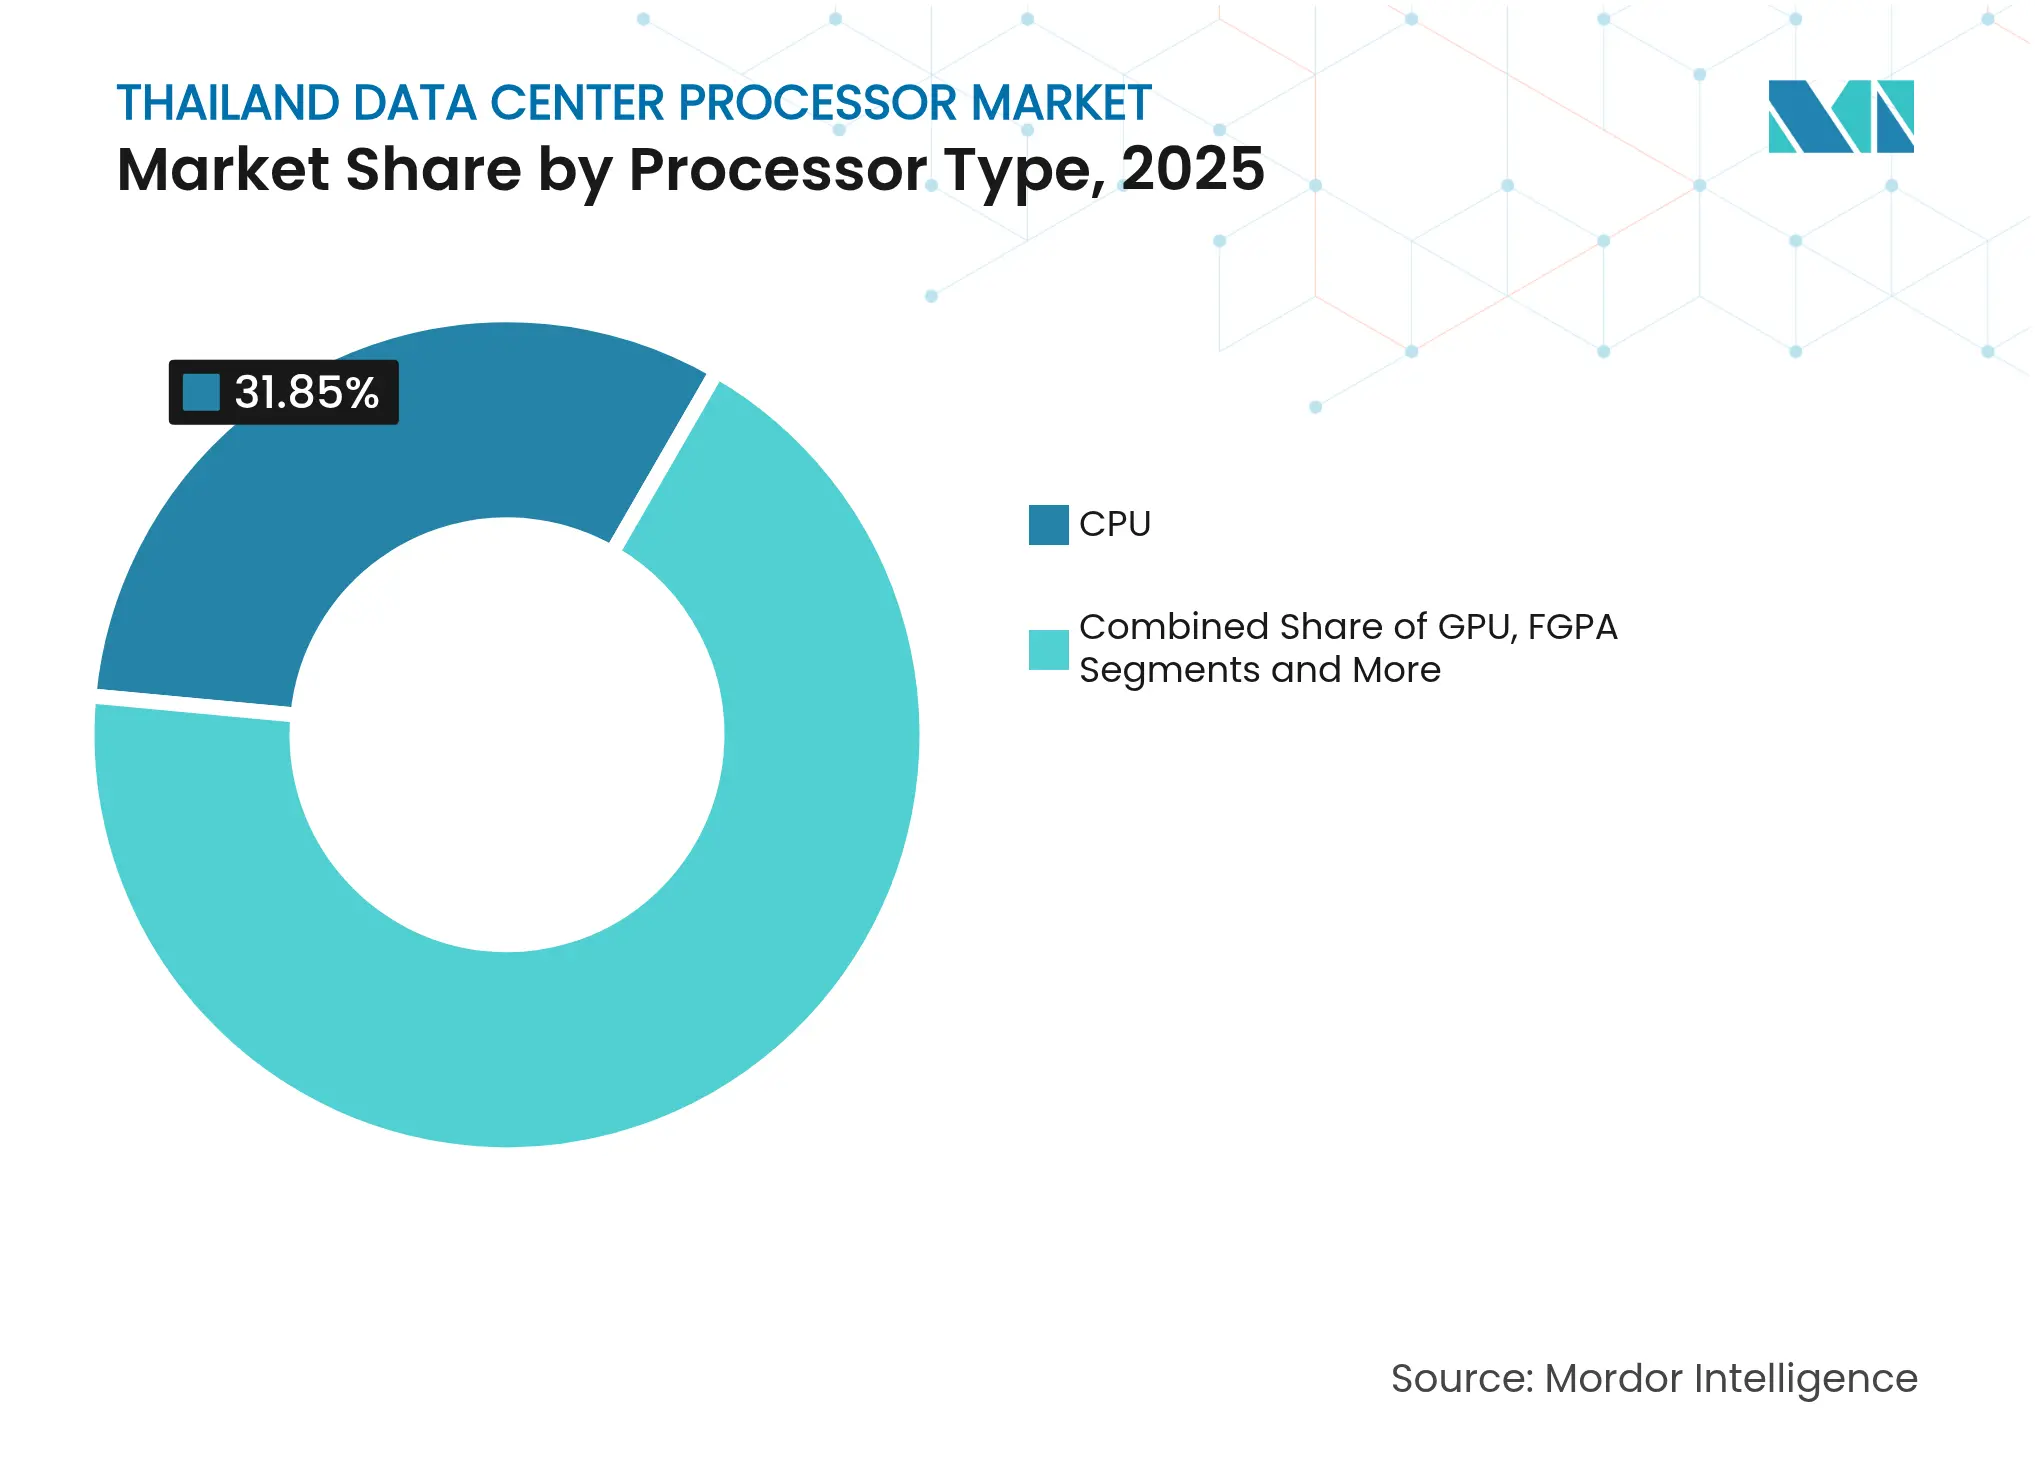
- By processor type, CPU devices led with 31.85% of Thailand data center processor market share in 2025, while AI accelerators are poised for 45.3% CAGR through 2031.
- By application, AI/ML training & inference held a 33.62% slice of the Thailand data center processor market share in 2025; advanced data analytics is projected to expand at a 45.8% CAGR to 2031.
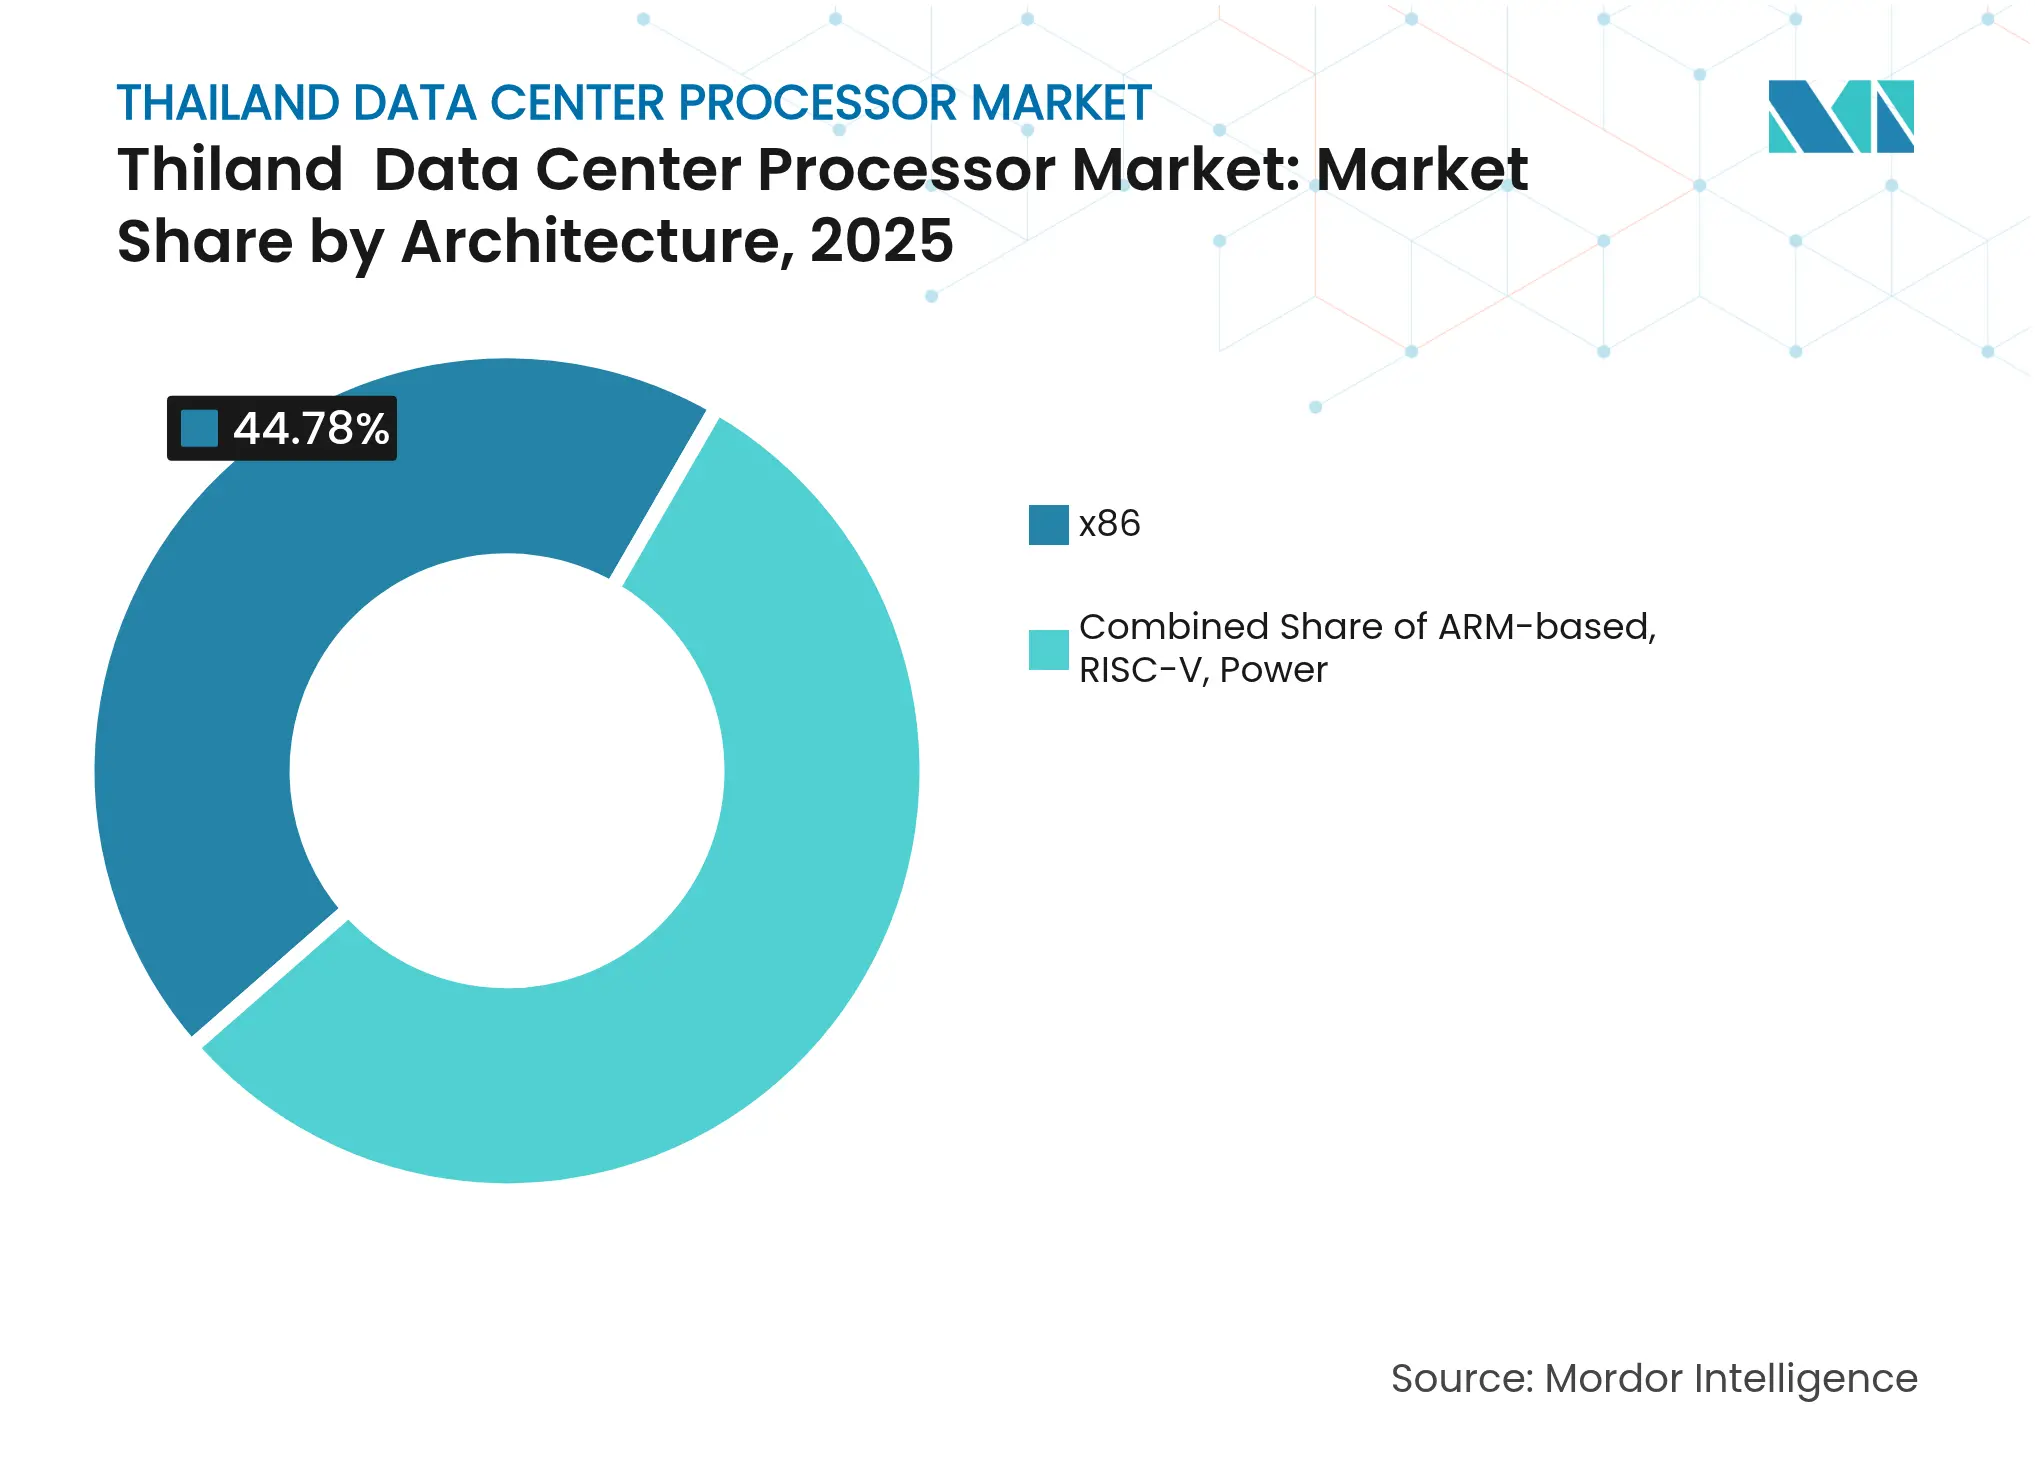
- By architecture, x86 captured 44.78% of the Thailand data center processor market size in 2025; RISC-V is the fastest-growing architecture with a 45.1% CAGR.
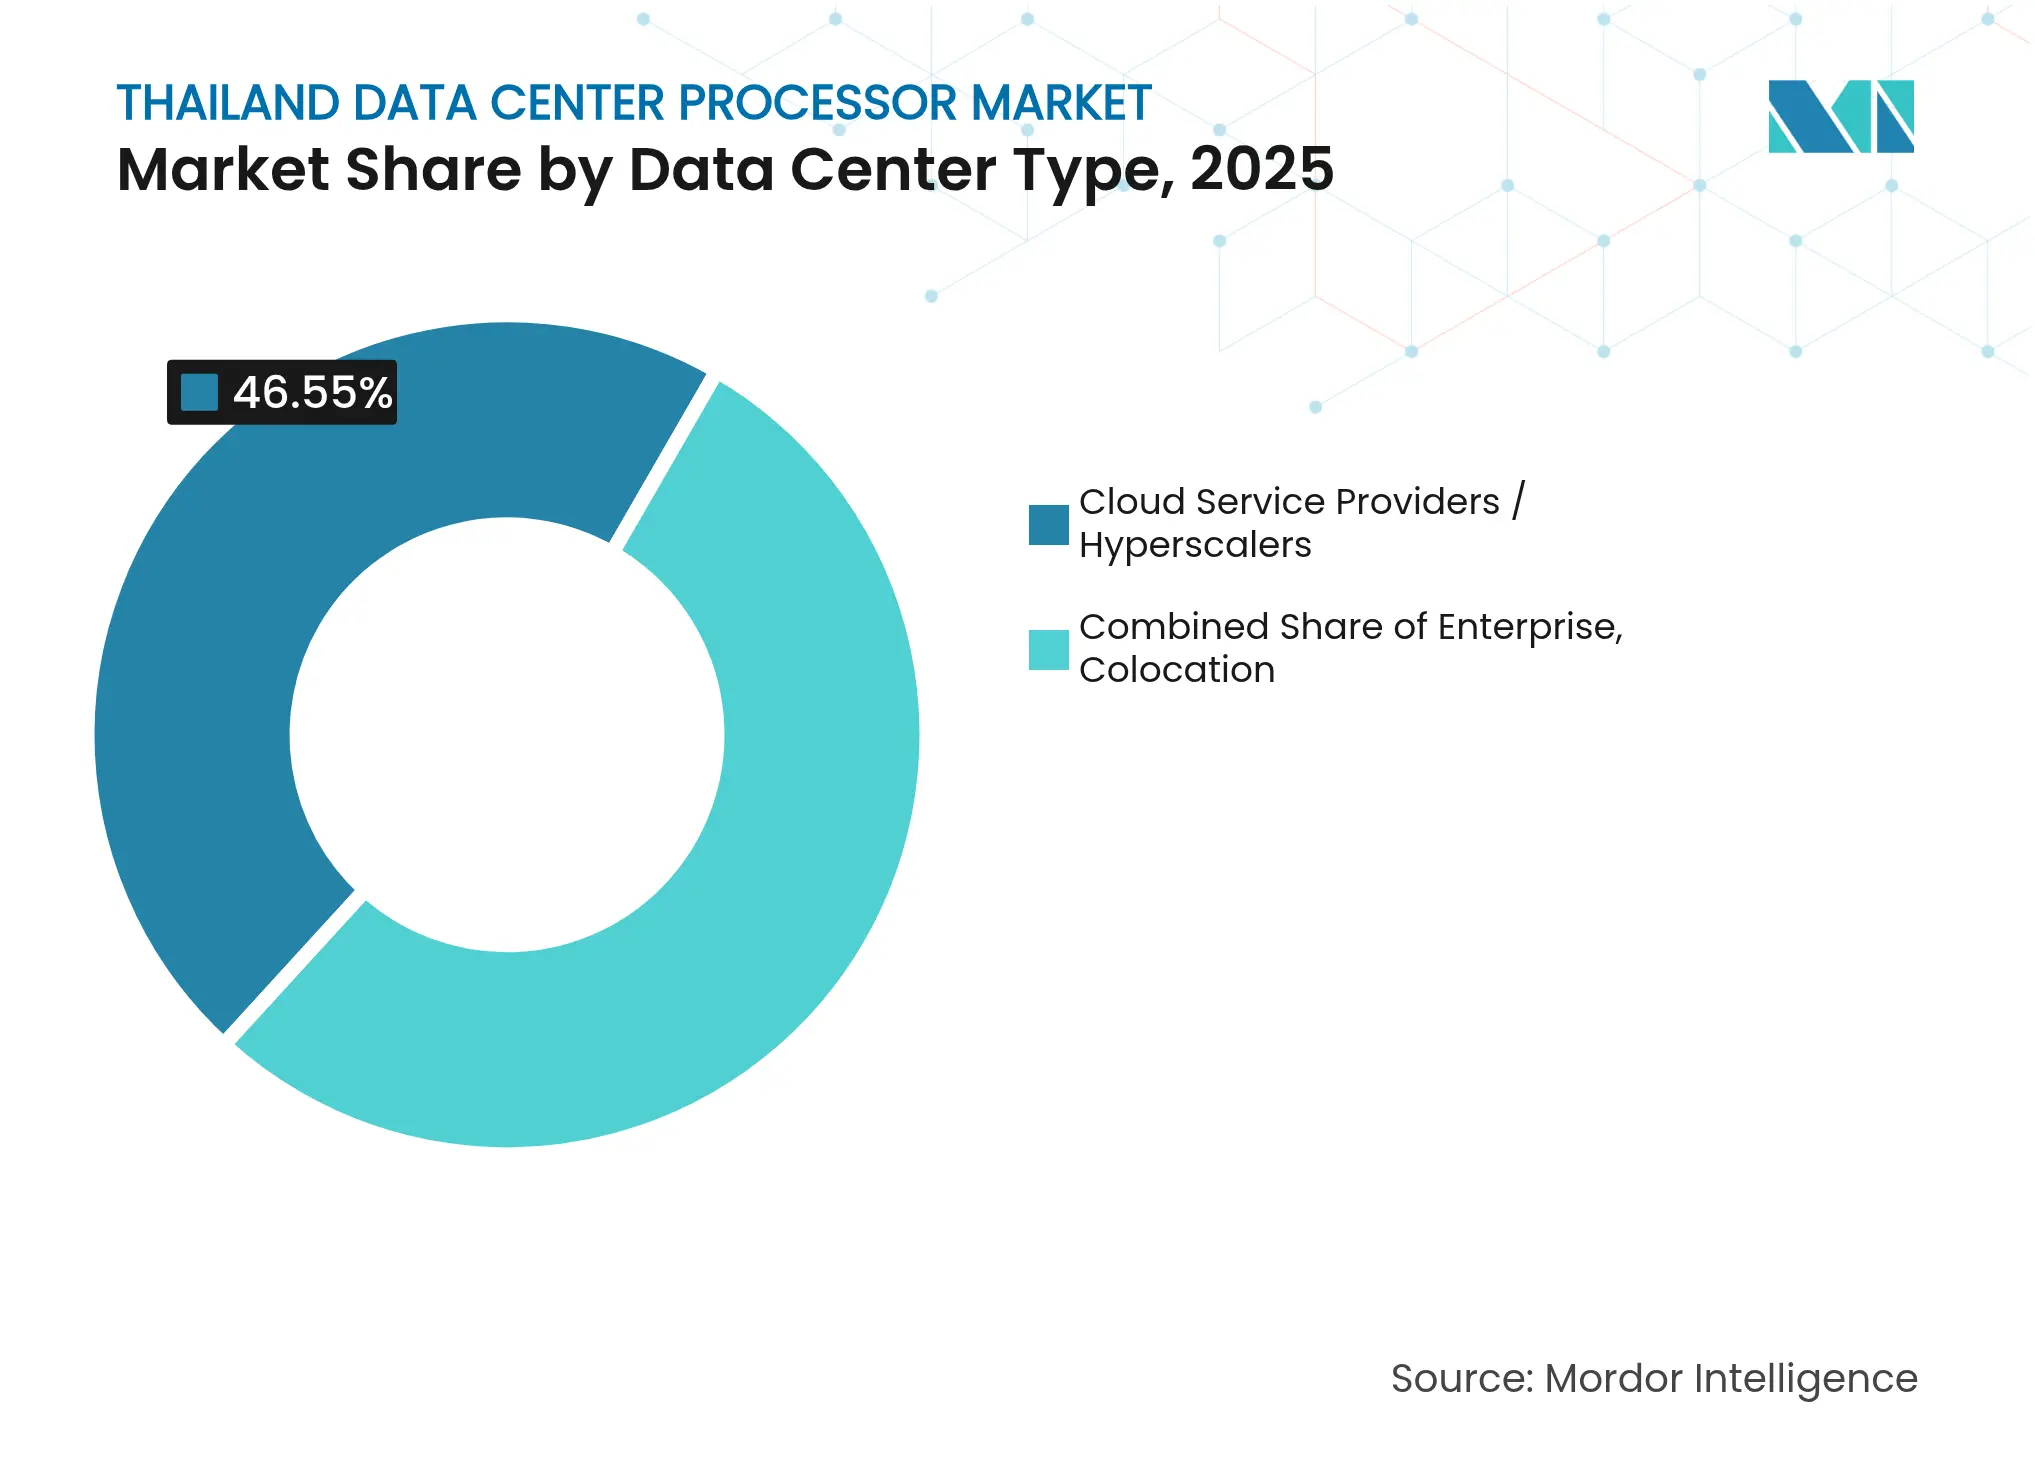
- By data-center type, Cloud service providers accounted for 46.55% of the Thailand data center processor market size in 2025, whereas colocation sites are advancing at a 46.0% CAGR through 2031.
Note: Market size and forecast figures in this report are generated using Mordor Intelligence's proprietary estimation framework, updated with the latest available data and insights as of 2026.
Thailand Data Center Processor Market Trends and Insights
Drivers Impact Analysis
| Driver | (~)% Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
|---|---|---|---|
5G roll-out accelerating edge & cloud workload
demand
|
8.2%
|
National, concentrated in Bangkok and EEC zones
|
Medium term (2-4 years)
|
Government digital-economy incentives & EEC tax
breaks
| 7.1% | Eastern Economic Corridor, spillover to Bangkok | Short term (≤ 2 years) |
Hyperscale cloud entrants' cap-ex (AWS, Google,
Alibaba)
| 9.3% | National, with primary hubs in Bangkok and Chonburi | Medium term (2-4 years) |
Crypto-mining compliance push for efficient processors
| 4.8% | National, with concentration in industrial zones | Short term (≤ 2 years) |
Corporate net-zero goals boosting ARM/low-power chips
| 6.2% | Bangkok metropolitan area, expanding to regional centers | Long term (≥ 4 years) |
National AI Action Plan (2022-27) driving AI
accelerator uptake
| 8.9% | National, with government sector leading adoption | Medium term (2-4 years) |
| Source: Mordor Intelligence | |||
5G Roll-out Accelerating Edge & Cloud Workload Demand
Thailand’s nationwide 5G build-out is redefining processor requirements. Ultra-low-latency use cases need inference engines close to subscribers, encouraging telecom operators to specify ARM-based chips for edge nodes because of their superior performance-per-watt. [1]True Corporation’s multi-city expansion highlights how decentralized topologies split demand between energy-efficient edge silicon and high-core-count x86 devices at regional hubs. Vendor roadmaps now prioritize thermal envelopes and real-time AI processing over peak clock speed, reshaping procurement criteria across the Thailand data center processor market.
Government Digital-Economy Incentives & EEC Tax Breaks
The EEC’s incentive framework trims total cost of ownership for high-density compute installations by up to 15%, giving Thailand cost parity with Singapore. These rebates accelerate AI-accelerator adoption, allowing firms to retain sensitive data onshore instead of relying exclusively on foreign clouds. Early adopters across automotive and electronics clusters in Chonburi have moved pilot ML workloads onto local silicon, reinforcing sovereign-cloud objectives within the Thailand data center processor market.[2]
Hyperscale Cloud Entrants’ Capital Expenditure
AWS, Google, and Alibaba each deploy distinct processor mixes in Thai facilities. AWS combines Intel Xeon for general workloads with in-house Graviton chips for cost-sensitive tiers. Google supplements x86 nodes with TPU racks, and Alibaba optimizes power budgets through ARM cores. Their disparate strategies create a heterogeneous ecosystem that spreads opportunity among multiple chipmakers and cements Thailand’s role as a multi-cloud hub.
National AI Action Plan Driving Accelerator Uptake
Public-sector projects under the 2022-27 plan mandate on-prem inference for health, education, and smart-city pilots. Procurement guidelines specify dedicated AI accelerators, lifting the penetration of ASICs and GPUs in provincial data centers. This policy channel secures baseline volumes and de-risks local supply chains, underpinning the rapid expansion of the Thailand data center processor market.
Restraint Impact Analysis
| Restraint | (~)% Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
|---|---|---|---|
Shortage of skilled chip & DC engineering talent
|
-4.7%
|
National, most acute in Bangkok and industrial zones
|
Long term (≥ 4 years)
|
Import tariffs & customs delays on high-end processors
| -3.2% | National, affecting all import-dependent segments | Short term (≤ 2 years) |
Power-quality issues outside Bangkok for high-TDP chips
| -2.8% | Regional centers excluding Bangkok metropolitan area | Medium term (2-4 years) |
US export controls on advanced AI GPUs creating supply
risk
| -5.1% | National, particularly affecting AI-focused enterprises | Medium term (2-4 years) |
| Source: Mordor Intelligence | |||
Shortage of Skilled Chip & DC Engineering Talent
Insufficient local expertise in ASIC design and advanced cooling limits deployment velocity. Rising salary premiums prompt Thai operators to outsource critical roles, lengthening commissioning cycles across the Thailand data center processor market. Universities are revamping curricula, yet a multi-year gap persists before supply meets demand.
US Export Controls on Advanced AI GPUs Creating Supply Risk
Tighter licencing on leading-edge GPUs complicates procurement for high-end Thai AI projects. Enterprises must commit capital without certainty of delivery dates or resort to alternative accelerators with lower throughput. This unpredictability inflates total project costs and moderates the otherwise steep growth curve of the Thailand data center processor market.[3]
Segment Analysis
By Processor Type: AI Accelerators Drive Next-Generation Workloads
CPU devices retained 31.85% of the Thailand data center processor market share in 2025, underscoring their role in payroll, ERP, and web hosting. The Thailand data center processor market size for AI accelerators is on track to enlarge at 45.3% CAGR, reflecting widespread machine-learning adoption under government stimulus. GPU cards remain pivotal for deep-learning training, especially in research clusters, whereas FPGA deployments concentrate on workloads demanding ultra-low latency.
Elevated electricity tariffs push buyers toward purpose-built ASICs that deliver higher operations-per-watt. Tier-2 colocation providers bundle liquid-cooled racks to host dense accelerator nodes, monetizing rising demand without overstressing grid connections. This heterogeneity signals a longer-term shift from monolithic CPU estates to specialized silicon within the Thailand data center processor market.
Note: Segment shares of all individual segments available upon report purchase
By Application: AI/ML Training Dominates Current Demand
AI/ML workloads commanded a 33.62% slice of the Thailand data center processor market in 2025, cementing machine intelligence as today’s principal consumption driver. The Thailand data center processor market size tied to advanced data analytics is expanding at a 45.8% CAGR as finance, telecom, and retail sectors embed predictive modeling into daily operations. High-performance computing clusters in universities prioritize weather forecasting and genomic research, while security analytics nodes gain traction due to stricter cyber-threat reporting.
Software-defined networks create fresh demand for packet-processing engines that can be re-flashed on-the-fly. As use cases diversify, operators allocate distinct processor pools—CPUs for transaction integrity, accelerators for AI inference, and FPGAs for network functions—strengthening overall spend within the Thailand data center processor market.
By Architecture: x86 Dominance Faces ARM Challenge
x86 retained 44.78% of the architecture mix in 2025, supported by a mature software stack and deep systems-integrator skills. Nevertheless, RISC-V is accelerating at 45.1% CAGR on the promise of open-source customization, while ARM wins in edge form factors where a 40% lower power draw matters. The Thailand data center processor market now features hybrid racks blending instruction sets to fine-tune cost-per-operation.
Government interest in RISC-V aligns with long-term digital sovereignty agendas, spurring local start-ups to design domain-specific cores. Meanwhile, hyperscalers pilot chiplet-based x86 variants that reduce die size and boost manufacturing yields. Multi-architecture adoption is set to grow as workload diversity intensifies across the Thailand data center processor market.
Note: Segment shares of all individual segments available upon report purchase
By Data Center Type: Hyperscalers Lead, Colocation Accelerates
Cloud service providers held 46.55% of deployments in 2025, driven by AWS, Google, and Alibaba region launches. Colocation space, rising at 46.0% CAGR, appeals to enterprises seeking hybrid strategies that balance sovereignty with hyperscale connectivity. The Thailand data center processor market size inside colocation halls will expand rapidly as mid-market firms lift their AI compute budgets without building in-house facilities.
Enterprise on-premise sites remain essential for regulated workloads, yet capital budgets are shifting toward procuring edge nodes connected to regional pods. Power quality outside Bangkok prompts operators to invest in modular DC designs and front-end power conditioning, shaping processor mix decisions throughout the Thailand data center processor market.
Note: Segment shares of all individual segments available upon report purchase
Geography Analysis
Bangkok and its periphery currently absorb over two-thirds of processor shipments as digital businesses cluster near submarine-cable gateways and the national internet exchange. The Thailand data center processor market size in the capital benefits from robust fiber density and reliable power, making it the launchpad for new architectures. Suburban expansion into Chonburi reflects tax relief under the EEC, where land availability supports hyperscale campuses.
Second-tier cities such as Chiang Mai and Khon Kaen are leveraging 5G backhaul upgrades to deploy compact edge facilities. Here, ARM and RISC-V boards tackle local inference tasks for smart-logistics and telemedicine pilots, diversifying revenue streams within the Thailand data center processor market. Power grids in these regions still face voltage variability, steering operators toward lower-TDP silicon.
Thailand’s role as an ASEAN logistics hub enables efficient cross-border parts flow. Supply-chain resilience improves as regional neighbours, notably Vietnam, add advanced test and assembly capacity that can funnel processors into Thai projects with reduced transit times. This proximity lessens tariff exposure and hedges against ocean-freight disruptions.
Competitive Landscape
Market Concentration
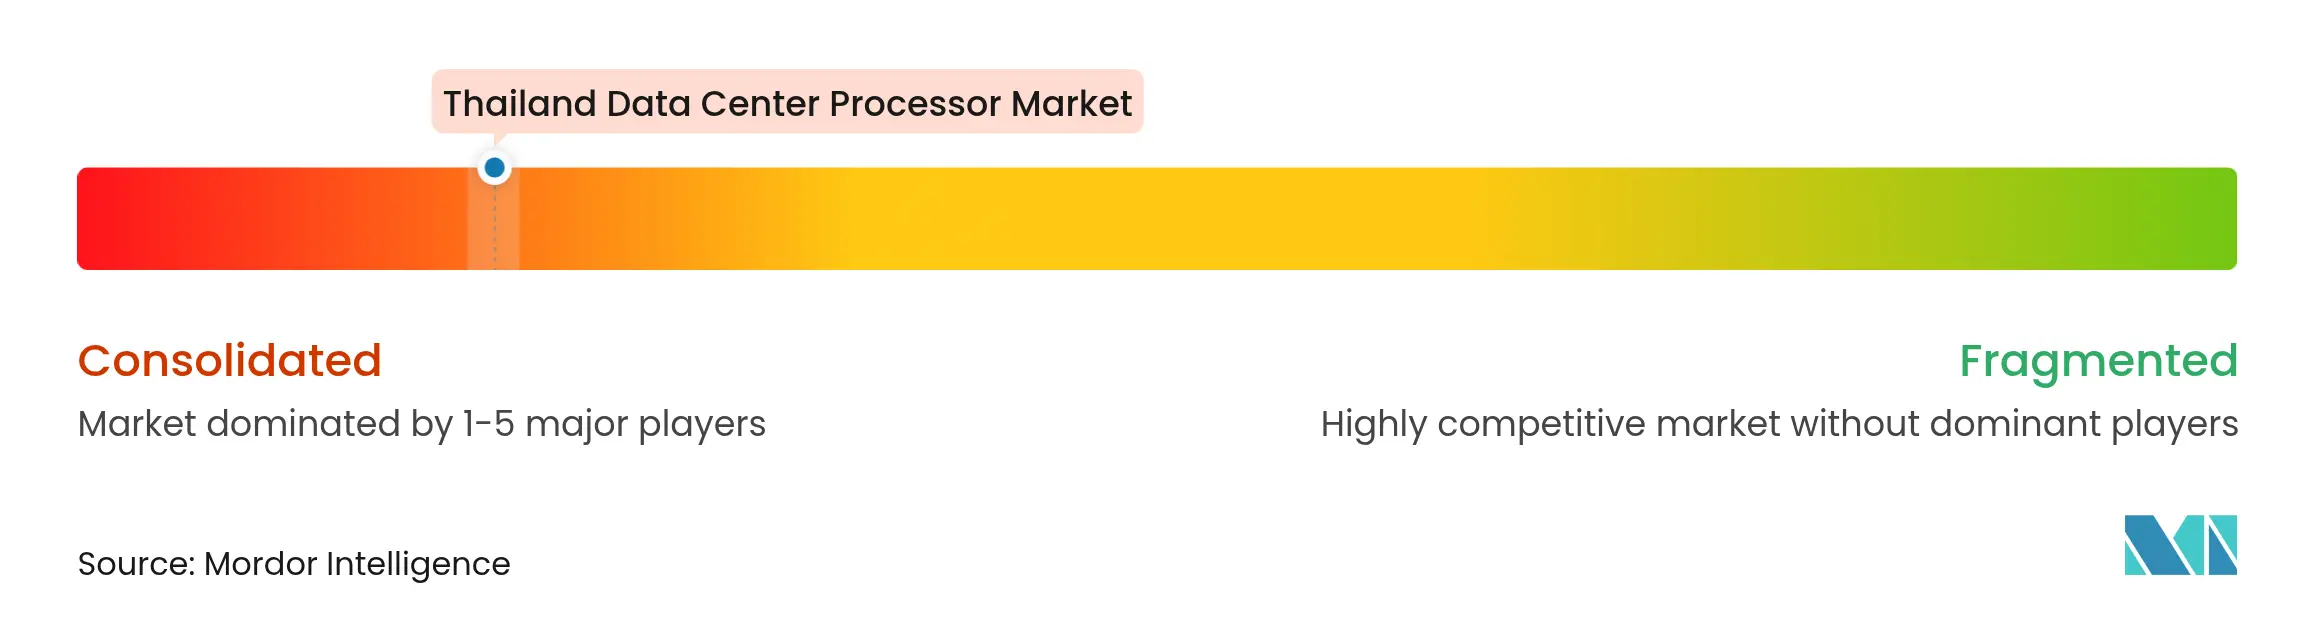
Market leadership remains in the hands of Intel, AMD, and NVIDIA, whose combined portfolios address general compute, HPC, and AI acceleration. Their deep channel networks and long software support cycles resonate with Thai CIOs who prioritize continuity. The Thailand data center processor market still offers headroom for challengers; Ampere Computing courts cloud natives with high-core ARM parts, while Huawei’s HiSilicon line targets AI inference under tighter power budgets.
Strategy is shifting from sheer core counts to workload-specific optimization. NVIDIA’s latest GPU modules integrate network adapters and shared memory stacks, simplifying AI cluster scale-out. AMD counters with 4th Gen EPYC processors that double energy efficiency over prior x86 iteration. Intel has fast-tracked 18A node production, promising competitive per-watt gains once volume ramps.
Thailand Data Center Processor Industry Leaders
*Disclaimer: Major Players sorted in no particular order
Recent Industry Developments
- June 2025: Schneider Electric partnered with NVIDIA to co-develop power and cooling solutions for AI factories, enhancing deployment viability in hot climates.
- June 2025: Samsung and Groq began mass production of 4 nm AI chips, easing tight supply for regional data centers.
- May 2025: AMD unveiled 4th Gen EPYC results showing up to 3.7× efficiency gains versus competing parts.
- February 2025: KASIKORN BANK detailed its roadmap to deploy energy-efficient processors as part of a net-zero pledge.
Table of Contents for Thailand Data Center Processor Industry Report
1. INTRODUCTION
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2. RESEARCH METHODOLOGY
3. EXECUTIVE SUMMARY
4. MARKET LANDSCAPE
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 5G roll-out accelerating edge and cloud workload demand
- 4.2.2 Government digital economy incentives and EEC tax breaks
- 4.2.3 Hyperscale cloud entrants cap-ex (AWS, Google, Alibaba)
- 4.2.4 Crypto-mining compliance push for efficient processors
- 4.2.5 Corporate net-zero goals boosting ARM/low-power chips
- 4.2.6 National AI Action Plan (2022-27) driving AI accelerator uptake
- 4.3 Market Restraints
- 4.3.1 Shortage of skilled chip and DC engineering talent
- 4.3.2 Import tariffs and customs delays on high-end processors
- 4.3.3 Power-quality issues outside Bangkok for high-TDP chips
- 4.3.4 US export controls on advanced AI GPUs creating supply risk
- 4.4 Supply-Chain Analysis
- 4.5 Regulatory Landscape
- 4.6 Technological Outlook
- 4.7 Porter's Five Forces Analysis
- 4.7.1 Bargaining Power of Suppliers
- 4.7.2 Bargaining Power of Consumers
- 4.7.3 Threat of New Entrants
- 4.7.4 Threat of Substitutes
- 4.7.5 Intensity of Competitive Rivalry
- 4.8 Assessment of Macroeconomic Factors on the Market
5. MARKET SIZE and GROWTH FORECASTS (VALUE)
- 5.1 By Processor Type (Value)
- 5.1.1 GPU
- 5.1.2 CPU
- 5.1.3 FPGA
- 5.1.4 AI Accelerator/ASIC
- 5.2 By Application (Value)
- 5.2.1 Advanced Data Analytics
- 5.2.2 AI/ML Training and Inference
- 5.2.3 High-Performance Computing
- 5.2.4 Security and Encryption
- 5.2.5 Network Functions Virtualisation
- 5.2.6 Others
- 5.3 By Architecture (Value)
- 5.3.1 x86
- 5.3.2 ARM-based
- 5.3.3 RISC-V
- 5.3.4 Power
- 5.4 By Data Center Type (Value)
- 5.4.1 Enterprise
- 5.4.2 Colocation
- 5.4.3 Cloud Service Providers / Hyperscalers
6. COMPETITIVE LANDSCAPE
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share for key companies, Products and Services, and Recent Developments)
- 6.4.1 Intel Corporation
- 6.4.2 Advanced Micro Devices Inc.
- 6.4.3 NVIDIA Corporation
- 6.4.4 Arm Ltd.
- 6.4.5 IBM Corporation
- 6.4.6 Broadcom Inc.
- 6.4.7 Marvell Technology Inc.
- 6.4.8 Toshiba Electronic Devices and Storage Corp.
- 6.4.9 Qualcomm Technologies Inc.
- 6.4.10 Ampere Computing LLC
- 6.4.11 Huawei (HiSilicon and Kunpeng)
- 6.4.12 Alibaba Group
- 6.4.13 Samsung Electronics (Exynos DC)
- 6.4.14 MediaTek Inc.
- 6.4.15 Graphcore Ltd.
- 6.4.16 Cerebras Systems Inc.
- 6.4.17 Tenstorrent Inc.
- 6.4.18 VIA Technologies Inc.
- 6.4.19 SiFive Inc.
- 6.4.20 Tachyum Inc.
7. MARKET OPPORTUNITIES and FUTURE OUTLOOK
- 7.1 White-space and Unmet-Need Assessment
Scope and Methodology
- Data centers house and manage critical applications and data, using computing and storage networks for efficient delivery. Processors—GPUs, CPUs, and TPUs—are central to their operation. GPUs handle multitasking, excelling in graphics rendering and AI tasks. CPUs, with multi-core architecture, support parallel processing. TPUs, designed for machine learning, stand out from GPUs, which have transitioned from graphics to AI applications.
- Thailand Data Center Processor Market is Segmented by Processor Type (CPU, GPU, FPGA, AI Accelerators), by Application (Advanced Data Analytics, AI/ML Training and Inferences, High Performance Computing, Security and Encryption, Network Functions, and Others), by Architecture (x86 and Non-x86 (ARM, Power and other processors), and by Data Center Type (Enterprise, Colocation and Cloud Service Providers). The Report Offers the Market Size and Forecasts for all the Above Segments in Terms of Value (USD).
| By Processor Type (Value) | GPU |
| CPU | |
| FPGA | |
| AI Accelerator/ASIC | |
| By Application (Value) | Advanced Data Analytics |
| AI/ML Training and Inference | |
| High-Performance Computing | |
| Security and Encryption | |
| Network Functions Virtualisation | |
| Others | |
| By Architecture (Value) | x86 |
| ARM-based | |
| RISC-V | |
| Power | |
| By Data Center Type (Value) | Enterprise |
| Colocation | |
| Cloud Service Providers / Hyperscalers |
Key Questions Answered in the Report
What is the current value of the Thailand data center processor market?
Which processor type is growing the fastest in Thailand?
How significant are hyperscale cloud providers to Thai demand?
Why are ARM and RISC-V architectures gaining ground?
More reports on data centers
Find the right report below.
