
Sweden Hyperscale Data Center Market Size and Share
Market Overview
| Study Period | 2020 - 2031 |
|---|---|
| Forecast Data Period | 2026 - 2031 |
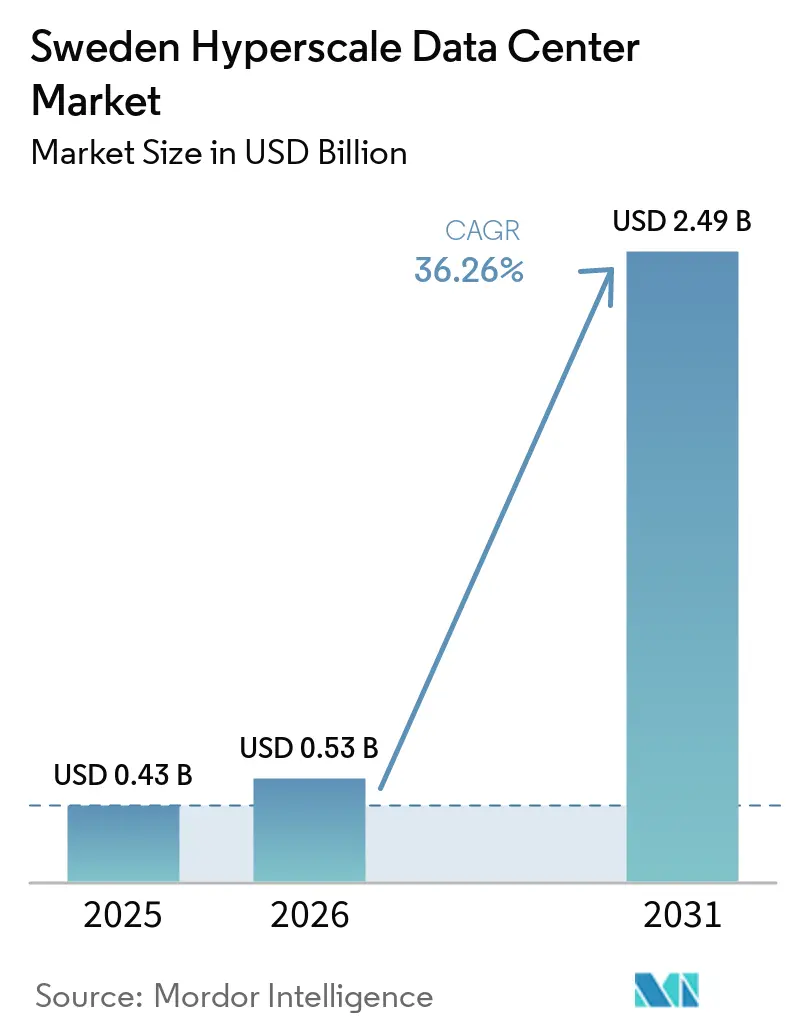
| Base Year Market Size (2025) | USD 0.43 Billion |
| Market Size (2026) | USD 0.53 Billion |
| Market Size (2031) | USD 2.49 Billion |
| Growth Rate (2026 - 2031) | 36.26 % |
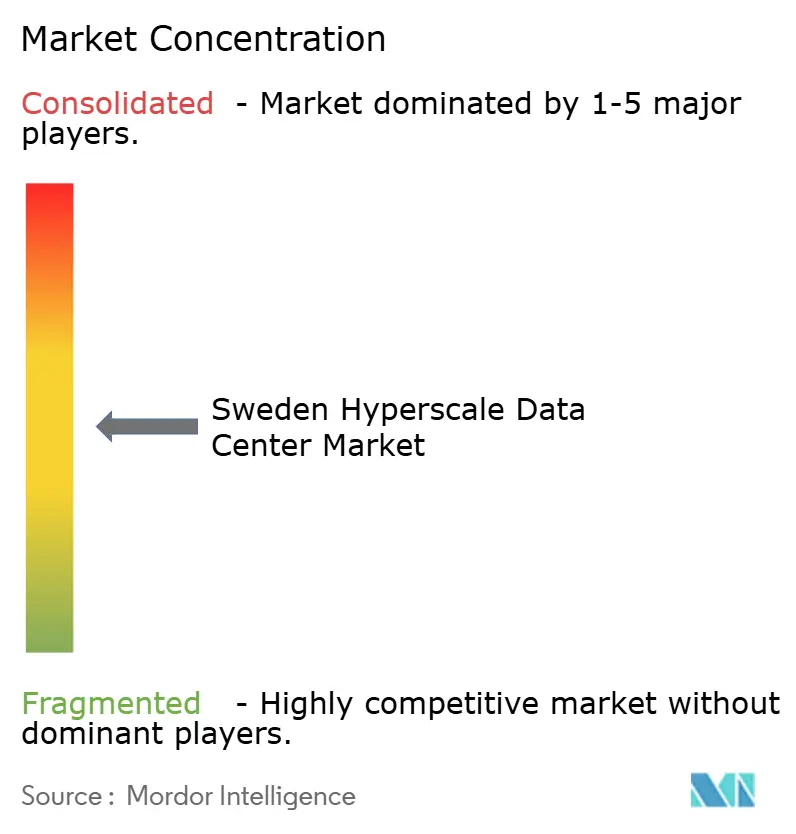
| Market Concentration | Medium |
Major Players *Disclaimer: Major Players sorted in no particular order Image © Mordor Intelligence. Reuse requires attribution under CC BY 4.0. | |
Sweden Hyperscale Data Center Market Analysis by Mordor Intelligence
The Sweden Hyperscale Data Center Market size is expected to grow from USD 0.43 billion in 2025 to USD 0.53 billion in 2026 and is forecast to reach USD 2.49 billion by 2031 at 36.26% CAGR over 2026-2031. In terms of production volume, the market was valued at 0.63 thousand megawatt in 2025 and is expected to grow from 0.65 thousand megawatt in 2026 to 3.72 thousand megawatt by 2031, at a CAGR of 41.90% during the forecast period (2026-2031).
Solid investment momentum, highly competitive renewable-energy pricing, and a policy environment that rewards domestic data processing underpin this expansion. Subsea cable upgrades strengthen international connectivity, while district-heat reuse programs lower operating costs and reinforce sustainability credentials. The arrival of ultra-large AI training clusters accelerates innovation in mechanical infrastructure, especially in liquid cooling. Together, these forces position the Sweden hyperscale data center market as the Nordic region’s primary magnet for next-generation cloud and AI workloads.
Key Report Takeaways
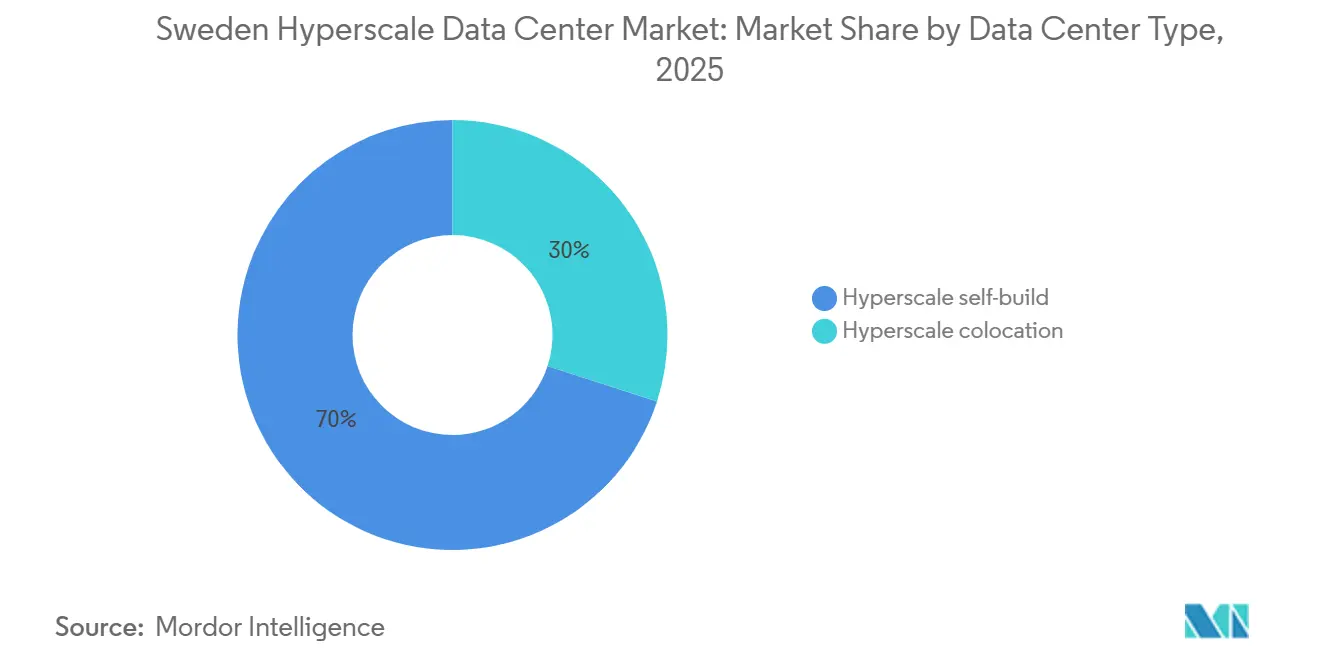
- By data center type, hyperscale self-builds accounted for 70% of Sweden's hyperscale data center market share in 2025, while hyperscale colocation is projected to expand at a 39.50% CAGR through 2031.
- By component, IT infrastructure accounted for 45% of the Sweden hyperscale data center market size in 2025, while mechanical infrastructure is projected to grow at a 40.20% CAGR through 2031.
- By tier standard, Tier III facilities accounted for 80% of the Sweden hyperscale data center market size in 2025, while Tier IV deployments are projected to grow at a 42.10% CAGR through 2031.
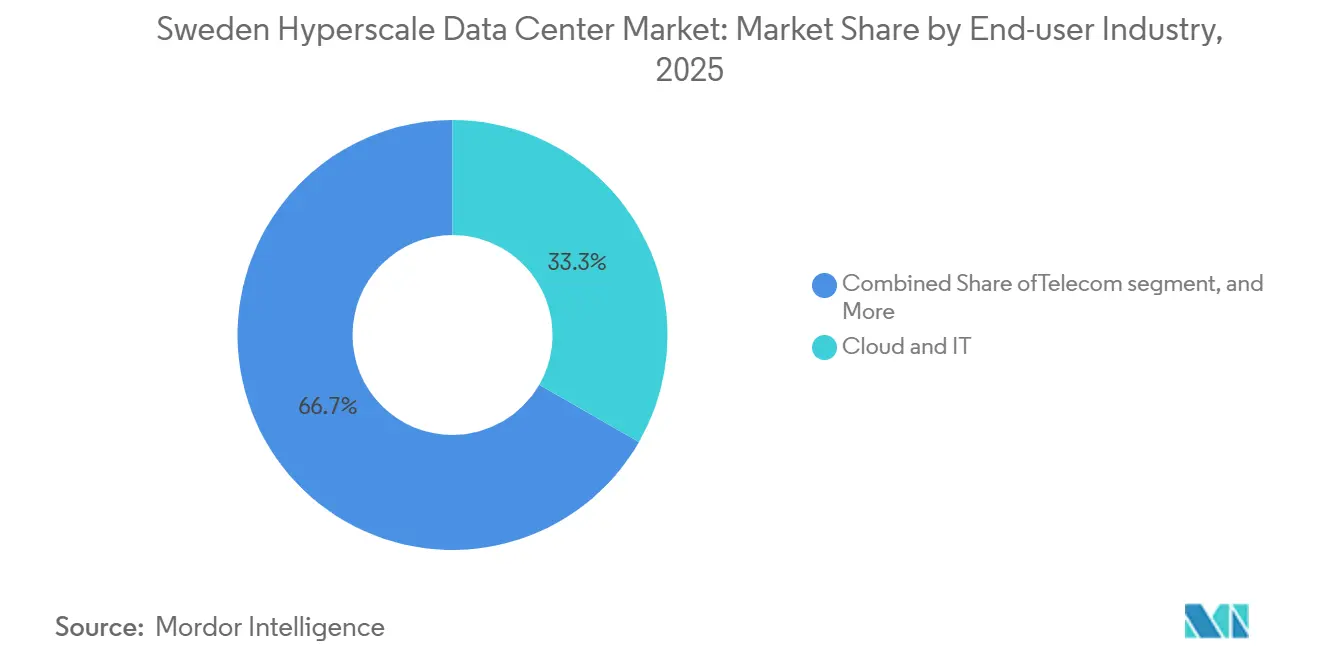
- By end-user industry, cloud and IT led with 33.3% revenue share in 2025, while BFSI is forecast to expand at a 38.80% CAGR through 2031.
- By data center size, massive facilities (>25 MW and ≤60 MW) accounted for 50% of the Swedish hyperscale data center market in 2025, while mega facilities (>60 MW) are projected to see the fastest growth, at a 44.50% CAGR through 2031.
Sweden Hyperscale Data Center Market Trends and Insights
Drivers Impact Analysis*
| Driver | (~) % Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
|---|---|---|---|
| Surge in cloud-region launches by hyperscalers | +8.50% | National, concentrated in Stockholm-Mälardalen region | Short term (≤ 2 years) |
| Rapid build-out of new subsea cable landings to Swedish shores | +6.20% | Coastal regions, particularly west coast connectivity hubs | Medium term (2-4 years) |
| Government digital-sovereignty and data-residency mandates | +7.80% | National, with priority for government and BFSI sectors | Medium term (2-4 years) |
| Abundant hydro and wind PPAs lowering total energy cost | +5.90% | Northern Sweden hydroelectric regions, offshore wind zones | Long term (≥ 4 years) |
| Gen-AI inferencing demand spurring liquid-cooled edge nodes | +4.10% | Urban centers with high compute density requirements | Short term (≤ 2 years) |
| Mandated district-heat reuse unlocking new revenue streams | +2.40% | Urban districts with existing heating infrastructure | Long term (≥ 4 years) |
| Source: Mordor Intelligence | |||
Surge in cloud-region launches by hyperscalers
Microsoft’s USD 3.2 billion allocation for new Swedish cloud regions illustrates a sovereignty-first strategy that is reshaping hyperscale capital plans [1]. AWS is adding three facilities in Mälardalen using lower-carbon steel, cutting build-phase emissions by 70%. Each announcement compresses competitors’ rollout schedules, spurring a self-reinforcing investment cycle. Domestic newcomer Evroc is leveraging the momentum to secure land near Arlanda Airport for a hyperscale AI campus. These overlapping projects amplify demand for specialty cooling systems and high-voltage interconnects at a pace unseen in traditional colocation builds.
Rapid build-out of new subsea cable landings to Swedish shores
GlobalConnect’s Nordic Super Fiber Cable adds 3 Pbps of capacity and underpins Sweden’s pivot from a regional to a continental gateway. A SEK 75 million (USD 7.77 million) land link to Finland hardens Nordic redundancy and mitigates recent cable-break risks in the Baltic. Operators now prioritize coastal campuses that pair landing stations and data halls to shave milliseconds of latency. Enhanced resilience also elevates Sweden’s appeal for disaster-recovery nodes serving Germany, Poland, and the UK.
Government digital-sovereignty and data-residency mandates
Sweden’s 2025-2030 digitalization plan cements local data processing as a national-security pillar. The EUR 1 billion (USD 1.15 billion) public-sector infrastructure budget requires that sensitive workloads stay within national borders. Tele2’s sovereign-cloud platform and Swedbank’s domestic private-cloud rollout confirm that both public and financial institutions now index site selection on country-level sovereignty rather than price. These mandates widen the competitive moat for Sweden hyperscale data center market entrants that can provide in-country, Tier IV-certified capacity.
Abundant hydro and wind PPAs lowering total energy cost
Vattenfall’s 24/7 renewable-matching for Microsoft showcases how granular power-purchase agreements slash emissions without eroding uptime [2]. Google’s additional Swedish wind buys for its Finnish hub indicate cross-border arbitrage opportunities that reward hyperscale buyers willing to contract in bulk. Planned small modular reactors could supply carbon-free baseload, further flattening electricity price volatility
Restraints Impact Analysis*
| Restraint | (~) % Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
|---|---|---|---|
| Transmission-grid congestion in urban clusters | -4.70% | Stockholm metropolitan area, Gothenburg region | Short term (≤ 2 years) |
| Shortage of HV electrical and mechanical O and M talent | -3.20% | National, acute in northern development zones | Medium term (2-4 years) |
| Water-stress moratoria on evaporative cooling designs | -2.10% | Southern Sweden, drought-prone municipalities | Long term (≥ 4 years) |
| GPU / photonics allocation bias toward Tier-1 European regions | -1.80% | National, affecting AI-optimized facility development | Short term (≤ 2 years) |
| Source: Mordor Intelligence | |||
Transmission-grid congestion in urban clusters
Multiple 50-100 MW interconnect requests converge on Stockholm’s 400 kV ring, stretching queue times to 18 months. Vattenfall’s fast-track program with Svenska Kraftnät mitigates delays yet still requires SEK 2 billion upgrades for Brookfield’s 750 MW Strängnäs campus. Northern hydro surplus remains stranded until long-lead reinforcement lines come online.
Shortage of HV electrical and mechanical O and M talent
Instalco reports a multi-year backlog for certified high-voltage technicians, forcing operators to import labor at premium rates [3]. Training programs at Luleå Technical University will not close the gap before 2027, compelling developers to pre-commit to workforce pipelines when securing land.
*Our forecasts treat driver/restraint impacts as directional, not additive. The impact forecasts reflect baseline growth, mix effects, and variable interactions.
Segment Analysis
By Data Center Type: Self-Build Dominance Drives Market Evolution
Self-builds accounted for 70% of Sweden's hyperscale data center market revenue in 2025, reflecting hyperscalers' preference for greater control over facility design, power infrastructure, and high-density AI requirements. These facilities enable operators to optimize infrastructure configurations around specific workload and performance requirements, supporting continued investment in purpose-built hyperscale campuses.
Colocation, while smaller, is projected to expand at a 39.50% CAGR through 2031, driven by rising demand from AI and cloud workloads and by hyperscalers' and enterprises' ability to access scalable data center capacity without the capital requirements of building their own facilities. Providers such as atNorth are strengthening their positioning through renewable power sourcing and heat-reuse initiatives, supporting demand from customers with sustainability requirements. The rapid expansion of hyperscale colocation alongside self-build campuses points toward a more diversified deployment model, supporting long-term growth in Sweden's hyperscale data center market.
By Component: Mechanical Infrastructure Leads Innovation Wave
IT hardware still accounts for 45% of spend, yet mechanical infrastructure is projected to post the fastest growth at a 40.20% CAGR through 2031. The increasing deployment of high-density AI workloads is driving greater demand for advanced cooling infrastructure, including direct-to-chip liquid cooling, rear-door heat exchangers, and heat-recovery systems, thereby increasing the importance of mechanical infrastructure in hyperscale data center development.
Electrical infrastructure continues to support rising rack power densities, while mechanical systems are gaining strategic importance as operators optimize facilities for higher-density workloads and improved energy efficiency. The growing integration of advanced cooling and heat-recovery solutions is therefore reshaping infrastructure requirements, project designs, and capex profiles within the Sweden hyperscale data center market.
By Tier Standard: Tier IV Growth Reflects AI Reliability Demands
Tier III remains dominant, but Tier IV’s 42.10% CAGR signals a stronger shift toward higher-reliability infrastructure for latency-sensitive AI workloads. New hyperscale developments increasingly prioritize redundant power feeds, resilient electrical systems, and enhanced mechanical redundancy to support demanding AI workloads and minimize service interruptions.
New builds are increasingly incorporating higher-tier resilience at the design stage rather than relying on retrofits, helping optimize lifecycle costs and infrastructure performance. This trajectory is increasing demand for premium power and cooling equipment within the Sweden hyperscale data center market while adding complexity to project design and construction requirements.
By End-User Industry: BFSI Transformation Accelerates Digital Demand
Cloud and IT held 33.3% of revenue in 2025, yet BFSI’s 38.80% CAGR reflects accelerating demand for secure, compliant, and locally hosted computing capacity. Financial institutions such as Nordea and Swedbank support demand for dedicated, resilient data center capacity that can meet regulatory and data-residency requirements.
Public-sector modernization and continued digitalization are supporting steady demand across Sweden, while manufacturers increasingly adopt hybrid cloud solutions to retain control over sensitive operational data. Together, these verticals diversify the revenue base of the Swedish hyperscale data center market and support sustained utilization growth.

By Data Center Size: Mega Facilities Drive Capacity Concentration
Massive campuses between 25–60 MW accounted for 50% of live power in 2025, balancing grid-connection considerations with economies of scale. Mega sites above 60 MW are projected to expand at a 44.50% CAGR through 2031, as AI workloads drive demand for larger, high-density campuses with substantial power and connectivity requirements. Large-scale developments are increasingly being designed around centralized power infrastructure, network capacity, and phased expansion.
EcoDataCenter’s large-scale development roadmap illustrates the phased-build approach, aligning power-availability milestones with contracted demand and future capacity expansion. Such deployments are increasing the size of Sweden's hyperscale data center market and reinforcing the need for coordinated grid capacity, substation, and power infrastructure upgrades.
Geography Analysis
The Stockholm-Mälardalen corridor anchors 55% of Nordic internet traffic and hosts more than 125 carriers, anchoring it as the logical first stop for international entrants. Subsea landing upgrades fortify the capital’s role as the principal European gateway for Nordic cloud flows, encouraging hyperscalers to co-locate cable heads and compute halls. Urban district-heat grids enable operators to monetize thermal output, lowering effective PUE and trimming energy costs below EUR 0.03 per kWh.
Northern Sweden leverages abundant hydro resources and cool ambient temperatures that facilitate free-air cooling for up to 10 months each year. Facebook’s long-standing Luleå campus validated the region, and EcoDataCenter’s planned 150 MW Östersund site accelerates the northern cluster, adding renewable capacity without stressing urban grids. The prospect of small modular reactors near Ringhals introduces future baseload options that could further reduce carbon intensity.
Western coastal municipalities increasingly woo hyperscale investments to exploit newly reinforced subsea landings. GlobalConnect’s fiber corridors shorten round-trip times to Germany and the UK, offering an alternate to congested Danish routes. This tri-regional dynamic diversifies site selection within the Sweden hyperscale data center market and moderates power-price disparities across the country.
Competitive Landscape
Global hyperscalers AWS, Microsoft, and Google anchor the ecosystem with self-built mega-campuses that set benchmarks for scale and efficiency. International colocation leaders Equinix, Digital Realty, and NTT supplement their capacity with carrier-dense facilities for enterprises seeking rapid deployment. Nordic specialists EcoDataCenter, atNorth, and Bahnhof differentiate by offering climate-positive operations, heat-recovery integration, and low-carbon construction materials.
Sustainability narratives now extend to power-sourcing transparency and embodied-carbon disclosure. EcoDataCenter’s biomass-augmented Falun campus and Digital Realty’s district-heat partnerships illustrate how operators translate green credentials into long-term price advantages. Small-modular-reactor developers such as Kärnfull Next represent a potential disruptive cohort, promising zero-carbon baseload that could reset market power-pricing curves within a decade.
Competitive focus is also shifting toward AI-optimized white space. The NVIDIA-backed AI Technology Center demonstrates how sovereign AI demand candrivee GPUcluster concentration inn colocation environments, forcing incumbents to re-engineer layouts for liquid cooling and 100 kW racks. Operators able to marry carrier density, heat-reuse revenue, and Tier IV resiliency will command premium pricing in the Sweden hyperscale data center market.
Sweden Hyperscale Data Center Industry Leaders
-
Amazon Web Services, Inc.
-
Microsoft Corporation
-
Google LLC
-
Meta Platforms, Inc.
-
Digital Realty Trust, Inc.
- *Disclaimer: Major Players sorted in no particular order
Recent Industry Developments
- January 2025: GlobalConnect completed a land-based Sweden-Finland fiber link carrying up to 3 Pbps, bolstering Nordic digital security.
- February 2025: STACK Infrastructure advanced a 30 MW Stockholm campus, with 18 MW under construction in a sustainability-focused global expansion.
- March 2025: Areim raised USD 977 million to fund green data-center projects across the Nordics, with Sweden as a priority.
- May 2025: A Swedish consortium with AstraZeneca, Ericsson, Saab, SEB, and Wallenberg Investments partnered with NVIDIA to deploy two DGX SuperPODs, creating Sweden’s largest enterprise AI supercomputer.
- June 2025: Brookfield committed SEK 95 billion (USD 9.9 billion) for a 750 MW AI data-center campus in Strängnäs, more than doubling its earlier plan.
Research Methodology Framework and Report Scope
Market Definitions and Key Coverage
Mordor Intelligence defines the Swedish hyperscale data center market as the annual revenue stream generated by newly built or leased facilities delivering at least 4 MW of IT load to a single owner or anchor tenant and engineered for cloud-scale automation, modular expansion, and PUE targets below 1.3.
Scope exclusion: Edge micro-sites below 4 MW and enterprise on-premises server rooms are excluded.
Segmentation Overview
- By Data Center Type
- Hyperscale self-build
- Hyperscale colocation
- By Component
- IT Infrastructure
- Server Infrastructure
- Storage Infrastructure
- Network Infrastructure
- Electrical Infrastructure
- Power Distribution Unit
- Transfer Switches and Switchgears
- UPS Systems
- Generators
- Other Electrical Infrastructure
- Mechanical Infrastructure
- Cooling Systems
- Racks
- Other Mechanical Infrastructure
- General Construction and Services
- Core and Shell Development
- Installation and Commisioning Services
- Design Engineering
- Fire Detection, Suppression and Physical Security
- DCIM/BMS Solutions
- IT Infrastructure
- By Tier Standard
- Tier III
- Tier IV
- By End-User Industry
- Cloud and IT
- Telecom
- Media and Entertainment
- Government
- BFSI
- Manufacturing
- E-Commerce
- Other End Users
- By Data Center Size
- Large (Less than equal to 25 MW)
- Massive (Greater than 25 MW and less than equal to 60 MW)
- Mega (Greater than 60 MW)
Detailed Research Methodology and Data Validation
Primary Research
We interviewed Swedish grid planners, real-estate developers, Nordic cloud-region directors, HVAC OEM engineers, and channel partners across Stockholm, Vasteras, and Lulea. Their inputs helped validate power-price assumptions, attainable rack densities, and likely commissioning timetables, ensuring that survey feedback bridged gaps left by desk research.
Desk Research
Our analysts began with statutory and open datasets from bodies such as the Swedish Energy Agency, Svenska kraftnat, the Swedish Post & Telecom Authority, and Eurostat, which quantify grid capacity, latency corridors, and data-traffic growth. Trade association portals like SweDCI, Cloudscene, and the European Data Centre Association supplied facility counts and tier splits that anchor installed base estimates.
These insights were enriched with company filings, investor decks, and reputable press archives captured via D&B Hoovers and Dow Jones Factiva, while patent clusters for immersion cooling were sampled through Questel to flag emerging capex drivers. The sources listed are illustrative; many additional public and paid references were consulted for cross-checks and clarification.
Market-Sizing & Forecasting
A top-down build starts with Stockholm and regional IT-load statistics, electricity-tax records, and announced hyperscale capex, which are then converted to revenue using sampled average build cost per deployed megawatt. Results are corroborated through a selective bottom-up roll-up of disclosed campus capacities and channel ASP × volume checks. Key variables like renewable-energy price index, average rack density, AI/Telco workload penetration, tax-rebate runway, and grid-connection lead time feed a multivariate regression that generates the 2025-2031 outlook. Scenario analysis adjusts for power-pricing shocks.
Data Validation & Update Cycle
Outputs pass variance scans against historical series, peer ratios, and fresh primary calls before senior review. Models refresh annually, with interim updates triggered by >=100 MW announcements or regulatory moves; a last-mile sense check precedes every client delivery.
Why Mordor's Sweden Hyperscale Data Center Baseline Rings True
Published numbers differ because firms mix geographies, measure spend instead of revenue, or omit cooling retrofits. Our disciplined scope, annual refresh, and dual-layer validation keep the 2025 market value at USD 427.64 million both transparent and repeatable.
Key gap drivers include: some publishers quote global or Nordic aggregates, others apply unvetted ASP uplifts, and a few rely on outdated capacity pipelines lacking on-site verification.
Benchmark comparison
| Market Size | Anonymized source | Primary gap driver |
|---|---|---|
| USD 427.64 M (2025) | Mordor Intelligence | - |
| USD 162.79 B (2024) | Global Consultancy A | Global scope, spend metric, single-step top-down model |
| USD 2.8 B (2023) | Trade Journal B | Investment value, mixes colocation & enterprise halls, unclear FX basis |
Taken together, the comparison shows that once scope and metric misalignments are stripped away, Mordor's grounded, variable-driven baseline offers decision-makers a dependable reference point for Sweden's rapidly scaling hyperscale landscape.
Key Questions Answered in the Report
What is the forecast value of the Sweden hyperscale data center market in 2031?
It is projected to reach USD 2.49 billion by 2031, growing at a 36.26% CAGR.
Which segment is expanding fastest by tier standard?
Tier IV facilities are projected to advance at a 42.10% CAGR through 2031, driven by increasing requirements for resilient infrastructure to support high-density AI workloads and mission-critical computing.
How do Sweden’s renewable resources benefit data-center operators?
Operators secure 24/7 hydro- and wind-matched PPAs that lower total energy cost and support aggressive sustainability targets.
Why is BFSI demand rising so quickly?
Domestic sovereignty rules require Swedish processing of sensitive financial data, driving a 38.80% CAGR for BFSI footprints.
What risk could slow near-term growth?
Urban transmission-grid congestion in Stockholm and Gothenburg may delay new power connections by up to 18 months.
- Data Center Construction Market Construction worldwide, split by tier, facility size and facility type.
- Artificial Intelligence (AI) Data Center Market AI facilities worldwide, split by facility type, component and tier.
- Data Center Server Market Servers worldwide, split by tier, facility size and facility type.
- Sweden Data Center Construction Market Sweden's construction, split by infrastructure, tier and end user.
- Sweden Data Center Storage Market Storage in Sweden, split by facility size and tier.
- Spain Data Center Power Market Spain power systems, split by component, facility type and facility size.
- Sweden Data Center Physical Security Market Physical security in Sweden, split by solution type and service type.