
Spa Market Size and Share

Spa Market Analysis by Mordor Intelligence
The spa market size was valued at USD 164.7 billion in 2026 and estimated to grow from USD 174.6 billion in 2027 to reach USD 236.8 billion by 2032, at a CAGR of 6.28% during the forecast period (2027-2032).
Wellness travel and rising real income in China support demand for resort spa experiences and repeat local treatments. Hotel operators can integrate treatment space into a stay, while specialist networks can expand through existing service locations. Mobile booking extends the sales window, but delivering those appointments depends on usable space and staffing. Seasonality makes peak demand an imperfect guide to annual returns, so resort spas that add capacity for the busiest weeks risk carrying it unused through slower months.
Key Report Takeaways
- By service type, massage and body treatments held a 36.95% spa market share in 2026, while medical and medi-spa treatments are forecast to grow fastest at a CAGR of 9.12% during 2027-2032.
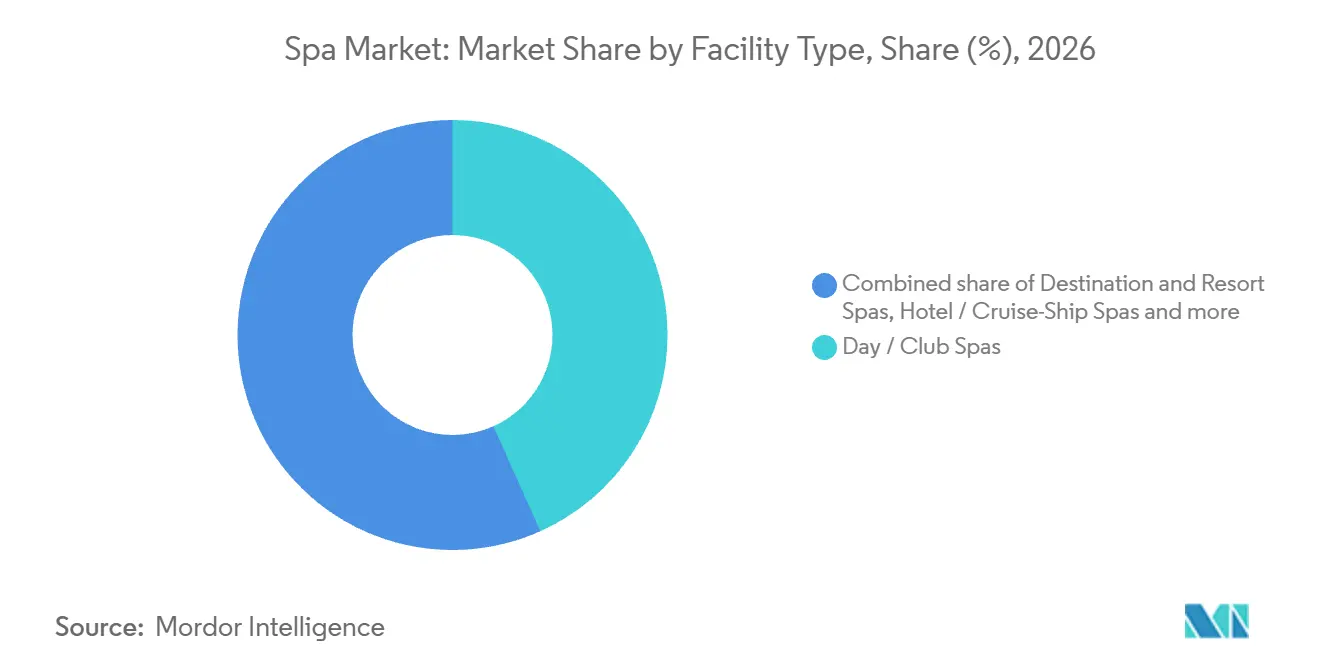
- Across facility types, day and club spas accounted for a 43.3% share of the spa market size in 2026, whereas medical spas are projected to be the fastest-growing segment, with a CAGR of 12.63% during 2027-2032.
- Booking channels were led by on-site and walk-in bookings with 70.83% of spa service revenue in 2026, while online and mobile app bookings are forecast to grow fastest at a CAGR of 8.21% during 2027-2032.
- Among end users, women accounted for 55.84% of spa service revenue in 2026, with family and group customers forecast to grow fastest at a CAGR of 8.72% during 2027-2032.
- Geographically, Europe accounted for 35.73% of spa service revenue in 2026, and Asia-Pacific is forecast to be the fastest-growing region at a CAGR of 9.15% during 2027-2032.
Note: Market numbers in this report are based on Mordor Intelligence's proprietary estimation framework, which combines nine months of actuals with Q4 projections for base year 2026.
Market Trends and Insights
Drivers Impact Analysis of Spa Market*
| Driver | (~) % Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
|---|---|---|---|
| Rising Wellness Tourism And Experiential Travel | +3.4% | Saudi Arabia's resort destinations | Medium term (2-4 years) |
| Increasing Disposable Income In Emerging Markets | +2.3% | China and India | Medium term (2-4 years) |
| Aging Population Driving Health-Focused Spa Visits | +1.2% | Europe and North America | Long term (≥ 4 years) |
| Corporate Wellness Program Integration | +0.7% | The United States | Medium term (2-4 years) |
| AI-Powered Hyper-Personalized Treatment Protocols | +0.4% | Orlando and Miami Beach | Long term (≥ 4 years) |
| Subscription-Based Urban Micro-Spa Models | +0.3% | Charlotte's urban spa catchments | Short term (≤ 2 years) |
| Source: Mordor Intelligence | |||
Rising Wellness Tourism And Experiential Travel
Wellness-oriented travel gives resort operators a reason to build the treatment experience into the destination itself. Four Seasons Resort and Residences AMAALA at Triple Bay opened in Saudi Arabia on June 15, 2026, with a 2,095-square-meter HYLIAA Wellness & Spa. Locating a substantial spa within the resort lets an operator connect treatment time with the guest's stay instead of relying solely on separate spa trips. The opportunity depends on leaving enough time within the stay for a sequence of treatments, so the service design must fit the visit's duration. A resort can then grow spa revenue through deeper use within one journey, reducing its dependence on attracting another traveler for every additional treatment.
Increasing Disposable Income In Emerging Markets
Real income growth can broaden the customer base for treatments without forcing operators to depend entirely on luxury travel. China’s nationwide per capita disposable income increased 5.3% nominally and 4.4% in real terms year over year in the first 3 quarters of 2026.[1] In May 2025, Ode Spa announced a new Vadodara outlet offering premium massage therapies to residents and travelers. An outlet that serves residents as well as travelers can build repeat local visits instead of relying on tourist traffic alone. Pricing determines whether that mixed audience is offered occasional premium treatments or sessions affordable enough for regular local use.
Aging Population Driving Health-Focused Spa Visits
A larger older customer base can add health-focused spa visits when sessions fit guests' mobility and endurance. An operator targeting these guests can offer shorter appointments, accessible treatment space, and assistance suited to each guest's pace. Where a standard session would be too demanding, those adaptations can make a visit feasible and add demand from the growing older customer base. Health-focused positioning works best when the offer separates a relaxation service from a medical treatment, so it does not imply a clinical result. Session length and treatment-room access therefore determine how many of these visits an operator can accommodate within a guest's endurance limit.
Corporate Wellness Program Integration
Employer-funded spa access can change the unit of demand from an individual leisure purchase to a recurring employee benefit. For a day spa, the commercial value would come from employees redeeming a treatment entitlement, rather than the employer's overall wellness budget. A recurring allowance can make an additional appointment affordable without requiring the spa to lower its public treatment price. Such an arrangement would also give an employer a defined service to fund, instead of an unrestricted promise of well-being. Redemption rates among eligible employees, not the number of employers that sign up, determine how much of a funded allowance reaches spa revenue.
Restraints Impact Analysis of Spa Market*
| Restraint | (~) % Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
|---|---|---|---|
| High Operating And Labor Costs | -0.9% | The United States | Short term (≤ 2 years) |
| Seasonality Of Demand In Resort Locations | -0.5% | Thailand's resort destinations | Short term (≤ 2 years) |
| Shortage Of Certified Therapists In Key Regions | -0.4% | The United Kingdom | Medium term (2-4 years) |
| Data-Privacy Concerns Around Biometric Diagnostics | -0.2% | The United Kingdom | Medium term (2-4 years) |
| Source: Mordor Intelligence | |||
High Operating And Labor Costs
The operating-cost challenge is the service capacity that must be paid for to deliver an additional appointment. The 2026 ISPA U.S. Spa Industry Study said labor constraints were reshaping U.S. spa operations in 2025, with full-time staffing unchanged. With full-time staffing unchanged, extending opening hours requires additional staff coverage or a redistribution of existing hours, which limits the appointments an operator can offer. Staffing coverage for a broad treatment menu therefore affects both operating costs and the services available to sell. Higher treatment prices can cover additional expense, but may weaken the affordability of routine visits. The remaining constraint is the cost of adding reliably staffed appointments, which physical room expansion alone cannot resolve.
Seasonality Of Demand In Resort Locations
Seasonal visitor demand limits how confidently resort-linked spas can turn peak-period treatment demand into year-round earnings. In its 2025 management discussion, Siam Wellness Group said its spa business in Thailand typically peaks in high season, while low season may temporarily slow operating results. For a resort operator exposed to that pattern, peak-period demand alone provides an incomplete basis for adding treatment rooms. The investment decision depends on how many weeks of high-season demand the added capacity can serve. Capacity sized for that peak may stand underused when low season slows results, leaving fewer revenue-generating appointments over which to recover the investment.
*Our forecasts treat driver/restraint impacts as directional, not additive. The impact forecasts reflect baseline growth, mix effects, and variable interactions.
Spa Market Segment Analysis
By Service Type:
Massage Leads as Medical Treatments ExpandMassage and body treatments accounted for a 36.95% share of the spa market size in 2026. In March 2026, Massage Envy reported that its independently owned U.S. franchise locations had collectively delivered over 235 million services across skin-care and body-care offerings. Massage Envy's franchised locations reported record growth in Hot Stone services during 2025. That massage-specific result shows demand for a service combining relaxation with deeper pressure. Franchise operators can build around that familiar category and vary the session, preserving a recognizable treatment offer as the network reaches different local customer bases.
Medical and medi-spa treatments are forecast to be the fastest-growing segment, with a CAGR of 9.12% during 2027-2032. In December 2025, VIO Med Spa's franchise network opened 4 U.S. medical-spa locations, operated by local franchise owners. In its January 2026 announcement, VIO described clinical services delivered under licensed medical director oversight. Local franchise operation and licensed medical director oversight make staffing and clinical governance part of each facility's treatment-delivery model. Extending that model means reproducing the service-delivery structure across locations, rather than treating each new site as floor space alone.


By Facility Type:
Local Membership and Clinical Networks Support ExpansionDay and club spas represented a 43.3% spa market share in 2026. Hand & Stone's franchise network opened 13 massage and facial spas in Q4 2025. At its Holbrook, New York, location, owned and operated by franchisee Patrick Martone, nearly 550 founding members had enrolled before its November 2025 opening. The network openings show replication of the facility model, while the Holbrook enrollment shows a local audience being assembled before service begins. Founding-member enrollment can move customer acquisition ahead of a site's first treatment, so a launch depends less on being discovered after opening.
Medical spas are forecast to be the fastest-growing segment, with a CAGR of 12.63% during 2027-2032. In January 2026, OrangeTwist acquired 6 additional med spa locations in Colorado and Nevada, expanding its footprint to 24 locations across 6 U.S. states. The transaction extended the acquirer's operating footprint through existing clinics, making network control the immediate mechanism of its expansion rather than new facility construction. Integrating service delivery across acquired clinics becomes the execution task that further acquisitions alone cannot resolve for a multistate operator.
By Booking Channel:
In-Person Service Supports a Growing Mobile ChannelOn-site and walk-in bookings were the largest segment, representing 70.83% of spa service revenue in 2026. For a guest already at a property, an in-person conversation can resolve the choice of treatment, practitioner, or available time within the same visit. The channel's commercial value lies in turning immediate interest into a deliverable appointment, rather than requiring the customer to commit before arriving. Operators can also match a guest's request to capacity that is available at that moment, although the value disappears if the suitable slot cannot be offered. At peak hours, a spa without a suitable opening risks losing a walk-in sale that advance online booking could move to another time.
Online and mobile app bookings are forecast to be the fastest-growing segment, with a CAGR of 8.21% during 2027-2032. Trybe's 2025 data from a global sample of 345 spas found that 76% of bookings made outside traditional office hours were made on a smartphone or tablet. That out-of-hours pattern makes the mobile interface commercially relevant at a time when a guest may be ready to book without speaking to the spa. A clear path from treatment selection to an available appointment can capture that interest, provided the digital offer reflects the services the operator can deliver. A spa with a working mobile booking path can capture after-hours decisions without extending the hours in which its staff deliver treatments.
By End User:
Individual Needs and Shared Experiences Shape the OfferWomen were the largest segment, accounting for a 55.84% share of spa service revenue in 2026. Their majority share gives operators a reason to organize the core service menu around this customer group's treatment choices. With women contributing the majority of revenue, operators have a commercial reason to offer relaxation, skin, and body services in session lengths that support repeat visits. Because women account for most spa service revenue, a menu or pricing change that weakens their repeat bookings puts more of an operator's income at risk than a change aimed at any smaller customer group.
Family and group customers form the fastest-growing segment, forecast at a CAGR of 8.72% during 2027-2032. By October 2025, Six Senses Con Dao in Vietnam had developed parent-and-child massage and group sound baths after guests returned with children following earlier wellness and nature stays. The sequence matters commercially because the property adapted the experience to a returning family's needs, creating a shared service format rather than treating every guest separately. The opportunity lies in including more participants within a visit while keeping the service suitable for the group, rather than assuming that every participant requires the same treatment. A parent-and-child or group format lets the spa sell a shared experience within a family stay, rather than relying only on separate individual appointments.
Geography Analysis
Europe Spa Market
Europe was the largest region, accounting for a 35.73% spa market share in 2026. By May 2025, Chalet Hotel Schönegg had opened a 400-square-meter spa in Zermatt, Switzerland, adding dedicated wellness space to an established, family-run 4-star superior hotel. A hotel that adds a spa can sell treatments to guests already staying at the property, which ties treatment demand to an existing accommodation channel.
Asia-Pacific Spa Market
Asia-Pacific is forecast to be the fastest-growing region, with a CAGR of 9.15% during 2027-2032. Banyan Tree Holdings (operating as Banyan Group) opened 2 spa outlets in Greater China and one each in Singapore and Vietnam in 2025. In Sri Lanka, Kahanda Kanda opened the KK Spa on January 4, 2026, with 3 treatment rooms, 2 consultation studios, and an open-air yoga shala. The openings span a multi-country hospitality group and a boutique retreat, demonstrating different routes to additional regional service capacity.
In North America, ISPA reported 191 million spa visits in the United States in 2025, up 1.8% from 2024.[3] In South America, La Prensa reported that Uruguay's Spa Thermal Daymán offered thermal-water treatments with rheumatology, rehabilitation, and preventive medicine for local patients and international tourists in 2025. Brazil's 2026 tourism outlook also positioned spas and thermal waters as part of wellness travel. In Middle East & Africa, Four Seasons Hotel Rabat at Kasr Al Bahr opened a spa in Morocco on November 17, 2025, with 10 treatment rooms and a traditional hammam. Uruguay's thermal site offered treatments to local patients and international tourists, while Morocco's opening added a hotel spa, distinguishing specific routes to customers within the broader category measured by U.S. spa visits.

Regulatory Framework and Outlook
The comparison covers selected jurisdictions from the perspective of a nonmedical spa operator entering and running a treatment facility. Establishment licensing makes the treatment scope and administering authority more consequential than the spa label alone. Florida and Haringey provide the U.S. and UK examples, while the other columns cover the stated national categories of bathing, beauty, or relaxation centers.
Regulatory Table of Spa Market
| Decision factor | United States | Brazil | China | United Kingdom | Saudi Arabia |
|---|---|---|---|---|---|
| Primary authority | Florida Department of Health and Board of Massage Therapy | State, district and municipal sanitary-surveillance agencies | City- and county-level disease-control departments | Haringey Council | Ministry of Municipalities and Housing |
| Key instruments or direction | Florida Statutes §480.043 | Anvisa's September 2026 notice on aesthetics and beauty services | Public Place Health Management Regulations; hygiene-standard revision under review | London Local Authorities Act 1991 and local special-treatment conditions | Relaxation and body-care center requirements and worker health certificates |
| Commercial effect | Establishment license and facility, safety and sanitation rules | Local sanitary licensing and inspection continue during guidance reassessment | Listed bathing and beauty premises need a health permit before opening | Licensee or written nominee must be in charge on the premises whenever licensed massage or sauna premises are open | Balady licensing, tool sterilization after each use and worker certification |
| Current policy attractiveness | Medium | Medium | Medium | Medium | Medium |
| Future direction of policy attractiveness | No change | No change | No change | No change | No change |
| Source: Mordor Intelligence | |||||
Florida's establishment license and Haringey's requirement for the licensee or a written nominee to be in charge on the premises support Medium ratings and continuity judgments based on defined operating duties. China's operative preopening health-permit duty supports Medium and No change while the National Disease Control and Prevention Administration's June 15, 2026 mandatory public-place hygiene draft was under review and unpublished on October 20, 2026, with implementation planned 6 months after publication. Brazil's Medium and No change judgments reflect Anvisa's September 23, 2026 confirmation that local sanitary licensing continues while its technical guidance is reassessed. Saudi relaxation-center workers need annual certificates following medical exams at accredited authorities and health education tests in covered cities and professions, making staffing compliance recurring and supporting Medium and No change judgments.
Value Chain Stages
The value chain compares professional treatment inputs, appointment coordination, and the delivery of spa services to guests. Product suppliers earn from the materials and equipment used to deliver treatments, while software providers support the coordination of service capacity. Spa operators capture the guest-facing service sale, giving them direct exposure to whether an appointment can actually be delivered. These stages are complementary, but their revenue mechanisms and operational risks differ.
Value Chain Analysis Table of Spa Market
| Primary activity | Key participants | Value capture | Bottleneck | Resilience response |
|---|---|---|---|---|
| Supply treatment products and equipment | Treatment-product suppliers such as Biossentials; product and equipment suppliers such as Universal Companies | Professional product and equipment sales | Replenishment of treatment-specific consumables | Qualify suitable alternatives and hold treatment stock |
| Coordinate bookings and service capacity | Spa software providers such as Zenoti and Agilysys (Book4Time) | Software revenue | Risk of room and therapist scheduling conflicts | Reconcile appointments with available rooms and practitioners |
| Deliver spa services | Spa operators such as OneSpaWorld and The Ritz-Carlton Orlando, Grande Lakes | Guest treatment and service revenue | Dependence on usable treatment space and staff | Phase service availability around deliverable capacity |
| Source: Mordor Intelligence | ||||
Zenoti's therapist-aware appointment scheduling ties the booking stage to the staffed capacity that limits what an operator can sell. Biossentials combines professional products with training and support for luxury spas in Asia and the Middle East, illustrating how input supply can extend into treatment capability. That creates a route for upstream suppliers to deepen their role without owning the spa, while the operator retains the direct revenue from the treatment.
Competitive Landscape
The dispersed field includes hotel-linked operators Four Seasons Hotels & Resorts and Marriott International, whose spas connect treatment services with a broader hospitality setting. Mandarin Oriental Hotel Group also serves hotel spa guests, while OneSpaWorld Holdings Limited (OneSpaWorld) operates across cruise ships and destination resorts. Hilton Worldwide (Eforea) adds another hotel-based wellness proposition through its resort spas. In fiscal 2025, OneSpaWorld’s consolidated revenue rose 7% to USD 961 million as maritime gains from new ships, guest spend, and revenue days offset lower destination-resort revenue.[2] That divergence makes the choice of guest channel commercially significant, because cruise and resort exposure can produce different operating results within the same company.
Physical spa investment can give a resort a more distinctive treatment setting while exposing it to the economics of one destination. In November 2025, Four Seasons Resort Mauritius at Anahita reopened Oseyan Spa with renovated treatment rooms, a thermal suite, and a new overwater Royal Spa Suite. Combining heat, water, private treatment space, and the overwater setting creates several reasons for a guest to choose an extended spa experience at that property. A competing resort would need comparable physical facilities to match the thermal suite and overwater treatment setting.
More specialized service portfolios introduce another competitive route beyond investment in land-based facilities. OneSpaWorld had rolled out Medi-Spa to 153 vessels by December 31, 2025. A vessel-based rollout can distribute services through the operator's existing cruise-partner channel, giving expansion a route beyond constructing another destination spa. That scale makes consistent delivery across locations a more consequential differentiator than simply adding a Medi-Spa name to a treatment menu. Challengers face a choice between specializing in service capability and recreating the distribution network, because guest access and treatment delivery are separate requirements for matching this model.
Spa Industry Leaders
-
Four Seasons Hotels & Resorts
-
Marriott International (Heavenly Spa, Remede)
-
Mandarin Oriental Hotel Group
-
OneSpaWorld Holdings Limited (OneSpaWorld)
-
Hilton Worldwide (Eforea)
- *Disclaimer: Major Players sorted in no particular order

Spa Market Companies Covered in this Report
- Four Seasons Hotels & Resorts
- Marriott International (Heavenly Spa, Remede)
- Mandarin Oriental Hotel Group
- Hilton Worldwide (Eforea)
- OneSpaWorld Holdings Limited (OneSpaWorld)
- Minor International (Anantara Spa)
- Accor (Fairmont & Sofitel Spas)
- Hyatt Hotels Corporation (Miraval, Exhale)
- Six Senses Hotels Resorts Spas
- Banyan Tree Holdings
- Canyon Ranch
- Champneys Health Resorts
- Lanserhof Group
- The Red Door by Elizabeth Arden
- Marriott International (Spa by JW)
- L'Occitane en Provence Spas
- Hand & Stone Massage and Facial Spa
- Massage Envy
- Planet Beach Spray & Spa
- Hot Springs Resort & Spa
- Shangri-La Hotels & Resorts (Chi Spas)
- ESPA International
- COMO Shambhala
- Nuffield Health Wellbeing & Beauty
Key Opportunities for Market Participants
The opportunities compare treatment revenue from thermal destinations, urban hotel spas, and service continuity during renovations. A spa-hotel development links a future treatment offer to a destination stay, while an urban hotel can fit spa services around a shorter visit. Those settings favor different service designs, from bathing-linked treatments to appointments that complement the hotel experience. Renovation adds a separate commercial need, keeping a focused treatment offer available while the main spa changes.
Market Opportunities Table of Spa Market
| Opportunity | Why now | Buyer / lead segment | Recommended play | Main barrier | Likely beneficiaries |
|---|---|---|---|---|---|
| Thermal destination treatment visits | June 2026 Fernie groundbreaking; fall 2027 planned opening | Thermal destination guests in Western Canada | Combine bathing access with separately identifiable treatment services | Treatment revenue depends on facility delivery | Everwild, owned and operated by Basecamp Resorts |
| Urban hotel spa experiences | Waldorf Astoria Kuala Lumpur scheduled its spa and wellness opening for October 30, 2026 | Urban luxury hotel spa guests in Malaysia | Offer treatment appointments that complement the hotel stay | Scheduled facilities must become operational before visits can be served | Hotel spa operators such as Waldorf Astoria Kuala Lumpur |
| Treatment continuity through renovation | Bellagio's February 2026 remodel announcement provided for select treatments in alternative spaces | Guests of resort spas undertaking a remodel | Retain a focused treatment menu in suitable replacement space | Temporary service scope limits the offer | Resort spa operators such as MGM Resorts International |
| Source: Mordor Intelligence | |||||
Treatment continuity during renovation is the central opening for operators seeking sales during construction, while new spa capacity in Fernie and Kuala Lumpur depends on planned openings. Bellagio's February 2026 announcement provided for select treatments on the fourth floor of the Spa Tower and through in-room services during the remodel of its 55,000-square-foot spa, ahead of a planned November 2026 debut. An operator that plans replacement space before closing its main spa can keep a treatment booking path open through construction.
Recent Industry Developments in Spa Market
- Oct 2026: Hilton announced that Waldorf Astoria Kuala Lumpur's wellness facilities, including a spa with 7 treatment rooms, were scheduled to open on October 30, 2026, adding a planned urban hotel spa offer in Malaysia.
- Sep 2026: Anvisa temporarily suspended its 2024 guidance on aesthetics and beauty services during reassessment with a working group, while Brazil's applicable sanitary rules and local licensing duties continued.
- Aug 2026: Rosewood AMAALA opened in Triple Bay, Saudi Arabia, with a 2,100-square-meter Asaya well-being facility containing 6 treatment rooms and a double suite.
Spa Market Report Scope and Research Methodology
Market Definition and Coverage
The global spa market measures annual customer spending on services delivered by spa facilities worldwide. It counts spa operator revenue from those purchases, classified by service, facility, booking channel, customer group and region.
Scope exclusions: Separately sold spa retail products, lodging, cruise fares and other travel packages, standalone salon or barber services outside spa facilities, and travel transport sold apart from spa treatments are excluded.
Segments Covered in This Report
- By Service Type
- Massage and Body Treatments
- Facials and Skin Care
- Beauty and Grooming (Nails, Hair)
- Hydrotherapy and Thermal/Mineral Springs
- Medical / Medi-Spa Treatments
- Others (Aromatherapy, Reiki, etc.)
- By Facility Type
- Day / Club Spas
- Destination and Resort Spas
- Hotel / Cruise-Ship Spas
- Medical Spas
- Thermal and Mineral Spring Facilities
- By Booking Channel
- On-site / Walk-in
- Online and Mobile App Bookings
- By End User
- Women
- Men
- Couples
- Family / Group
- By Geography
- North America
- Canada
- United States
- Mexico
- South America
- Brazil
- Peru
- Chile
- Argentina
- Rest of South America
- Asia-Pacific
- India
- China
- Japan
- Australia
- South Korea
- South East Asia (Singapore, Malaysia, Thailand, Indonesia, Vietnam, Philippines)
- Rest of Asia-Pacific
- Europe
- United Kingdom
- Germany
- France
- Spain
- Italy
- BENELUX (Belgium, Netherlands, Luxembourg)
- NORDICS (Denmark, Finland, Iceland, Norway, Sweden)
- Russia
- Rest of Europe
- Middle East & Africa
- United Arab Emirates
- Saudi Arabia
- South Africa
- Nigeria
- Rest of Middle East & Africa
- North America
Data Sources, Market Sizing, and Validation
Desk Research
The analyst can use sources such as the International Spa Association's recurring U.S. industry study for revenue, visits, locations and revenue per visit, the Global Wellness Institute's spa industry series for historical global and country context, its 2025 monitor for regional spa revenue and establishment patterns, and the World Bank's household consumption indicators to frame demand and compare markets. These sources help anchor activity, category definitions and demand conditions, while tourism and household spending remain context measures rather than spa revenue.
Company filings, investor presentations, annual reports and reputable business press can clarify operator footprints, service offerings, expansion plans and disclosed sales trends, with those facts used as cross-checks rather than substitutes for market totals. These named sources are illustrative and not exhaustive, and further sources inform collection, validation and clarification.
Primary Interviews and Surveys
Interviews and structured surveys would include spa operators across day and club, resort, hotel and cruise, medical, and thermal facilities, with commercial, operating, and finance leaders able to explain service revenue, capacity and customer demand. Respondents would be asked to check secondary findings on service mix, facility economics, channel use and regional conditions, while estimates that cannot be reconciled would be isolated for further checking against independent evidence. Where evidence remains sparse, the analyst would document the range of supported inputs and triangulate operator statements with published activity and financial indicators before selecting assumptions.
Distribution of primary research fieldwork respondents
| Company type | Respondent position | Region |
|---|---|---|
| Top tier: 40% | CXOs: 15% | APAC: 40% |
| Mid tier: 45% | Functional/Unit leaders: 35% | EMEA: 35% |
| Smaller Players: 15% | Managers: 50% | Americas: 25% |
Market-Sizing & Forecasting
Global annual spa-service revenue is estimated from the top down, and selected totals are then checked with operator and channel evidence such as sampled service price multiplied by service volume and facility revenue roll-ups. Core indicators would include spa visits and revenue per visit, facility counts and capacity, household spending and income, tourism activity for destination-linked facilities, and labor availability and cost. These help distinguish demand growth from prices, mix and the ability to serve appointments. Revenue by service, facility, booking channel, customer group and region would be built from published splits where available and adjusted using evidence on relative facility presence, customer use and growth, with regional totals reconciled to the global estimate. A multivariate regression can relate historical market revenue to these demand and capacity indicators, while scenario analysis can address sparse or conflicting country data. Missing inputs would be estimated from the nearest supported regional or facility evidence and recorded for review. Primary experts would check whether variable-level forecasts reflect actual spa operating conditions and whether the selective bottom-up checks fit the top-down totals.
Data Validation & Update Cycle
Analysts would triangulate operator disclosures, association indicators, tourism and household data, and published market estimates, then investigate outliers, inconsistent growth rates and large differences between independent signals before sign-off. A second analyst review would check source dates, definitions, units, arithmetic, segment totals and regional reconciliation, with re-contact triggered when an operator clarification changes a material input or when conflicting evidence cannot be resolved from records. The model would be refreshed annually, updated between cycles after material events such as major regulatory or travel disruptions, and given a fresh source and calculation review immediately before delivery.
Mordor Intelligence's Spa Market Size Measured Against Other Published Estimates
Published estimates can differ in the transactions and products they count and the inputs used to model demand. The global spa market measures annual customer spending on services delivered by spa facilities worldwide.
Key Gap Drivers include the study's defined coverage and market-specific modeling choices. Core indicators would include spa visits and revenue per visit, facility counts and capacity, household spending and income, tourism activity for destination-linked facilities, and labor availability and cost.
Benchmark comparison
| Source | Market Size | Gaps in Research Methodology |
|---|---|---|
| Mordor Intelligence | USD 174.6 B (2027) | |
| Global Consultancy A | USD 102.3 B (2025) | At its 2025 base, this estimate is 41.4% below this report's 2027 value of USD 174.6 B, 2 years later. The 2025 base year precedes the report's 2027 measurement, so intervening market growth can contribute to the lower displayed value. |
| Global Consultancy B | USD 67.6 B (2025) | At its 2025 base, this estimate is 61.3% below this report's 2027 value of USD 174.6 B, 2 years later. The 2025 base year precedes the report's 2027 measurement, so intervening market growth can contribute to the lower displayed value. |
Mordor Intelligence's analysts would triangulate operator disclosures, association indicators, tourism and household data, and published market estimates, then investigate outliers, inconsistent growth rates and large differences between independent signals before sign-off.
Key Questions Answered in the Report
What is the spa market size and growth outlook?
The industry is estimated at USD 174.6 billion in 2027 and forecast to reach USD 236.8 billion by 2032, at a CAGR of 6.28% during 2027-2032.
What is driving demand for spa services?
Wellness travel and greater spending capacity support demand. China's nationwide per capita disposable income rose 5.3% nominally and 4.4% in real terms year over year in the first 3 quarters of 2026.
Which spa service segment is the largest?
Massage and body treatments led with 36.95% of spa service revenue in 2026. Medical and medi-spa treatments are forecast to grow fastest at a CAGR of 9.12% during 2027-2032.
Which companies are prominent spa operators?
Major players include Four Seasons Hotels & Resorts, Marriott International, Mandarin Oriental Hotel Group, OneSpaWorld Holdings Limited (OneSpaWorld), and Hilton Worldwide (Eforea).
What is a key operating challenge for spa businesses?
Adding staffed appointments can be difficult when labor is constrained. The 2026 ISPA U.S. Spa Industry Study said labor constraints were reshaping U.S. spa operations in 2025, with full-time staffing unchanged.
Which region leads spa services and which is growing fastest?
Europe led with 35.73% of spa service revenue in 2026. Asia-Pacific is forecast to grow fastest at a CAGR of 9.15% during 2027-2032.