
South Korea Dairy Alternatives Market Size and Share
Market Overview
| Study Period | 2021 - 2031 |
|---|---|
| Forecast Data Period | 2026 - 2031 |
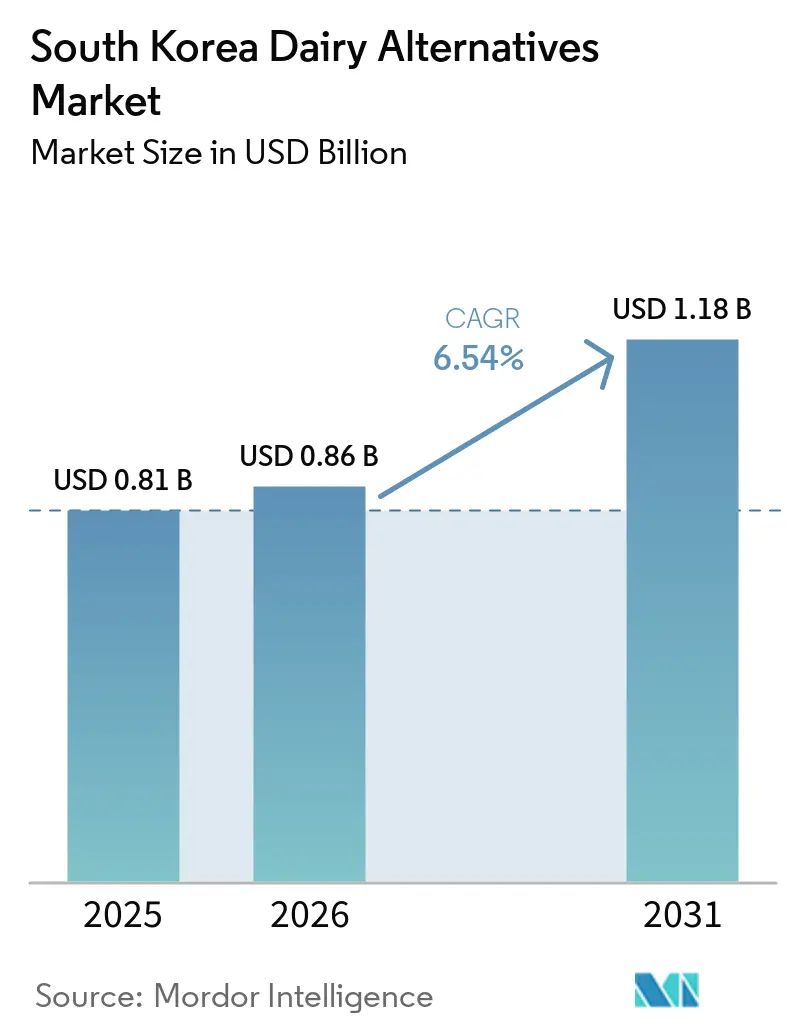
| Base Year Market Size (2025) | USD 0.81 Billion |
| Market Size (2026) | USD 0.86 Billion |
| Market Size (2031) | USD 1.18 Billion |
| Growth Rate (2026 - 2031) | 6.54 % |
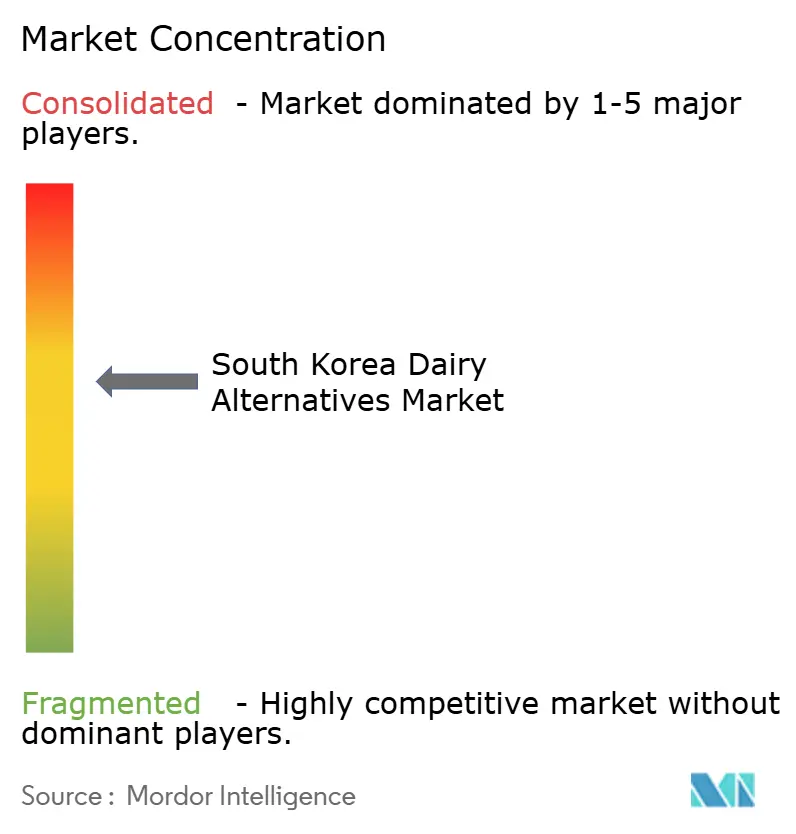
| Market Concentration | Medium |
Major Players *Disclaimer: Major Players sorted in no particular order Image © Mordor Intelligence. Reuse requires attribution under CC BY 4.0. | |
South Korea Dairy Alternatives Market Analysis by Mordor Intelligence
The South Korea dairy alternatives market size was valued at USD 0.81 billion in 2025 and is expected to reach USD 0.86 billion in 2026 and USD 1.18 billion by 2031, growing at a CAGR of 6.54% over 2026-2031. Lower white-milk consumption has created room for beverages that address changing nutrition and lifestyle preferences, while conventional milk faces greater price competition following tariff changes in 2026. The South Korea dairy alternatives market is led by products that match everyday consumption habits rather than occasional specialty use. Producers are responding with cleaner ingredient lists, domestic raw-material narratives, and formats suited to retail and cafés. The South Korea dairy alternatives market also benefits from café-led trial, which can translate into repeat purchases for home consumption. Input availability, taste, and the premium price of plant-based products remain practical limits on wider adoption.
Key Report Takeaways
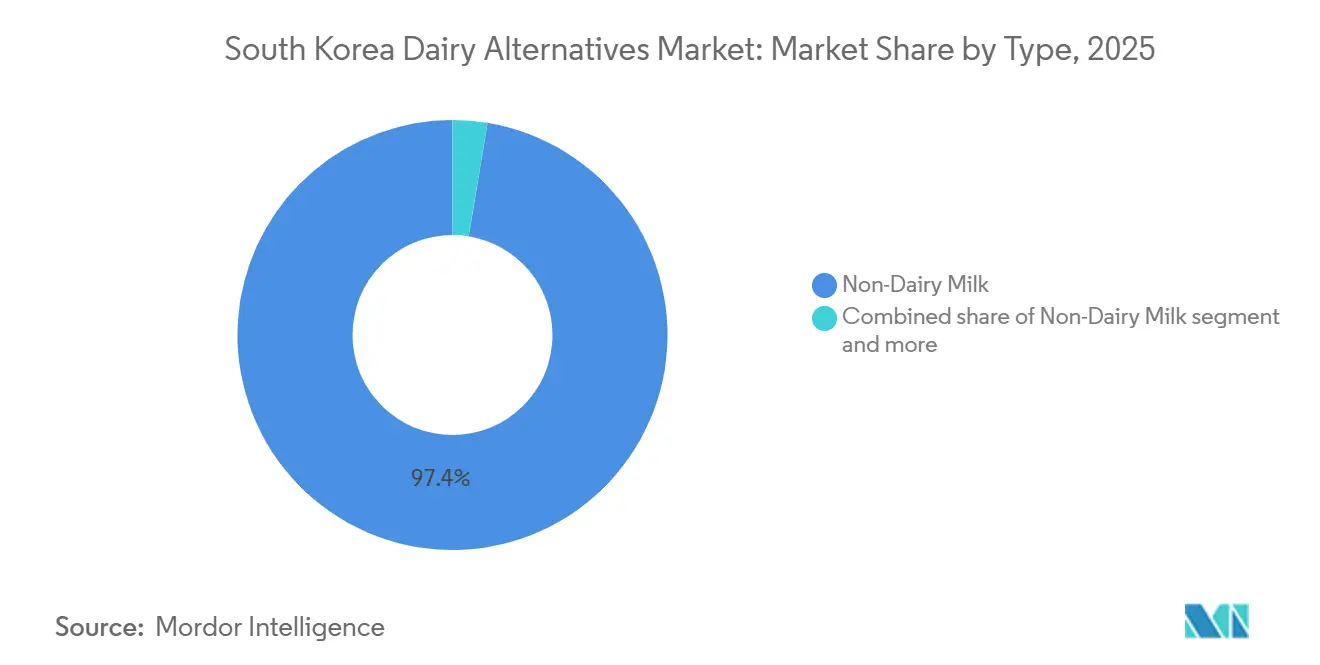
- By type, Non-Dairy Milk held 97.46% of the South Korea dairy alternatives market share in 2025, while Non-Dairy Milk recorded the highest projected CAGR at 6.86% through 2031.
- By flavor, Unflavored held 41.04% of the South Korea dairy alternatives market share in 2025, while Flavored recorded the highest projected CAGR at 7.45% through 2031.
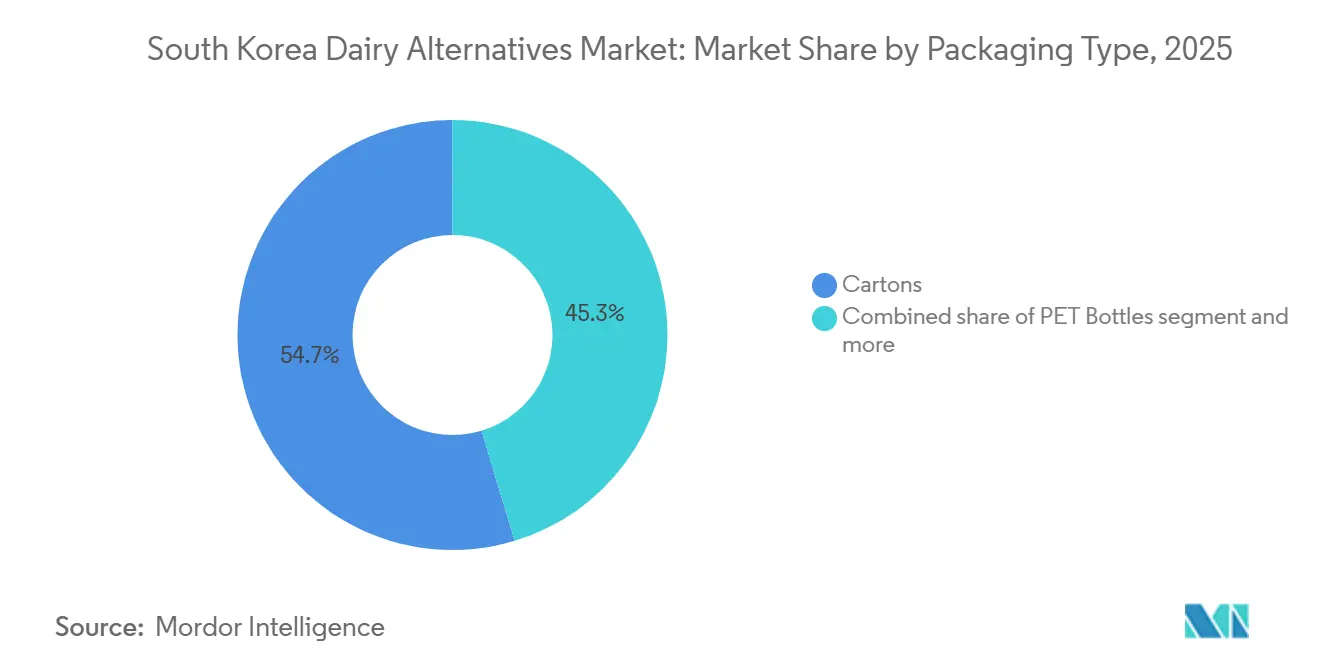
- By packaging type, Cartons held 54.67% of the South Korea dairy alternatives market share in 2025, while PET Bottles recorded the highest projected CAGR at 7.23% through 2031.
- By distribution channel, Off-Trade held 96.88% of the South Korea dairy alternatives market share in 2025, while On-Trade recorded the highest projected CAGR at 6.87% through 2031.
Market Trends and Insights
Drivers Impact Analysis of South Korea Dairy Alternatives Market*
| Driver | (~) % Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
|---|---|---|---|
| Growing Interest in Health and Wellness | +1.8% | National, with concentration in Seoul and Gyeonggi-do | Medium term (2-4 years) |
| Shift Toward Plant-Forward Diets | +1.3% | National, led by urban millennials and Gen Z in Seoul, Busan, and Incheon | Long term (≥ 4 years) |
| Government and Industry Support for Plant-Based Innovation | +0.7% | National, with innovation hubs in Jeonbuk Province and Seoul | Medium term (2-4 years) |
| Strong Café and Coffee Culture | +1.2% | National, concentrated in Seoul, Gyeonggi-do, and major urban centers | Short term (≤ 2 years) |
| Advancements in Food Technology | +0.6% | National, with early gains in precision fermentation clusters | Long term (≥ 4 years) |
| Rising Concerns Over Animal Welfare | +0.4% | National, more prominent among urban and younger consumers | Long term (≥ 4 years) |
| Source: Mordor Intelligence | |||
Growing Interest in Health and Wellness
Digestive comfort remains an important reason for Korean consumers to consider dairy alternatives. Plant-based products can address lactose-related concerns without requiring consumers to give up familiar beverage occasions. Taste remains the leading purchase consideration for plant-based food in South Korea, with nutrition and labeling close behind. This combination favors products that offer both acceptable flavor and a clear nutritional proposition. Producers in the South Korea dairy alternatives market are therefore prioritizing protein, probiotics, and simpler formulations. These features can broaden demand beyond consumers who actively identify with plant-based diets.
Shift Toward Plant-Forward Diets
Plant-forward eating received greater public attention during the 2025 boknal season, when campaigns and public events highlighted alternatives to traditional meat-heavy meals. The change matters because boknal has a strong cultural association with conventional animal-based dishes. Plant-based meal guidance was also present across all 17 metropolitan and provincial education offices in 2024. The guidance recommended plant-based school meals 1 to 2 times each month. Regular exposure in schools can make these foods more familiar across regions. This supports a longer-term consumer base for the South Korea dairy alternatives market.
Government and Industry Support for Plant-Based Innovation
South Korea enacted the Food Tech Industry Promotion Act in December 2024. The legislation established a dedicated policy basis for food-technology clusters, research support centers, and regulatory improvement applications. A plant-based food research support center was scheduled to open in 2026. Jeonbuk Province and the Netherlands Embassy in Seoul also signed a 2025 memorandum to support food-protein innovation. These actions can improve access to research networks and clarify pathways for innovation. They also support the South Korea dairy alternatives market by encouraging product development beyond established soy beverages.
Strong Café and Coffee Culture
Cafés introduce consumers to oat and almond drinks in familiar espresso-based beverages. This setting reduces the perceived risk of trying a new product because the beverage format is already well understood. Maeil Co. Ltd's Amazing Haute Barista oat milk was available in 7,600 cafés nationwide in 2024 and reported 38% sales growth that year. The high density of cafés in South Korea supports the premium positioning of plant-based milks, while e-commerce platforms enable consumers to replicate café-style beverages at home. For example, according to the Ministry of Food and Drug Safety, over 966,200 restaurants were operating in South Korea [1]. This extensive foodservice ecosystem, particularly the prevalence of Cafés, plays a critical role in driving demand for dairy alternatives through high-volume beverage service and plant-based menu adaptations.
Restraints Impact Analysis of South Korea Dairy Alternatives Market*
| Restraint | (~) % Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
|---|---|---|---|
| Taste and Texture Limitations | -0.8% | National, particularly affecting repeat purchase among flexitarians | Short term (≤ 2 years) |
| Perception of Plant-Based Products as Highly Processed | -0.6% | National, concentrated among older consumers and health-focused consumers | Medium term (2-4 years) |
| Limited Availability of Certain Varieties | -0.4% | Regional, more acute outside Seoul and Gyeonggi-do | Short term (≤ 2 years) |
| Supply Chain Vulnerabilities | -0.5% | National, with exposure to global commodity-price volatility | Medium term (2-4 years) |
| Source: Mordor Intelligence | |||
Taste and Texture Limitations
Consumer acceptance depends on whether a plant-based beverage performs well in routine drinking and coffee use. Research on plant-based milk found that perceptions of artificiality and food neophobia can reduce willingness to adopt these products. This issue is especially relevant when consumers compare products directly with dairy milk. A poor first experience can limit repeat purchase even if the product has favorable nutrition information. The South Korea dairy alternatives market therefore has a strong incentive to improve flavor, mouthfeel, and functionality. Simpler formulations may also reduce the concern that dairy alternatives are heavily processed. These changes are important for attracting flexitarian consumers who do not have a firm dietary commitment to plant-based products.
Perception of Plant-Based Products as Highly Processed
The perception of plant-based products as highly processed is a limiting factor for the South Korea dairy alternatives market. Consumers express concerns about additives, stabilizers, emulsifiers, and fortificants in products such as soy, almond, and oat milk, often viewing them as artificial despite clean-label claims. Many prefer natural, traditional dairy products or unprocessed ferments like doenjang, driven by health-conscious skepticism toward ultra-processed foods associated with metabolic risks. This perception is particularly strong among older demographics and rural populations, such as those in Jeolla, who value minimal processing. As a result, the adoption of non-dairy yogurts and cheeses, which rely on gums for texture, remains limited. However, urban millennials are increasingly driving demand for transparency, favoring products with shorter ingredient lists and enhanced natural formulations.
*Our forecasts treat driver/restraint impacts as directional, not additive. The impact forecasts reflect baseline growth, mix effects, and variable interactions.
South Korea Dairy Alternatives Market Segment Analysis
By Type:
Non-Dairy Milk Anchors Demand While Specialty Categories Build DifferentiationNon-dairy milk accounted for 97.46% of the South Korea dairy alternatives market share in 2025. Soy milk remains central because it is already familiar to many consumers as an everyday beverage. Oat milk has gained attention through café use, while almond milk is positioned more often in premium offerings. The South Korea dairy alternatives market size for non-dairy milk is supported by retail replenishment rather than one-time experimentation. Pulmuone’s Premium Grade Domestic Soymilk product used 96.37% whole-ground domestic soybean juice and 3 ingredients.
Non-dairy milk is also the fastest-growing type, with a projected CAGR of 6.86% through 2031. Its growth from an established base shows that product renovation remains possible in the largest category. Maeil Co. Ltd launched Sangha Farm Bean Water Soymilk in August 2026 with black soybean, mugwort, and red bean varieties made from domestic agricultural ingredients. These offerings show how local flavors can create differentiation within a familiar format. Non-dairy cheese, desserts, and yogurt remain smaller categories. They provide a route for suppliers to address uses where functional performance, indulgence, or dairy-like texture can matter more than daily beverage habits.

By Flavor:
Unflavored Leads While Flavored Products Attract New OccasionsUnflavored products held 41.04% of the South Korea dairy alternatives market share in 2025. Plain soy milk remains an established routine purchase, and neutral-flavor oat milk suits coffee preparation. This demand reflects the value of products that can fit different daily occasions without changing the flavor of a meal or beverage. Unflavored products also give cafés a dependable base for espresso drinks. Their leading position shows that simple formats continue to underpin the South Korea dairy alternatives market. Retailers can use this segment to meet needs for familiar, practical, and versatile drinks.
Flavored dairy alternatives are projected to expand at a 7.45% CAGR through 2031. Café-ready recipes, grain-based choices, and ingredients such as mugwort, black bean, and red bean create a stronger reason to try new variants. Maeil Co. Ltd's August 2026 launch placed mugwort and red bean within a premium soy-milk range. These flavors connect new products with recognizable Korean food traditions. Flavored lines can also support seasonal offerings and a wider range of foodservice menus. The segment’s expansion indicates that novelty can work alongside the established appeal of plain soy milk.
By Packaging Type:
Cartons Support Scale While PET Bottles Gain RelevanceCartons held 54.67% of the South Korea dairy alternatives market share in 2025. Shelf-stable cartons fit the country’s supermarket, hypermarket, and household storage needs. Their use is well suited to repeat purchases of soy milk and other everyday beverages. Cartons also make nationwide distribution easier without an extensive cold chain. In September 2025, Tetra Pak Korea and Maeil Co. Ltd introduced a commercial paper-based barrier aseptic carton for Maeil Soy Milk 99.9. The product combined a paper protective layer with a sugarcane-derived polymer.
PET bottles are the fastest-growing packaging format, with a projected CAGR of 7.23% through 2031. The format is relevant for premium, refrigerated, and convenient single-serve uses. Additionally, cost-effective scalability supports the introduction of premium flavored products, while tamper-evident features build trust among allergen-sensitive consumers. This growth aligns with South Korea's sustainability goals, driven by innovations in rPET recycling and deposit systems. These advancements support portable packaging solutions in e-commerce and foodservice grab-and-go segments. According to the Ministry of Climate, Energy and Environment, South Korea aims to reduce plastic waste generation by 50% and increase the plastic waste recycling rate from 34% to 70% by 2030 [2]. These initiatives are expected to further drive eco-friendly adaptations of PET bottles, meeting the rising demand for vegan and plant-based products.
By Distribution Channel:
Off-Trade Drives Volume While On-Trade Expands TrialOff-trade represented 96.88% of the South Korea dairy alternatives market share in 2025. Supermarkets, hypermarkets, convenience stores, and online retail remain the main routes for routine purchases. These channels allow consumers to replenish familiar beverages without visiting specialty outlets. Convenience stores are especially important for consumers seeking immediate, single-serve products. Pulmuone planned to extend its premium domestic soymilk into convenience stores after its early-2026 launch. Broad retail access remains essential because Non-Dairy Milk is the category’s main volume driver.
On-trade is expected to grow at a CAGR of 6.87% through 2031. Specialty cafés use barista-grade plant-based milks to serve customers who want a dairy-free option with coffee. Foodservice chains are innovating by incorporating dairy alternatives into beverages and baked goods, enhancing visibility and fostering repeat consumption. This trend aligns with growing health awareness, as consumers seek cholesterol-free, nutrient-fortified substitutes. Additionally, the rise of ethical veganism and sustainable dining preferences is driving per capita on-trade consumption of dairy alternatives. According to the United States Department of Agriculture (USDA), monthly per capita spending in this sector reached USD 139.1, highlighting strong foodservice investments that are accelerating the adoption of plant-based alternatives [3].
Competitive Landscape
The South Korea dairy alternatives market reflects meaningful domestic-scale players alongside specialist brands and global entrants. Califia Farms LLC, Dr. Chung’s Food Co. Ltd, Maeil Co. Ltd, and Seoul Dairy Cooperative can leverage established retail relationships and beverage operations. Sahmyook Foods retains credibility with consumers who have long associated its brand with plant-based nutrition. Competition centers on cleaner ingredient lists, nutritional positioning, and performance in foodservice use. This mix leaves room for companies that can offer both familiar flavors and a distinct reason to trade up.
Precision fermentation is emerging as a transformative technology in the market, enabling startups and agile firms to produce animal-free caseins and whey proteins. These innovations enhance the sensory qualities of non-dairy products, such as melt, stretch, and browning in cheeses and yogurts, addressing key barriers to mass adoption. This technological advancement positions disruptors to compete with incumbents in premium segments. Additionally, precision fermentation supports scalable and customizable textures for products like vegan ice creams, aligning with ethical consumer demands and the expansion of urban cafés.
Global and specialty suppliers add pressure in selected niches. Vitasoy, Califia Farms, and Oatly contribute to consumer choice in café and premium retail formats. Oatly’s café-oriented positioning is relevant because coffee is an important route for category trial. Seoul Dairy Cooperative’s 2025 recyclable aseptic packaging launch illustrates how suppliers can compete on packaging credentials as well as product formulation. The competitive field is not dominated by a single producer. The South Korea dairy alternatives market will favor companies that can pair broad access with credible product differentiation.
South Korea Dairy Alternatives Industry Leaders
-
Armored Fresh
-
Blue Diamond Growers
-
Califia Farms LLC
-
Dr. Chung’s Food Co. Ltd
-
Maeil Co. Ltd
- *Disclaimer: Major Players sorted in no particular order
South Korea Dairy Alternatives Market Companies Covered in this Report
- Armored Fresh
- Blue Diamond Growers
- Califia Farms LLC
- Dr. Chung's Food Co. Ltd
- Hanmi Healthcare Inc.
- Maeil Co. Ltd
- Namyang Dairy Products Co. Ltd
- Otsuka Holdings Co. Ltd
- Sahmyook Foods
- Danone Korea
- Vitasoy International
- Lotte Foods Co. Ltd
- NotCo Korea
- Nestlé S.A.
- Pulmuone Co. Ltd
- Yuhan Care
- Yakult Korea
- Seoul Dairy Co-op (plant-based line)
- CJ CheilJedang Corp. (Veggie Garden)
- Daesang Wellife
Recent Industry Developments in South Korea Dairy Alternatives Market
- August 2026: Maeil Co. Ltd launched "Sangha Farm Bean Water Soymilk" in 3 premium varieties, black soybean, mugwort, and red bean. The launch extended its eco-friendly Sangha Farm dairy brand into plant-based beverages and targeted the premium food category. The range used 100% domestic agricultural products and applied quality-management standards previously used for conventional dairy.
- July 2026: Maeil Co. Ltd entered Olive Young’s U.S. retail store in Pasadena and its U.S. online platform with 8 products, including 3 Maeil Soymilk varieties. The move positioned plant-based beverages as K-wellness export products as domestic per-capita white-milk consumption continued to decline.
- October 2025: Seoul Dairy Cooperative launched products in SIG Terra Alu-free + Full Barrier aseptic cartons. The package was classified as recyclable under South Korea’s recyclability grading system. The design removed the aluminum layer, which SIG said represents 25% of a standard aseptic carton’s carbon footprint despite accounting for 5% of its weight.
South Korea Dairy Alternatives Market Report Scope
The South Korea Dairy Alternatives Market is Segmented by Type (Non-Dairy Milk, Non-Dairy Cheese, Non-Dairy Desserts, Non-Dairy Yogurt, and More), Flavor (Flavored and Unflavored), Packaging Type (PET Bottles, Cans, Cartons, and More), and Distribution Channel (On-Trade and Off-Trade). The Market Forecasts are Provided in Terms of Value (USD) and Volume (Tons).
Segmentation Overview
| Non-Dairy Milk | Oat Milk |
| Hemp Milk | |
| Hazelnut Milk | |
| Soy Milk | |
| Almond Milk | |
| Coconut Milk | |
| Cashew Milk | |
| Non-Dairy Cheese | |
| Non-Dairy Desserts | |
| Non-Dairy Yogurt | |
| Other Types |
| Flavored |
| Unflavored |
| PET Bottles |
| Cans |
| Cartons |
| Other Packaging Types |
| On-trade | |
| Off-trade | Convenience Stores |
| Supermarkets and Hypermarkets | |
| Online Retail Stores | |
| Other Off-trade |
| By Type | Non-Dairy Milk | Oat Milk |
| Hemp Milk | ||
| Hazelnut Milk | ||
| Soy Milk | ||
| Almond Milk | ||
| Coconut Milk | ||
| Cashew Milk | ||
| Non-Dairy Cheese | ||
| Non-Dairy Desserts | ||
| Non-Dairy Yogurt | ||
| Other Types | ||
| By Flavor | Flavored | |
| Unflavored | ||
| Packaging Type | PET Bottles | |
| Cans | ||
| Cartons | ||
| Other Packaging Types | ||
| Distribution Channel | On-trade | |
| Off-trade | Convenience Stores | |
| Supermarkets and Hypermarkets | ||
| Online Retail Stores | ||
| Other Off-trade | ||
Market Definition
- Dairy Alternatives - Dairy alternatives are foods that are made from plant-based milk/oils instead of their usual animal products, such as cheese, butter, milk, ice cream, yogurt, etc. Plant-based or non-dairy milk alternative is the fast-growing segment in the newer food product development category of functional and specialty beverage across the globe.
- Non-Dairy Butter - Non dairy butter is a vegan butter alternative that is made from a mixture of plant oils. With an increase in alternative diets like vegetarianism, veganism, and gluten intolerance, plant butter is a healthy non-dairy substitute for normal butter.
- Non-Dairy Ice Cream - Plant based ice cream is a growing category. Non-dairy ice cream is a type of dessert made without any animal ingredients. This is typically considered a substitute for regular ice cream for those who cannot or do not eat animal or animal-derived products, including eggs, milk, cream, or honey.
- Plant-Based Milk - Plant based milks are milk substitutes that are made from nuts (e.g., hazelnuts, hemp seeds), seeds (e.g., sesame, walnuts, coconuts, cashews, almonds, rice, oats, etc.) or legumes (e.g., soy). Plant-based milk such as soy milk and almond milk have been popular in East Asia and the Middle East for centuries.
| Keyword | Definition |
|---|---|
| Cultured Butter | Cultured butter is prepared by having the raw butter go through chemical processing and has been added with certain emulsifiers and foreign ingredients. |
| Uncultured Butter | This type of butter is one which has not been processed in any way |
| Natural Cheese | The type of cheese in its most natural form. It is made from natural and simple products and ingredients, including fresh and natural salts, natural colors, enzymes, and high-quality milk. |
| Processed Cheese | Processed cheese undergoes the same processes as natural cheese; however, it requires more steps and many different forms of ingredients. Making processed cheese involves melting natural cheese, emulsifying it, and adding preservatives and other artificial ingredients or colorings. |
| Single Cream | Single cream contains around 18% fat. It’s a single layer of cream that appears over boiled milk. |
| Double Cream | Double cream contains 48% fat, more than double the amount of fat of single cream. It’s heavier and thicker than single cream |
| Whipping Cream | This has a much higher fat percentage than single cream (36%). Used to top cakes, pies, and puddings and as a thickener for sauces, soups, and fillings. |
| Frozen Desserts | Desserts that are meant to be eaten in frozen condition. E.g., sherbets, sorbets, frozen yogurts |
| UHT Milk (Ultra-high temperature milk) | Milk heated at a very high temperature. Ultra-high-temperature processing (UHT) of milk involves heating for 1–8 sec at 135–154°C. which kills the spore-forming pathogenic microorganism, resulting in a product with a shelf-life of several months. |
| Non-dairy butter/Plant-based butter | Butter made from plant-derived oil such as coconut, palm, etc. |
| Non-dairy Yogurt | Yogurt made from typically made from nuts, like almonds, cashews, coconuts, and even other foods like soybeans, plantains, oats, and peas |
| On-trade | It refers to restaurants, QSRs, and bars. |
| Off-trade | It refers to supermarkets, hypermarkets, on-line channels, etc. |
| Neufchatel cheese | One of the oldest kinds of cheese in France. It is a soft, slightly crumbly, mold-ripened, bloomy-rind cheese made in the Neufchâtel-en-Bray region of Normandy. |
| Flexitarian | It refers to a consumer preferring a semi-vegetarian diet, that is centered on plant foods with limited or occasional inclusion of meat. |
| Lactose Intolerance | Lactose intolerance is a reaction in digestive system to lactose, the sugar in milk. It causes uncomfortable symptoms in response to the consumption of dairy products. |
| Cream Cheese | Cream cheese is a soft and creamy fresh cheese with a tangy taste made from milk and cream. |
| Sorbets | Sorbet is a frozen dessert made using ice combined with fruit juice, fruit purée, or other ingredients, such as wine, liqueur, or honey. |
| Sherbet | Sherbet is a sweetened frozen dessert made with fruit and some sort of dairy product such as milk or cream. |
| Shelf stable | Foods that can be safely stored at room temperature, or "on the shelf," for at least one year and do not have to be cooked or refrigerated to eat safely. |
| DSD | Direct Store Delivery is the process in supply chain management wherein the product is delivered from manufacturing plant directly to the retailer. |
| OU Kosher | Orthodox Union Kosher is a kosher certification agency based in New York City. |
| Gelato | Gelato is a frozen creamy dessert made with milk, heavy cream and sugar. |
| Grass-fed Cows | Grass-fed cows are allowed to graze in pastures, where they eat a variety of grasses and clover. |
Research Methodology
Mordor Intelligence follows a four-step methodology in all our reports.
- Step-1: Identify Key Variables: In order to build a robust forecasting methodology, the variables and factors identified in Step 1 are tested against available historical market numbers. Through an iterative process, the variables required for market forecast are set, and the model is built on the basis of these variables.
- Step-2: Build a Market Model: Market-size estimations for the forecast years are in nominal terms. Inflation is not a part of the pricing, and the average selling price (ASP) is kept constant throughout the forecast period for each country.
- Step-3: Validate and Finalize: In this important step, all market numbers, variables, and analyst calls are validated through an extensive network of primary research experts from the market studied. The respondents are selected across levels and functions to generate a holistic picture of the market studied.
- Step-4: Research Outputs: Syndicated Reports, Custom Consulting Assignments, Databases & Subscription Platforms


