Saudi Arabia Waste Management Market Size and Share
Market Overview
| Study Period | 2021 - 2032 |
|---|---|
| Forecast Data Period | 2027 - 2032 |
| Base Year Market Size (2026) | USD 27.39 Billion |
| Market Size (2027) | USD 29.14 Billion |
| Market Size (2032) | USD 40.14 Billion |
| Growth Rate (2027 - 2032) | 6.61 % |
| Market Concentration | Medium |
Major Players *Disclaimer: Major Players sorted in no particular order Image © Mordor Intelligence. Reuse requires attribution under CC BY 4.0. | |
Saudi Arabia Waste Management Market Analysis by Mordor Intelligence
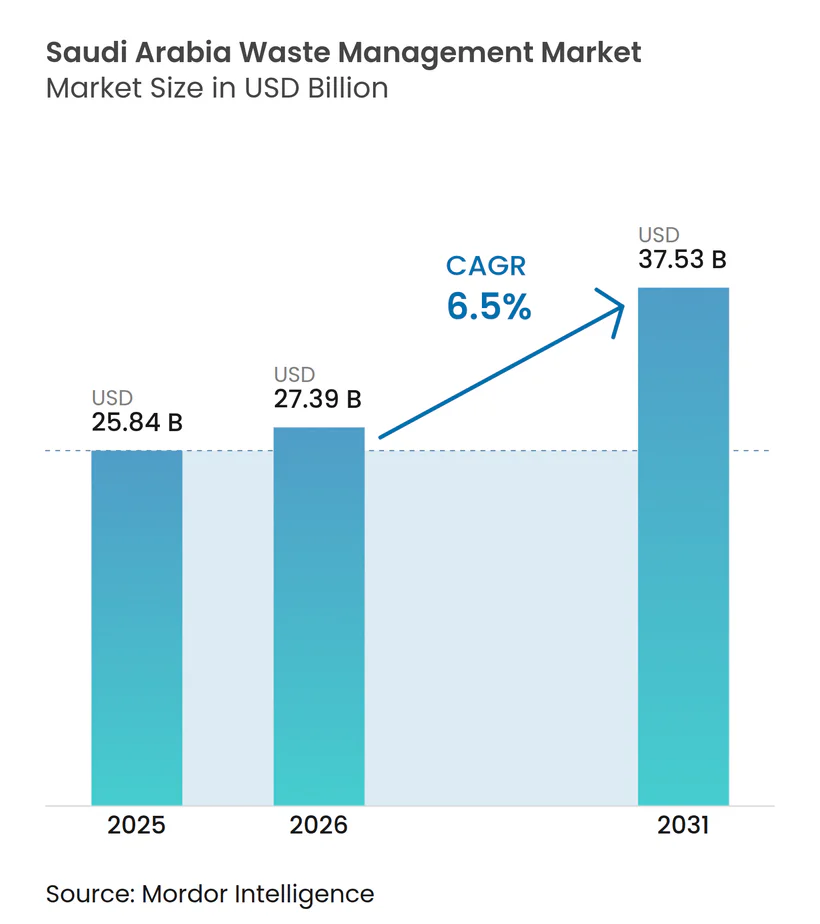
The Saudi Arabia Waste Management Market size is projected to expand from USD 27.39 billion in 2026 and USD 29.14 billion in 2027 to USD 40.14 billion by 2032, registering a CAGR of 6.61% between 2027 and 2032.
National diversion requirements, new recycling licenses, and private investment in treatment and digital systems are reshaping the Saudi Arabia waste management market. The Waste Management Law gives the regulatory framework greater force, while the recycling licensing program brings separate activity streams under clearer operating requirements. The Saudi Arabia waste management market also benefits from construction activity, dense urban centers, and the seasonal waste demands associated with pilgrimage and tourism. Private participation is moving beyond collection contracts toward larger facilities, traceability systems, and recovery projects. Execution remains important because recycling performance must rise materially for the Kingdom to meet its diversion plans within the stated national policy timetable and on schedule.
Key Report Takeaways
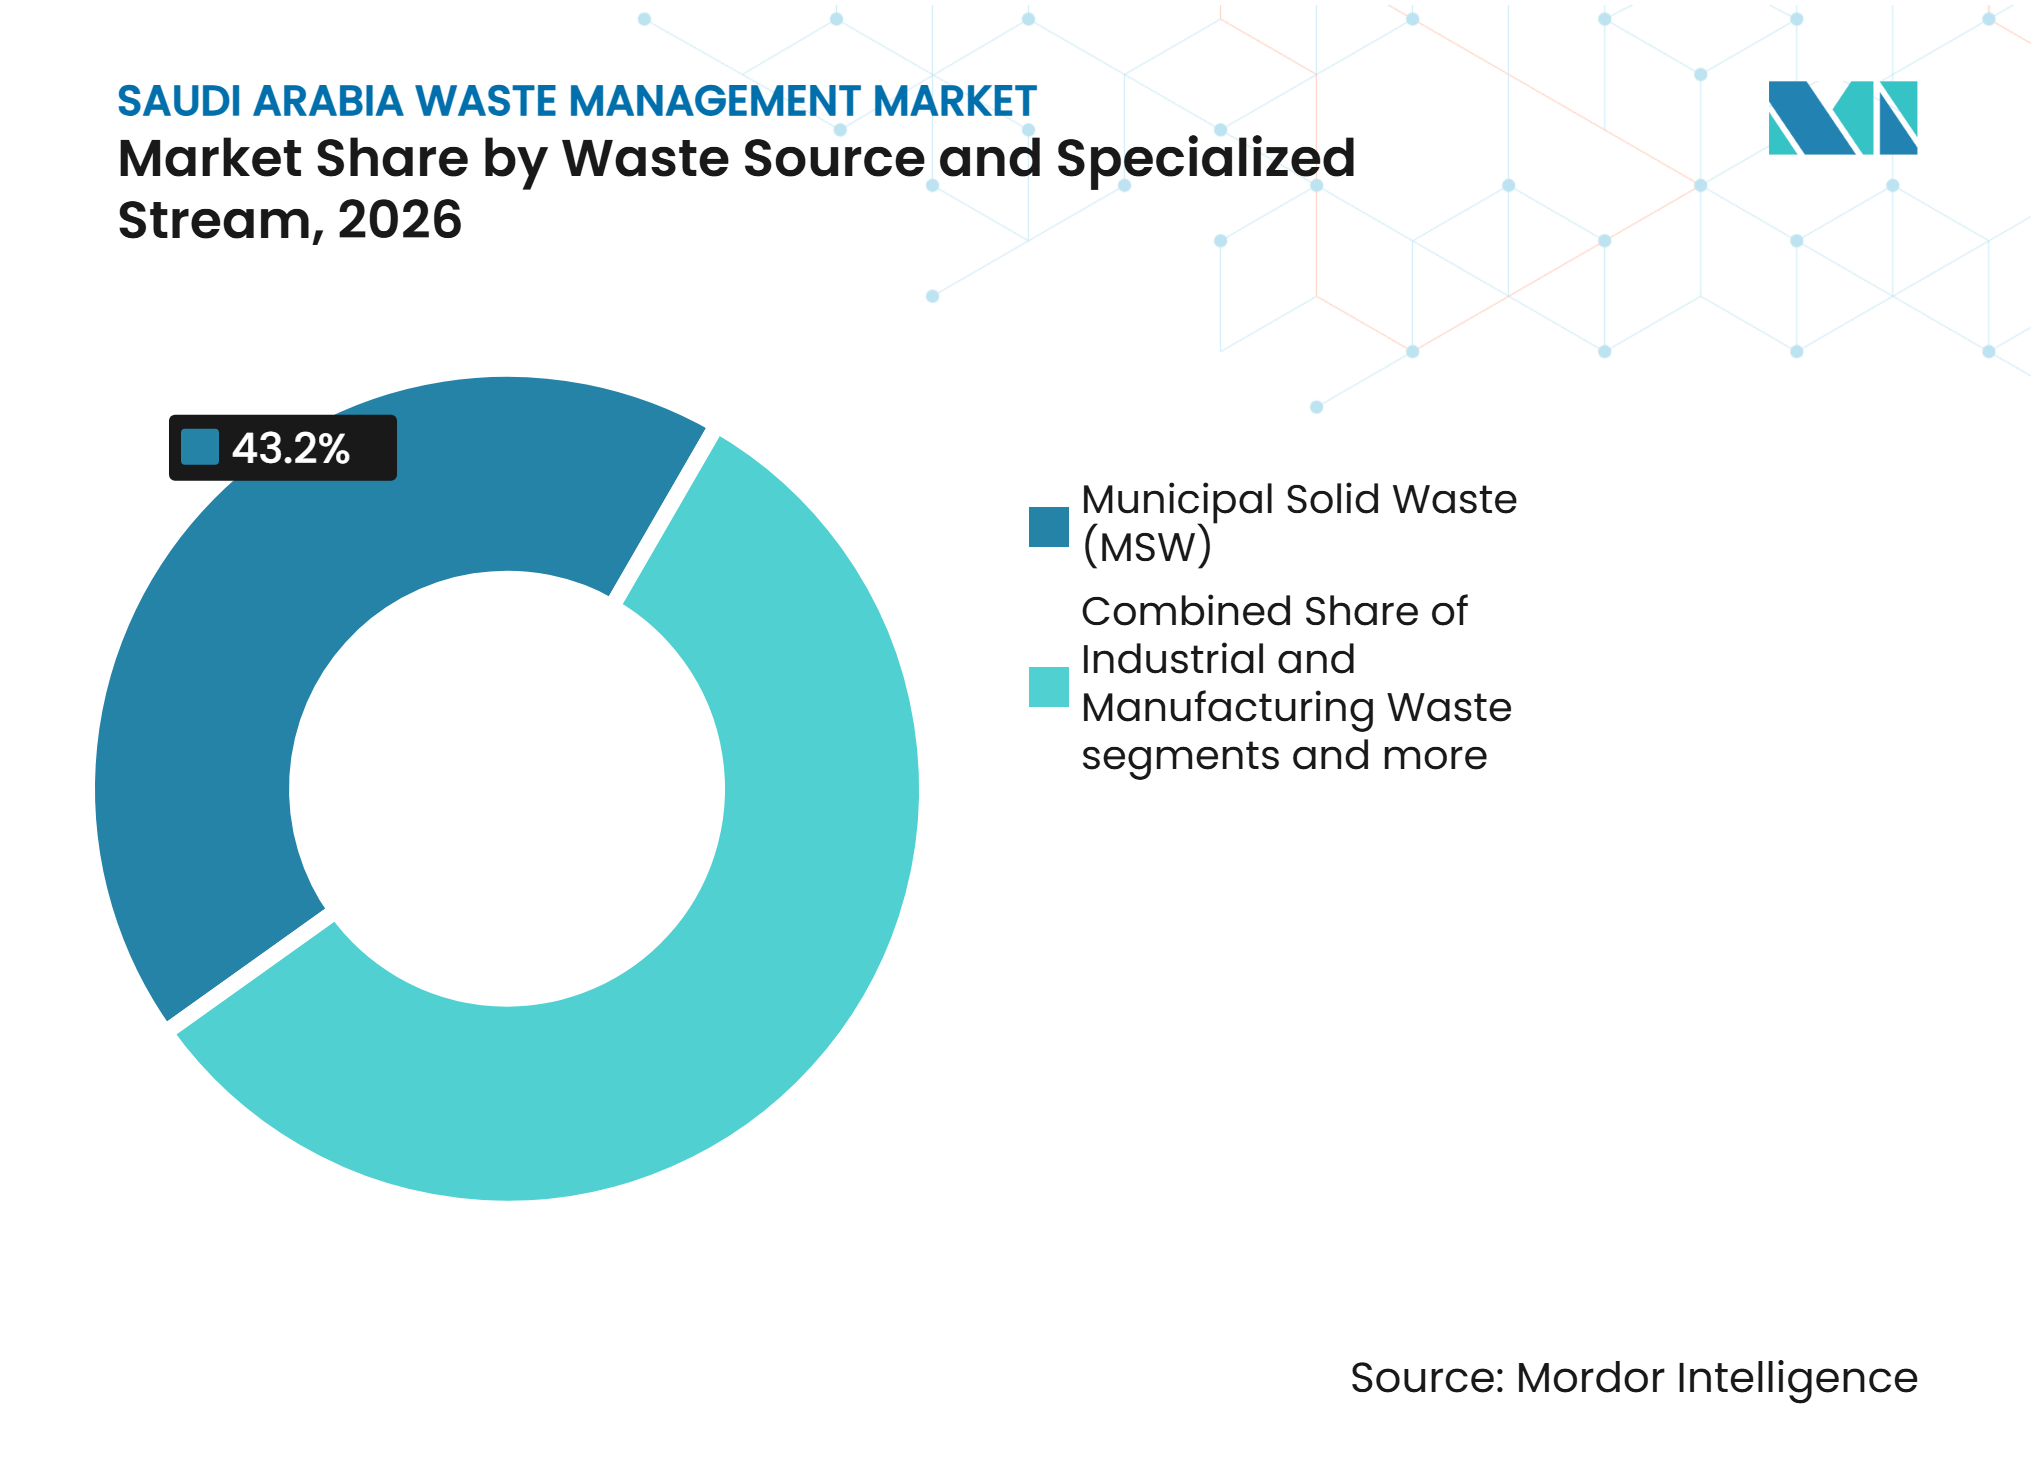
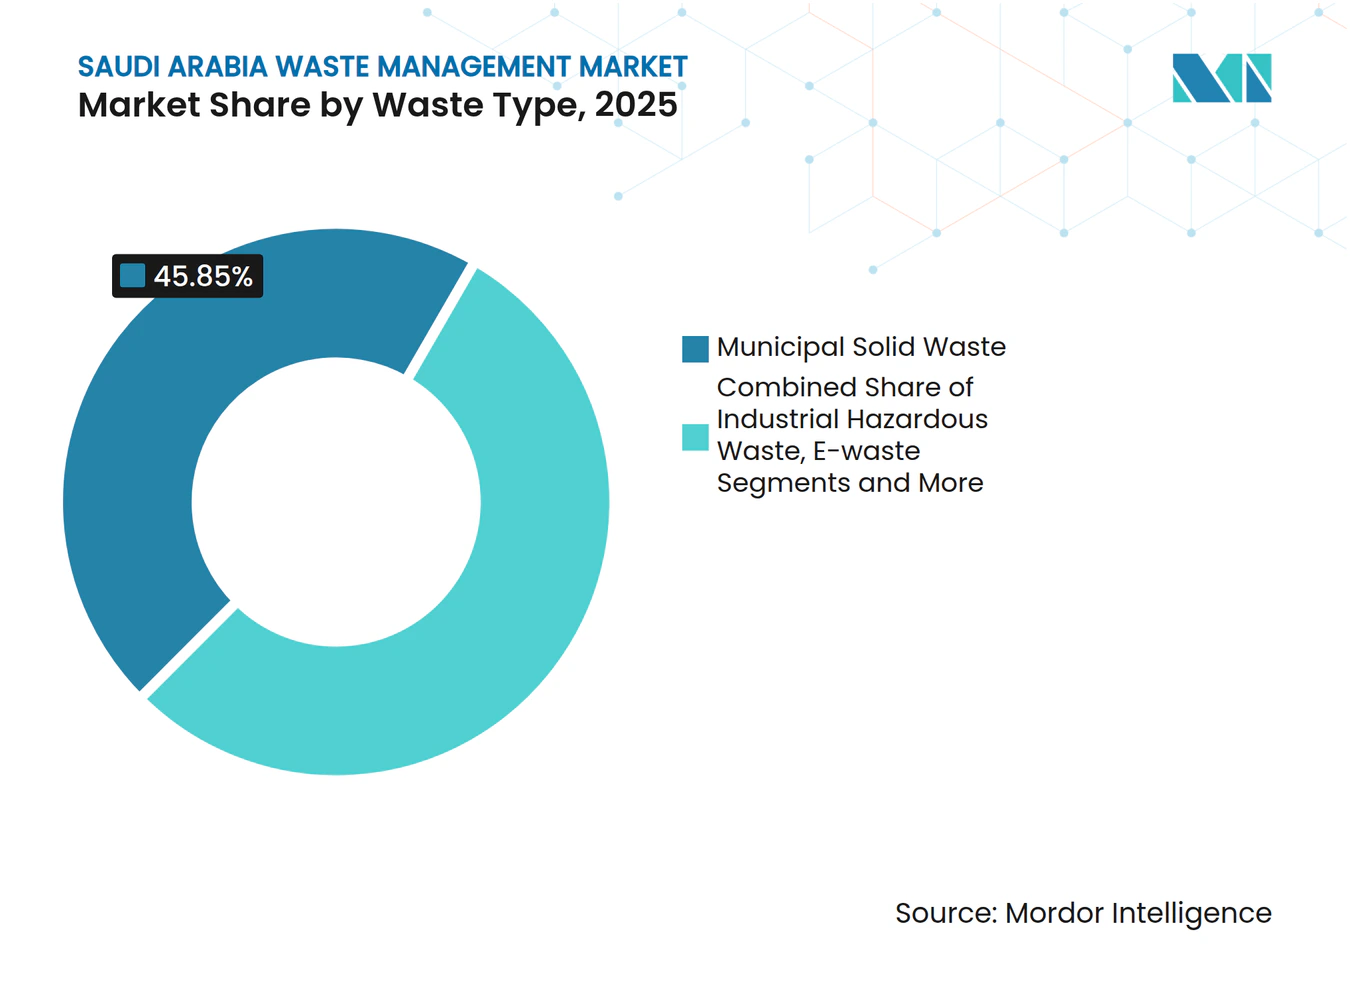
- By waste source and specialized stream, municipal solid waste held 43.2% of the Saudi Arabia waste management market share in 2026, while industrial and manufacturing waste is forecast to grow at a 7.47% CAGR through 2032.
- By service type, disposal/treatment accounted for 53.6% of the Saudi Arabia waste management market size in 2026, while the collection, transportation, sorting, and segregation segment is forecast to grow at a 7.21% CAGR through 2032.
- By waste type, food and organic waste held a 41.8% revenue share in 2026, while e-waste is forecast to grow at a 7.67% CAGR through 2032.
- By geography, Riyadh Province held a 36.4% revenue share in 2026, while the rest of Saudi Arabia is forecast to grow at a 7.81% CAGR through 2032.
Note: Market numbers in this report are based on Mordor Intelligence's proprietary estimation framework, which combines nine months of actuals with Q4 projections for base year 2026.
Market Trends and Insights
Drivers Impact Analysis of Saudi Arabia Waste Management Market*
| Driver | (~) % Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
|---|---|---|---|
| Vision 2030 zero-landfill target milestones | +2.1% | National, with infrastructure concentrated in Riyadh, Jeddah, and Dammam | Medium term (2-4 years) |
| Construction “giga-projects” generating high C&D waste | +1.6% | Riyadh, Makkah Province, Tabuk, and the NEOM and Oxagon corridor | Medium term (2-4 years) |
| Private-sector PPP pipeline for waste infrastructure | +1.2% | National, with early activity in Madinah, Dammam, Tabuk, and Qassim | Long term (≥ 4 years) |
| Economic growth and urban migration | +0.8% | National, centered on Riyadh, Jeddah, and Dammam | Long term (≥ 4 years) |
| Royal Commission green-hydrogen cluster spurring RDF demand | +0.5% | Tabuk, the NEOM and Oxagon corridor, Riyadh, and Jubail | Long term (≥ 4 years) |
| Blockchain-enabled EPR credits unlocking circular-economy financing | +0.3% | National, with early activity in Riyadh and Jeddah | Long term (≥ 4 years) |
| Source: Mordor Intelligence | |||
Vision 2030 Zero-Landfill Target Milestones Drive Market Structure
Saudi Arabia aims to divert 90% of waste from landfills by 2040, with intermediate targets for municipal and construction waste. The program calls for 840 treatment and recovery facilities by 2040. The Riyadh program targets 94% landfill diversion and more than 1.3 million tons of annual biodegradable-waste composting capacity. These requirements create recurring procurement needs for sorting, recovery, composting, and disposal services. Diversion targets have given the market a clearer regulatory demand base.[1]
Construction Giga-Projects Generate Structural C&D Waste Demand
The Roads General Authority states that Saudi Arabia generates 22 million tons of construction and demolition waste each year. In September 2026, the authority expanded its demolition-waste asphalt initiative to Jeddah, Riyadh, and Al-Muzahimiyah. This action gives recovered aggregates a more defined use case in public works. EDGE Innovate commissioned a 50-ton-per-hour processing plant for SIRC and AKAM Recycling in 2025, designed to recover clean stone, wood, and ferrous metals. Saudi Arabia's ongoing infrastructure and construction activities generate substantial volumes of construction and demolition (C&D) waste, creating potential feedstock for recycling and the recovery of reusable construction materials, subject to effective segregation, processing, and quality standards.
Private-Sector PPP Pipeline Supports Waste Infrastructure
MWAN and the National Centre for Privatisation and PPP launched an expression-of-interest process for the National Digital Waste Management Platform in April 2026. The proposed 11-year DBFOMT arrangement includes e-manifest, smart-contract, and regulatory-reporting functions. MWAN has also publicized 27 investment opportunities covering 33 treatment-facility sites with capacity of up to 7 million tons. These projects make traceability, route management, and formal reporting more important for operators. Providers that combine service delivery with compliant data systems are well placed.[2]
Economic Growth and Urban Migration Sustain Underlying Demand
Population growth, urban development, and tourism support waste-service demand in the Kingdom's main cities. A 2026 scientific study projects municipal solid-waste generation will approach 30 million tons annually by 2033. The General Food Security Authority reported in 2025 that food loss and waste declined from 33.1% to 27.9% against the 2019 baseline. Lower loss rates do not remove the need for collection and recovery systems because food consumption and visitor volumes continue to shape total waste flows. Riyadh, Jeddah, and Dammam remain central to demand because their scale supports large treatment and logistics projects.
Restraints Impact Analysis of Saudi Arabia Waste Management Market*
| Restraint | (~) % Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
|---|---|---|---|
| Volatile demand for reclaimed polymers amid new petrochemical capacity | -0.9% | National, with the strongest effect in the Eastern Province and Jubail | Medium term (2-4 years) |
| High upfront CapEx for integrated sites | -0.7% | National, with added pressure in secondary and emerging municipal clusters | Long term (≥ 4 years) |
| Fragmented collection in secondary cities | -0.5% | Qassim, Asir, Jazan, Tabuk, and Madinah | Short term (≤ 2 years) |
| Low household participation in recycling | -0.3% | National, with a larger gap in nonurban communities | Short term (≤ 2 years) |
| Source: Mordor Intelligence | |||
Volatile Demand for Reclaimed Polymers Amid New Petrochemical Capacity
Saudi Arabia's expanding petrochemical production capacity intensifies competition between virgin and recycled polymers across packaging, construction, and industrial applications. The availability of competitively priced virgin resins, influenced by crude oil price fluctuations and domestic petrochemical output, can reduce manufacturers' willingness to purchase recycled polymers at premium prices. This creates uncertainty in recycled material offtake, weakens the profitability of plastic recycling operators, and discourages investments in advanced recycling technologies and additional processing capacity.
High Upfront CapEx for Integrated Sites
Establishing integrated waste management facilities in Saudi Arabia requires substantial capital investment in collection infrastructure, material recovery facilities (MRFs), automated sorting equipment, recycling plants, waste-to-energy facilities, and treatment infrastructure. Additional expenditure on land acquisition, advanced processing technologies, environmental compliance, utility connections, and specialized workforce requirements further increases project development costs. High initial investment requirements and extended payback periods can restrict the participation of smaller private operators, delay infrastructure expansion, and increase dependence on government funding and public-private partnerships.[3]
*Our forecasts treat driver/restraint impacts as directional, not additive. The impact forecasts reflect baseline growth, mix effects, and variable interactions.
Saudi Arabia Waste Management Market Segment Analysis
By Waste Source and Specialized Stream:
Industrial Streams Accelerate Against a Municipal BaseMunicipal solid waste held 43.2% of Saudi Arabia waste management market share in 2026. It includes waste from households, commercial sites, and institutions, which gives it a large and recurring collection base. A 2026 scientific review found that food and biological material represent a meaningful portion of municipal waste in the Kingdom. This composition supports composting and anaerobic-digestion projects where waste is separated effectively. The Saudi Arabia waste management industry is also affected by new classifications for healthcare waste, which place more focus on separation and compliant handling.
Industrial and manufacturing waste is forecast to grow at a 7.47% CAGR from 2027 to 2032. Manufacturing diversification and industrial development expand the need for specialist collection and treatment capacity. Construction and demolition Waste also supports service demand because public projects generate large material volumes. The Roads General Authority's asphalt initiative shows that recovered construction material can be placed into defined end uses. Agricultural and livestock waste remains a major volume stream, but its formal-treatment coverage is less mature than its scale would suggest.



By Service Type:
Disposal Leads While Collection and Sorting Gain ImportanceDisposal/treatment accounted for 53.6% of the Saudi Arabia waste management market size in 2026. The segment includes landfill services, recycling and resource recovery, incineration and waste-to-energy activities, and composting. National policy is shifting the focus from landfill expansion toward resource recovery. This change requires operators to build technical capabilities that meet licensing and environmental requirements. Operators also require consulting, auditing, and training services to comply with regulatory and technical requirements.
Collection, transportation, sorting, and segregation are forecast to advance at a 7.21% CAGR through 2032. The planned e-manifest system increases the importance of traceable collection, carrier certification, and formal reporting. Digital platform functions can improve route planning and create clearer records for material movement. These systems could reduce the role of informal practices in the collection chain. The service segment is therefore gaining strategic importance even where disposal and treatment retain the larger revenue base.
By Waste Type:
Organic Volumes Lead While E-Waste Offers the Fastest GrowthFood and organic waste held 41.8% of Saudi Arabia waste management market share in 2026. This waste stream can support composting, biogas, and other recovery routes when its collection is separated from mixed waste. A 2025 scientific study estimated that food-waste recovery could produce biogas and net energy in Saudi Arabia. The General Food Security Authority has already reported progress in reducing food loss and waste. The Saudi Arabia waste management market can capture more value from organics when municipal and commercial generators have dependable segregation services.
E-waste is forecast to grow at a 7.67% CAGR from 2027 to 2032. A 2025 journal study projected a substantial rise in national e-waste generation by 2030. CST's Recycle Your Device program had collected more than 400,000 devices by the end of 2025 and recycled 960 tons of hardware. CST and MWAN have set a 2040 target of 90% e-waste recycling. Biomedical, battery, tire, and end-of-life vehicle waste also need specialized handling because their materials and risk profiles differ.

Geography Analysis
Riyadh Province: Capital Concentration Supports Large-Scale Infrastructure
Riyadh Province held 36.4% of the Saudi Arabia waste management market size in 2026. The province has the scale to support large facilities, including a proposed RDF project and expanded composting capacity. A 2026 scientific simulation identified a potential waste-to-hydrogen pathway for Riyadh municipal waste. Riyadh Municipality and MWAN also detected nearly 100 illegal construction-waste dumping violations in western Riyadh during a November 2026 joint inspection. This enforcement activity shows that investment is being matched by more active compliance oversight.
Makkah Province: Tourism and Healthcare Create Distinct Service Needs
Makkah Province has a complex waste profile because Jeddah's commercial activity, port operations, construction, and religious tourism overlap. Jeddah removed 11.4 million tons of solid waste during 2025, while its landfill received 9.4 million tons of construction and demolition waste. Wazeen and SUEZ began building a hazardous medical-waste recycling facility in Jeddah in January 2025. The Sustainable Hajj program also converted surplus food into soil enhancers and organic fertilizers during the 2026 pilgrimage period. These activities increase demand for scalable collection fleets, temporary storage, and specialized treatment capacity during peak periods.
Eastern Province and the Rest of Saudi Arabia: Industrial Investment and Distributed Opportunity
The Eastern Province has a large industrial base and includes Dammam, Khobar, Jubail, and Al-Ahsa. Veolia and Ma'aden signed a 2025 agreement covering water-cycle and industrial-waste management in the mining sector. Local initiatives in the province are also testing digital waste-service and source-sorting approaches. The rest of Saudi Arabia is forecast to grow at a 7.81% CAGR through 2032, reflecting the extension of investment into secondary municipalities. Madinah, Qassim, Tabuk, Jazan, and Asir offer varied opportunities in municipal, agricultural, construction, and industrial waste services.
Competitive Landscape
Market Concentration
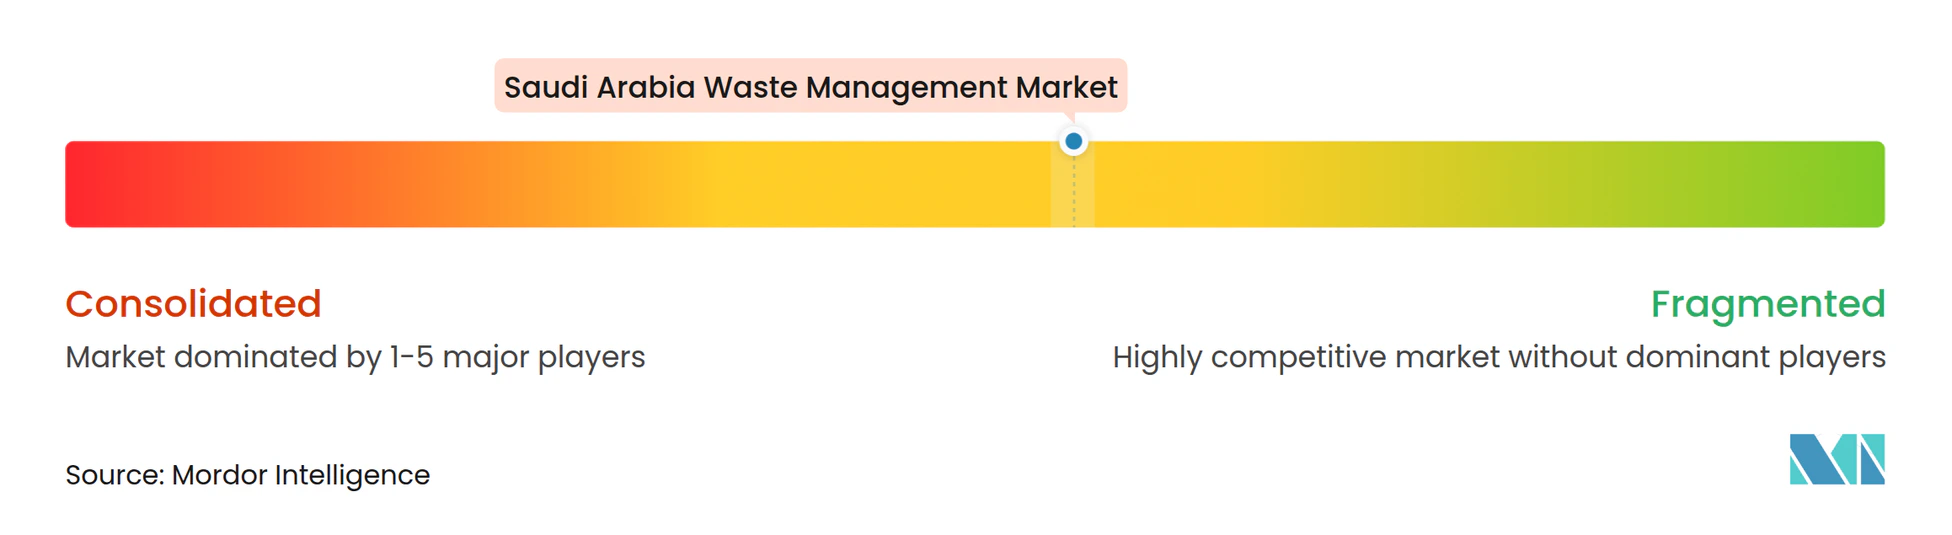
The Saudi Arabia waste management market exhibits a medium level of market concentration. Major participants include Saudi Investment Recycling Company (SIRC), Veolia Middle East, SUEZ Middle East, and BEEAH Group, which operate across different waste streams and service categories. SIRC has expanded its presence in industrial, medical, and construction waste management through subsidiaries and associated businesses, including Reviva, Wazeen, and AKAM Recycling. Established operators benefit from technical capabilities, regulatory experience, infrastructure investments, and access to capital. At the same time, smaller providers continue to find opportunities in secondary-city collection, agricultural-waste recovery, and specialized recycling services.
Strategic partnerships and infrastructure investments are strengthening competition in the market. In September 2025, Veolia signed three agreements with ACWA Power, Ma'aden, and Khazeen covering water technologies, industrial waste management, hazardous-waste treatment, and decarbonization initiatives. Separately, AKAM Recycling commissioned a construction-and-demolition waste processing plant with a capacity of 50 tons per hour in August 2024, supporting material recovery and reducing landfill disposal. These developments demonstrate the increasing focus on integrated environmental services, specialized treatment capabilities, and resource recovery.
Digital technologies are also gaining importance in waste management operations. In March 2025, Aramco Digital partnered with Diversys Software to introduce digital solutions for waste and resource management, including material tracking, compliance monitoring, and performance analytics. In January 2026, SIRC signed an MoU with Hydrogen Utopia International to evaluate InEnTec's Plasma Enhanced Melter technology for converting non-recyclable plastic waste into synthesis gas, with potential applications in hydrogen and sustainable aviation fuel production. These initiatives highlight the growing role of digital traceability, advanced processing technologies, and waste-to-resource solutions in shaping competitive capabilities.
Saudi Arabia Waste Management Industry Leaders
-
Saudi Investment Recycling Co. (SIRC)
-
BEEAH Group
-
Veolia Middle East
-
Averda
-
SUEZ Middle East
- *Disclaimer: Major Players sorted in no particular order
Saudi Arabia Waste Management Market Companies Covered in this Report
- Saudi Investment Recycling Co. (SIRC)
- BEEAH Group
- Veolia Middle East
- Averda
- SUEZ Middle East
- Ramky Enviro Engineers
- NESMA Recycling
- Waste Collection & Recycling Co. (WASCO)
- Dulsco Saudi
- Envac Gulf
- Environmental Horizons Company
- National Environmental Recycling Company (Tadweer)
- Al Qaryan Group
- Sustainable Environmental Works Co. (Mostadama)
- Yanbu United Company (YUNITCO)
- Arab Recycling Company (ARC)
- Waste Management / Environmental Services Company (SEPCO Environment)
- Edama Organic Solutions
- Akam Recycling Company for Environmental Services
- Tadweer Food Recycling Company
Recent Industry Developments in Saudi Arabia Waste Management Market
- September 2026: The Roads General Authority expanded its demolition-waste-in-asphalt initiative to Jeddah, Riyadh, and Al-Muzahimiyah. The authority confirmed that Saudi Arabia generates 22 million tons of C&D waste annually.
- May 2026: The Royal Commission for Makkah City and MWAN launched the Sustainable Hajj food-waste recycling initiative, converting thousands of tons of surplus food during the pilgrimage season into soil enhancers and organic fertilizers.
- September 2025: Veolia signed three strategic MoUs in Saudi Arabia with ACWA Power, Ma'aden, and Khazeen, covering water technology, hazardous-waste treatment, and industrial decarbonization.
Saudi Arabia Waste Management Market Report Scope
The Saudi Arabia Waste Management Market Report is Segmented by Waste Source and Specialized Stream (Municipal Solid Waste, Industrial and Manufacturing Waste, and More), by Service Type (Collection, Transportation, Sorting & Segregation, Disposal/Treatment, and Others), by Waste Type (Plastic Waste, Battery Waste, and More), and by Geography (Riyadh Province and More). The Market Forecasts are Provided in Terms of Value (USD).
Segmentation Overview
| Municipal Solid Waste (MSW) | Residential Waste (Households and Residential Communities) |
| Commercial Waste (Retail, Offices, Hospitality, etc.) | |
| Institutional and Other Municipal Waste (Educational Institutions, Government Facilities, Public Spaces, etc.) | |
| Industrial and Manufacturing Waste | Industrial Hazardous Waste |
| Industrial Non-Hazardous Process Waste | |
| Healthcare and Pharmaceutical Waste (Hospitals, Clinics, Research Laboratories, Pharmaceutical Manufacturing, etc.) | Hazardous Healthcare and Pharmaceutical Waste |
| Non-Hazardous Healthcare and Pharmaceutical Process Waste | |
| Construction and Demolition (C&D) Waste | Hazardous C&D Waste |
| Non-Hazardous C&D Waste | |
| Agricultural and Livestock Waste | Crop and Agricultural Residues |
| Other Agricultural Waste (Livestock and Animal Waste, etc.) | |
| Other Specialized Waste Streams (EOL Vehicles, Radioactive Sources, etc.) |
| Collection, Transportation, Sorting & Segregation | |
| Disposal / Treatment | Landfill |
| Recycling & Resource Recovery | |
| Incineration & Waste-to-Energy | |
| Others (Chemical Treatment, Composting, etc.) | |
| Others (Consulting, Audit & Training, etc.) |
| Plastic Waste |
| Chemical Waste and Hazardous Residues (Solvents, Oils, Contaminated Materials, Sludges, etc.) |
| Electronic Waste (E-Waste) |
| Biomedical and Infectious Waste |
| Battery Waste |
| Rubber and Tire Waste |
| Food and Organic Waste |
| Textile and Leather Waste |
| Metal Waste (Ferrous and Non-Ferrous) |
| End-of-Life Vehicles (Excluding Separately Classified Tires and Batteries) |
| Other Waste Types (Wood and Timber Waste, Glass Waste, Paper and Cardboard Waste, Mineral and Inert Waste such as Bricks and Ceramics, Radioactive, Unclassified Waste) |
| Riyadh Province (Including Riyadh City) |
| Makkah Province (Including Jeddah, Makkah City, and Taif) |
| Eastern Province (Including Dammam, Khobar, Jubail, and Al-Ahsa) |
| Rest of Saudi Arabia (Including Madinah, Qassim, Asir, Tabuk, Jazan, and Other Provinces) |
| By Waste Source and Specialized Stream | Municipal Solid Waste (MSW) | Residential Waste (Households and Residential Communities) |
| Commercial Waste (Retail, Offices, Hospitality, etc.) | ||
| Institutional and Other Municipal Waste (Educational Institutions, Government Facilities, Public Spaces, etc.) | ||
| Industrial and Manufacturing Waste | Industrial Hazardous Waste | |
| Industrial Non-Hazardous Process Waste | ||
| Healthcare and Pharmaceutical Waste (Hospitals, Clinics, Research Laboratories, Pharmaceutical Manufacturing, etc.) | Hazardous Healthcare and Pharmaceutical Waste | |
| Non-Hazardous Healthcare and Pharmaceutical Process Waste | ||
| Construction and Demolition (C&D) Waste | Hazardous C&D Waste | |
| Non-Hazardous C&D Waste | ||
| Agricultural and Livestock Waste | Crop and Agricultural Residues | |
| Other Agricultural Waste (Livestock and Animal Waste, etc.) | ||
| Other Specialized Waste Streams (EOL Vehicles, Radioactive Sources, etc.) | ||
| By Service Type | Collection, Transportation, Sorting & Segregation | |
| Disposal / Treatment | Landfill | |
| Recycling & Resource Recovery | ||
| Incineration & Waste-to-Energy | ||
| Others (Chemical Treatment, Composting, etc.) | ||
| Others (Consulting, Audit & Training, etc.) | ||
| By Waste Type | Plastic Waste | |
| Chemical Waste and Hazardous Residues (Solvents, Oils, Contaminated Materials, Sludges, etc.) | ||
| Electronic Waste (E-Waste) | ||
| Biomedical and Infectious Waste | ||
| Battery Waste | ||
| Rubber and Tire Waste | ||
| Food and Organic Waste | ||
| Textile and Leather Waste | ||
| Metal Waste (Ferrous and Non-Ferrous) | ||
| End-of-Life Vehicles (Excluding Separately Classified Tires and Batteries) | ||
| Other Waste Types (Wood and Timber Waste, Glass Waste, Paper and Cardboard Waste, Mineral and Inert Waste such as Bricks and Ceramics, Radioactive, Unclassified Waste) | ||
| By Geography | Riyadh Province (Including Riyadh City) | |
| Makkah Province (Including Jeddah, Makkah City, and Taif) | ||
| Eastern Province (Including Dammam, Khobar, Jubail, and Al-Ahsa) | ||
| Rest of Saudi Arabia (Including Madinah, Qassim, Asir, Tabuk, Jazan, and Other Provinces) | ||
Key Questions Answered in the Report
What is the projected value of Saudi Arabia waste management services by 2032?
The sector is projected to reach USD 40.14 billion by 2032, expanding at a 6.61% CAGR from 2027. The outlook reflects more investment in collection, recovery, treatment, and formal compliance systems.
Which waste source and specialized stream has the largest revenue share in Saudi Arabia?
Municipal solid waste leads by waste source and specialized stream with a 43.2% revenue share in 2026. Its residential, commercial, and institutional origins make it the core demand base for recurring collection and treatment activity.
Which service is growing fastest in waste management?
The collection, transportation, sorting, and segregation segment is projected to grow at a 7.21% CAGR through 2032. Digital manifest and reporting requirements are increasing the importance of traceable logistics and organized material flows.
Why is e-waste becoming important in Saudi Arabia?
E-waste is forecast to grow at a 7.67% CAGR, supported by device collection programs and a 2040 recycling target. Formal collection, secure dismantling, and recovery of valuable materials will be important for meeting this target.w
Which Saudi region leads waste management demand?
Riyadh province holds 36.4% revenue share in 2026 and supports large-scale treatment and compliance projects. Its infrastructure pipeline and enforcement activity make the province a major location for operators with technical capacity.
What are the main obstacles for waste-treatment investment?
High capital needs, variable demand for recycled polymers, fragmented collection networks, and limited household sorting can constrain project returns. Providers need reliable feedstock, clear contracts, and durable end markets for recovered materials.