
Printer Market Size and Share
Printer Market Analysis by Mordor Intelligence
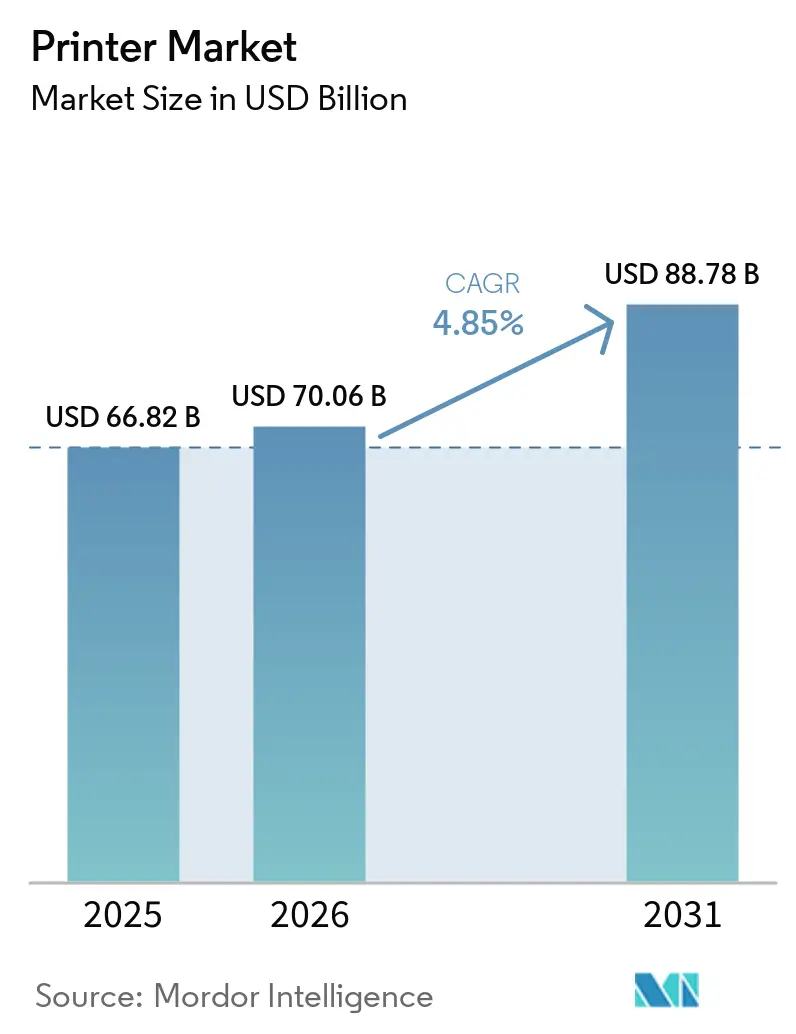
The printer market size is projected to expand from USD 70.06 billion in 2026 and USD 73.46 billion in 2027 to USD 90.67 billion by 2032, registering a CAGR of 4.3% between 2027 and 2032.
Physical delivery workloads in China and record-retention needs can support equipment demand, while digital transaction substitution raises the hurdle for expanding corporate print capacity. In India, ink-tank running-cost economics can support small-office adoption, and label converters’ shorter-run requirements create a separate investment case for digital production capacity. Suppliers respond with equipment partnerships, distribution alliances and workflow services that tie devices to a customer’s operating process. The contrast favors vendors whose channel partners reach logistics operators, label converters and small-office buyers over vendors whose installed base is concentrated in corporate transaction printing.
Key Report Takeaways
- By printer type, multi-functional printers led with a 60.4% printer market share in 2026, while large-format printers are forecast to grow fastest at a 4.75% CAGR from 2027 to 2032.
- Among printing technologies, inkjet led with a 48.24% share of the printer market size in 2026, while thermal (direct and transfer) printers are forecast to lead growth at a 4.9% CAGR from 2027 to 2032.
- Connectivity was led by wired printers with a 53.96% share in 2026, while wireless models (Wi-Fi, NFC, BT) are projected to grow fastest at a 4.95% CAGR from 2027 to 2032.
- For output type, color accounted for a 58.72% share in 2026 and is the fastest-growing segment, with a 4.4% CAGR forecast from 2027 to 2032.
- End-user applications were led by commercial and retail with a 52.21% share in 2026, while healthcare and logistics are forecast to grow fastest at a 5.8% CAGR from 2027 to 2032.
- Geographically, Asia-Pacific led with a 41.32% share in 2026 and is forecast to grow fastest at a 4.8% CAGR from 2027 to 2032.
Note: Market numbers in this report are based on Mordor Intelligence's proprietary estimation framework, which combines nine months of actuals with Q4 projections for base year 2026.
Market Trends and Insights
Drivers Impact Analysis of Printer Market*
| Driver | (~) % Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
|---|---|---|---|
| Surge in e-commerce parcel volumes boosting industrial thermal label printer demand in Asia-Pacific | +2.1% | China within Asia-Pacific | Short term (≤ 2 years) |
| Rapid adoption of ink-tank/EcoTank models lowering Total Cost of Ownership for Small Office Home Offices in emerging economies | +1.9% | India and North America | Medium term (2-4 years) |
| Secure hard-copy archiving of Critical Documents due to regulatory reasons | +0.8% | Colorado within North America | Long term (≥ 4 years) |
| Packaging premiumization driving UV-curable inkjet printers for short-run labels | +1.6% | Australia and United States | Medium term (2-4 years) |
| Sustainability pledges accelerating transition to LED printers and bio-based toners | +0.5% | Australia within Asia-Pacific | Long term (≥ 4 years) |
| Source: Mordor Intelligence | |||
Surge in e-commerce parcel volumes boosting industrial thermal label printer demand in Asia-Pacific
Parcel growth can support industrial thermal label-printer demand by increasing the workload that existing equipment must accommodate. China’s express-delivery volume reached 199 billion items in 2025, up 13.6% from 2024.[1] The resulting hardware opportunity is to add labeling throughput where a delivery operator cannot absorb the higher workload with existing equipment.
Rapid adoption of ink-tank/EcoTank models lowering Total Cost of Ownership for Small Office Home Offices in emerging economies
Low running costs can make ink-tank printers attractive to small offices by reducing the recurring expense a new device must recover. In a November 2025 interview, Epson India president Samba Moorthy estimated ink-tank costs as low as INR 0.2 to 0.3 per page (USD 2.26 to 3.38 per 1,000 pages). He put traditional cartridge-based inkjet and laser prints at INR 2 to 4 per page (USD 22.56 to 45.13 per 1,000 pages). Refilled cartridges cost about INR 0.6 per page (USD 6.77 per 1,000 pages) in his comparison. In FY2025 Q4, Epson reported strong SOHO and home high-capacity ink-tank sales in emerging markets and North America, driven by strengthened sales initiatives. The lower quoted cost even against cartridge refills makes existing refill users a relevant audience for ink-tank sales, extending the proposition beyond buyers replacing new cartridges.
Secure hard-copy archiving of Critical Documents due to regulatory reasons
Regulated recordkeeping can preserve a printing workload even when the underlying transaction system is computerized. Colorado’s 2025 pharmacy rules required outlets using computerized prescription and long-term-care chart-order records to retain daily hard-copy transaction printouts, subject to electronic-record exceptions. The exception required 2-year online retrieval and daily backup. It also required a printable transaction file or an editing lock-out, together with access for regulatory inspection. For outlets following the daily-printout route, reliable output every 24 hours therefore carries a compliance value, while outlets that meet the electronic conditions rely on retrievable, inspectable records instead.
Packaging premiumization driving UV-curable inkjet printers for short-run labels
Label converters can use digital capacity to accommodate a fragmented job mix as well as increase production output. By March 2026, Jet Technologies had completed installation of a second SCREEN Truepress Jet L350UV SAI at Australian converter PDQ Labels. PDQ had shifted more work to digital production to support shorter runs and more product variants. Separately, Los Angeles converter Cover Label upgraded from a Domino N610i to an N730i digital UV inkjet label press in 2025. Cover Label said the upgrade doubled production speed and labels produced per shift.[2] The installations show converters adding UV inkjet capacity for different reasons, job-mix flexibility at PDQ Labels and output per shift at Cover Label, so suppliers compete on both rather than speed alone.
Restraints Impact Analysis of Printer Market*
| Restraint | (~) % Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
|---|---|---|---|
| Corporate cloud migration shrinking transactional print volumes | -1.3% | United States and Canada | Long term (≥ 4 years) |
| Rising raw-material costs inflating consumable prices, delaying SMB upgrades | -0.8% | Japan within Asia-Pacific | Short term (≤ 2 years) |
| RoHS3 compliance costs limiting low-cost laser launches in Europe | -0.3% | European Union and Great Britain | Medium term (2-4 years) |
| Digital signature adoption curbing check and form printing in financial services | -0.2% | Portugal within Europe | Medium term (2-4 years) |
| Source: Mordor Intelligence | |||
Corporate cloud migration shrinking transactional print volumes
Digital transaction substitution can reduce the proportion of business activity that calls for dedicated paper output. In AFP’s survey, organizations in the United States and Canada made 26% of B2B payments by check in 2025, down 7 percentage points from 2022. Check-based receipts represented 25% of their B2B payments in 2025, down 5 percentage points from 2022. These changes cover both payments made and payments received, so a smaller share of surveyed corporate payment flows passed through paper checks in 2025. As a corporate buyer shifts transactions away from paper, its remaining output must justify the cost of dedicated printing capacity, raising the hurdle for device expansion.
Rising raw-material costs inflating consumable prices, delaying SMB upgrades
Higher consumables prices can make printer replacement harder to justify when new hardware leaves recurring supply costs exposed. Brother Sales, Brother Industries’ domestic sales subsidiary, revised selected Japanese consumables prices by about 5% to 15%, effective April 10, 2025. The revision covered shipment prices for 110 ink-cartridge items and shipment and list prices for 57 laser-printer toner and drum items. Separately, HP Inc. reported that global printer customers delayed hardware refresh decisions amid higher industry costs and market softness in Q4 FY2025. The selected Brother revisions illustrate the recurring cost a replacement printer must carry, a hurdle to upgrading alongside the refresh delays HP reported.
*Our forecasts treat driver/restraint impacts as directional, not additive. The impact forecasts reflect baseline growth, mix effects, and variable interactions.
Printer Market Segment Analysis
By Printer Type:
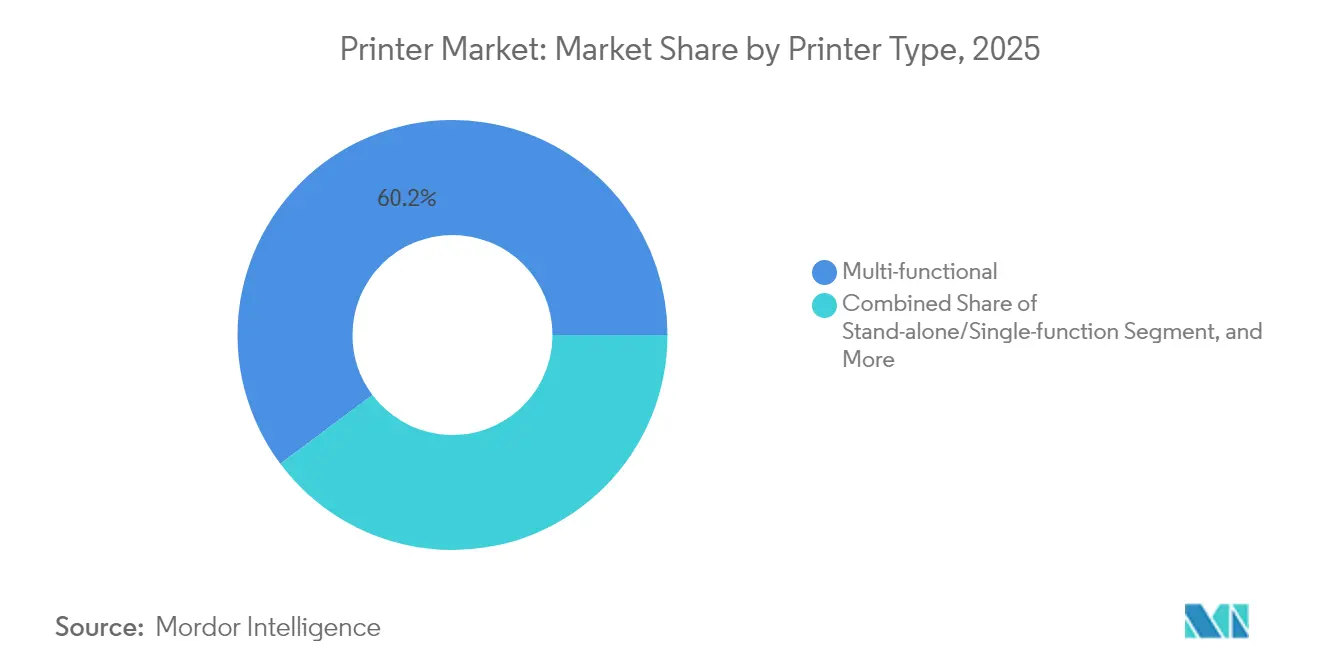
Fleet Consolidation Supports Multifunction DemandMulti-functional printers accounted for a 60.4% share of the printer market size in 2026, making them the largest segment by printer type. On October 14, 2025, Mid and West Wales Fire and Rescue Authority awarded Vision (Office Automation) Limited a contract for 75 new A3/A4 multifunction devices. The program was designed to replace a mixed fleet of multifunction devices and monochrome A4 printers across administrative, command and fire-station sites. Consolidation on multifunction models creates a defined replacement program across several operating locations, making the fleet specification a stronger sales route than an isolated device refresh.
Large-format printers are the fastest-growing segment, with a 4.75% CAGR forecast from 2027 to 2032. UK trade printer Printvision installed a swissQprint Kudu flatbed printer in Leicester in September 2025 to support large-format, exhibition and display work. Industrial/production printers address packaging output, illustrated by Pratt Industries’ June 2025 report that its HP PageWide T1195i became the highest-producing press in HP’s global PageWide install base within 6 months of installation. These examples distinguish the addition of display capabilities from intensive use of a packaging-production asset. The sales proposition consequently changes with the application, from broadening the work a trade printer can accept to supporting production intensity within a packaging operation.



By Technology Type:
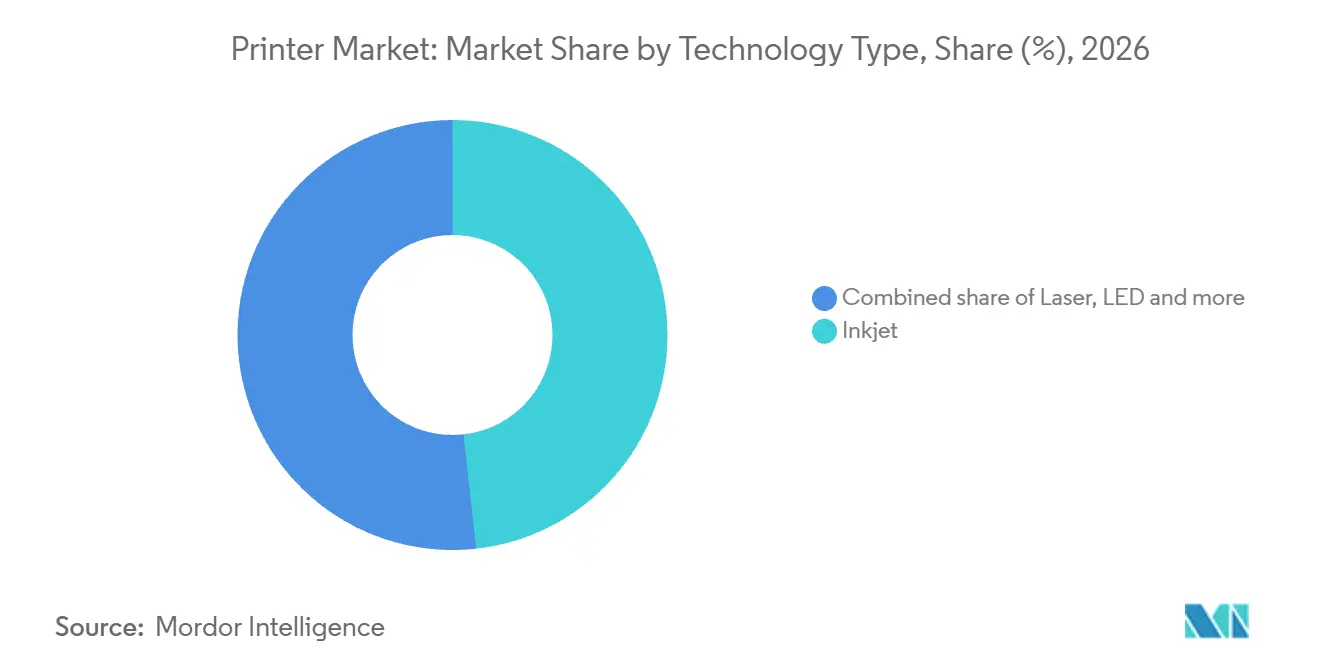
Refillable Inkjet Adoption and Thermal Launches Shape DemandInkjet represented a 48.24% printer market share in 2026, making it the largest segment by technology. Canon reported that its inkjet printer unit sales grew in 2025, mainly for refillable ink-tank models. Seiko Epson’s internally tracked worldwide SOHO/home high-capacity ink-tank hardware units were approximately 13.7 million in FY2025, versus approximately 13.1 million in FY2024. For Canon and Epson, refillable-model placements therefore connect inkjet’s hardware scale to a demonstrated source of additional units.
Thermal (direct and transfer) printers are the fastest-growing segment, with a 4.9% CAGR forecast from 2027 to 2032. In February 2026, SATO Corp. reported a strong start for its CL4/6-SXR line and expected cumulative sales of 300,000 units worldwide from FY2025 through FY2030. The CL4-SXR and CL6-SXR support both direct thermal and thermal-transfer printing. SATO attributed the start to design developed around market needs and presales work that generated early sales opportunities. That puts design relevance and early sales development alongside the print method itself as practical determinants of hardware adoption.

By Connectivity/Interface:
Cabled Options Coexist with Portable Wireless DemandWired connectivity held the largest segment position, with a 53.96% share in 2026. Zimbabwe’s August 25, 2025, DFM/DC/02/2025 award to Venor Projects covered one heavy-duty color printer with USB 2.0 PC, USB memory and Ethernet network connections, alongside wireless capability. This combination shows how a buyer can specify cabled connection options within a multifunction configuration, making interface breadth relevant alongside the printing functions themselves. For suppliers addressing this specification, wireless capability cannot substitute for the requested USB and Ethernet ports.
Wireless (Wi-Fi, NFC, BT) printers are the fastest-growing segment, with a 4.95% CAGR forecast from 2027 to 2032. On October 17, 2025, the Construction Industry Authority of the Philippines ordered 2 Epson WF-100 portable printers from ADECS International Corporation. The WF-100 is designed for mobile professional use and supports built-in wireless connectivity and Wi-Fi Direct, according to Epson. Pairing portable hardware with direct wireless connectivity makes location flexibility part of the equipment proposition, allowing a supplier to address printing tasks where a cabled connection would be impractical.
By Output Type:
Color Leadership Leaves Distinct Monochrome RequirementsColor was the largest output segment, with a 58.72% share in 2026, and is the fastest-growing segment, with a 4.4% CAGR forecast from 2027 to 2032. JEITA recorded 4.32 million color MFP shipments across Japan and overseas combined in 2025, equal to 95% of 2024. In an April 2025 report, Hudson Valley Community College’s in-plant said its need for color had increased and monochrome demand had declined before it installed Canon imagePRESS V800s. This buyer-level shift creates a color-capacity investment case even as the broader JEITA color MFP shipment series declines.
Monochrome printers can address a separate office requirement within a sector led by color output. On July 21, 2025, the Philippines’ Professional Regulation Commission Regional Office XI in Davao City requested quotations for 6 monochrome ink-tank printers. The request followed 2 failed bidding rounds and identified office operations and stakeholder services as the intended uses. Such a specification gives suppliers a defined single-color equipment opportunity, making the required office function more useful for selecting the device than the overall leadership of color output.
By End-user Application:
Retail Integration and Healthcare Services Create Different RoutesCommercial and retail applications formed the largest segment, with a 52.21% share in 2026. By October 2026, Toshiba Global Commerce Solutions reported 454 self-checkout systems installed year to date across 150 Colruyt Group stores in Belgium. Its complete checkout configuration included the Toshiba BV420 printer, placing the device inside a store-system rollout. This creates a potential equipment sales route tied to checkout deployment, where the printer is supplied as part of a larger retail system. For printer suppliers, access to the retail integration relationship can therefore matter as much as promoting a standalone device.
Healthcare and logistics applications form the fastest-growing segment, with a 5.8% CAGR forecast from 2027 to 2032. Epson’s July 23, 2026, announcement described Towner County Medical Center’s deployment of nearly 30 Epson business inkjet devices in North Dakota. Liberty Business Systems, Inc. implemented the managed print environment, including A3 multifunction and A4 color and monochrome devices. Separately, Buckinghamshire Healthcare NHS Trust awarded Altodigital Networks Limited a managed printer services contract on May 13, 2025. Together, the deployment and award show how healthcare buyers can combine device adoption with service responsibility, making the supported hardware configuration part of the supplier’s proposition.
Geography Analysis
Asia-Pacific Printer Market
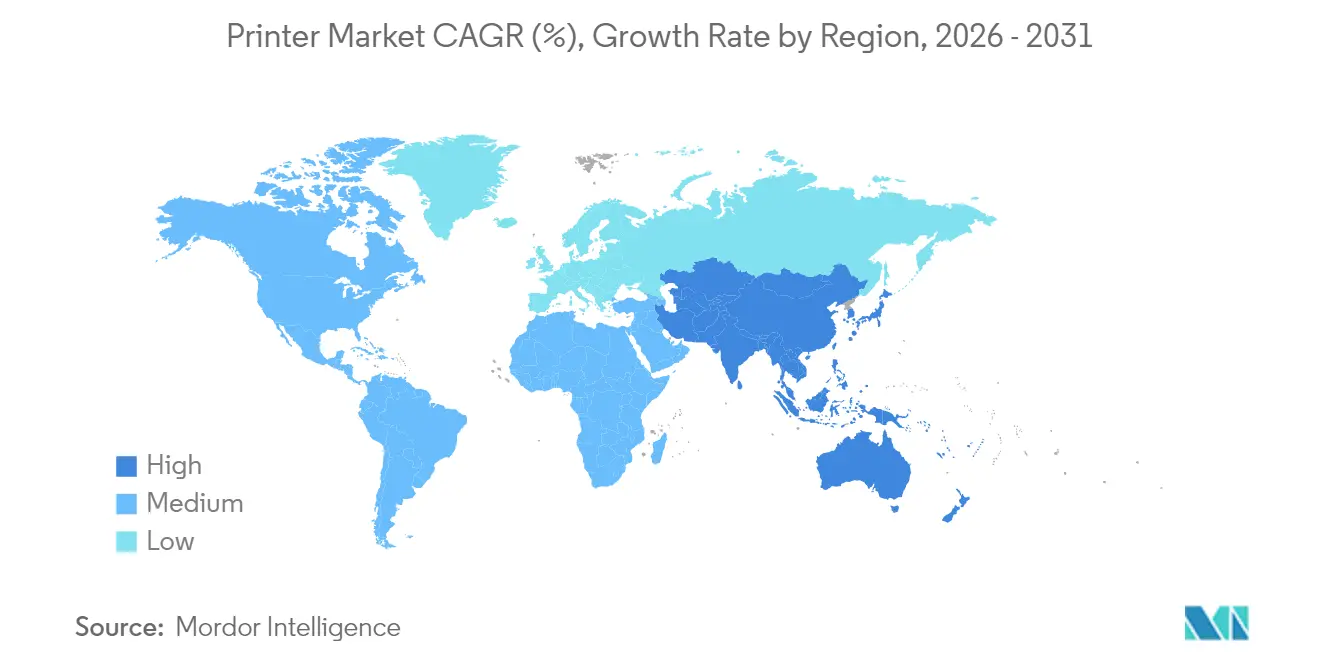
Asia-Pacific accounted for a 41.32% share of the printer market size in 2026 and is the fastest-growing geography, with a 4.8% CAGR forecast from 2027 to 2032. IDC reported that Asia/Pacific excluding Japan and China had the strongest year-over-year hardcopy peripheral shipment growth in Q2 2026, driven by continued growth in India. Japan ran the other way, with JEITA recording 1.48 million printers shipped in the first half of 2026, 94% of the first-half 2025 total. Australia adds a distinct office-equipment use case, with OKI Data Australia’s October 2025 mono LED offering addressing high-volume workplaces. India-led shipment growth supports the regional expansion case, while Japan’s decline and Australia’s high-volume office focus give suppliers different country-level requirements.
North American and European examples highlight equipment tailored to established commercial print applications. In January 2026, Canon Canada installed a Ronik-built Texas flatbed printer at Hemlock Printers’ Burnaby facility for high-volume card stock, posters, advertisements, and corrugated and coroplast materials for national campaigns. In Europe, Digibux Print in central and southern Italy runs Agfa’s Jeti Bronco H3300 HS hybrid inkjet press for agencies, the events industry and major clients. At Hemlock and Digibux, the equipment’s application-specific capacity connects the investment to campaign and event production.
In South America, Brazil’s Ministério Público do Estado do Pará adjudicated and homologated a price-registration procurement for printers, toner and paper on July 25, 2025. HP reported that Indigo 6K+ digital label and packaging press installations were being implemented in Argentina as of late October 2025. Within Middle East and Africa, South Africa’s Department of Justice and Constitutional Development awarded Bompembe IT Services a once-off contract on March 4, 2025, for 254 printers for its North West Provincial Office. Heidelberg Gulf reported that Yess Labels Dubai signed for its first Gallus One digital label press at Labelexpo Europe 2025. The Pará registration and South African award follow public-procurement rules, while the Argentine installations and Dubai agreement tie converter demand to capital-equipment sales cycles.
Regulatory Framework and Outlook
This comparison examines selected jurisdictions from the perspective of printer equipment manufacturers, focusing on public-purchase qualification, product conformity and end-of-life administration. The United Kingdom column addresses the Great Britain RoHS route, whose conformity-mark arrangements are distinct from Northern Ireland. Brazil’s household reverse-logistics system includes printer categories, with professional, corporate and health-service equipment and certain large-generator waste excluded. Brazil’s household-printer suppliers therefore bear duties under this reverse-logistics system that suppliers of the excluded professional, corporate and health-service equipment do not.
Regulatory Table of Printer Market
| Decision factor | United States | United Kingdom | China | Brazil |
|---|---|---|---|---|
| Primary authority | U.S. Environmental Protection Agency and Department of Energy’s Federal Energy Management Program (FEMP) | Office for Product Safety and Standards | State Administration for Market Regulation | Ministry of Environment and Climate Change |
| Key instruments or direction | ENERGY STAR Version 3.2 and federal purchasing qualification | Great Britain RoHS Regulations 2012 and CE or UKCA marking | China Compulsory Certification (CCC) rules for computer-connected printing devices and multifunction printer-copiers | Household electronics reverse logistics and Sisrev-BR |
| Commercial effect | Covered federal purchases require ENERGY STAR-certified or FEMP-designated products, subject to statutory exemptions | Manufacturers demonstrate component compliance before assembly, by testing or otherwise | Certification and CCC marking required for covered market entry | Household-printer take-back administration and reporting under existing duties |
| Current policy attractiveness | High | Medium | Medium | Medium |
| Future direction of policy attractiveness | No change | No change | No change | No change |
| Source: Mordor Intelligence | ||||
For manufacturers, the United States receives High for channel-specific federal purchasing requirements with statutory exemptions, while ENERGY STAR Version 3.2 has no new version in development, supporting No change. The United Kingdom receives Medium because manufacturers must demonstrate component conformity before assembly, balanced by CE or UKCA marking flexibility in Great Britain, with No change conditional on continuing EU and GB RoHS alignment. China receives Medium because certification and CCC marking gate covered market entry, imposing a broader access condition than a purchasing-channel requirement, with No change reflecting a 2026 certification-method transition addressing other product categories. Brazil receives Medium because household-printer suppliers carry reverse-logistics administration beyond the initial sale, while No change reflects Sisrev-BR’s September 18, 2026, organization of registration and reporting under existing duties.
Value Chain Stages
The value chain compares equipment supply, workflow deployment and applications administration, separating hardware sales from services attached to the installed system. In 2025, Canon began supplying digital printing equipment to Heidelberger Druckmaschinen AG and expanded its commercial and industrial printer sales channels.[3] The comparison distinguishes manufacturer-to-manufacturer supply from downstream services delivered to an equipment user.
Value Chain Analysis Table of Printer Market
| Primary activity | Key participants | Value capture | Bottleneck | Resilience response |
|---|---|---|---|---|
| Digital printing equipment supply | Equipment manufacturers such as Canon Inc. | Equipment sales | Aligning equipment supply with channel delivery needs | Coordinate supply and partner rollout schedules |
| Device deployment and workflow integration | Deployment and workflow providers such as Ricoh USA | Deployment and integration services | Moving separate print, fax and copy tasks into an integrated workflow | Configure imaging, scanning and document routing during deployment |
| Applications administration | Managed applications providers such as Ricoh USA | Applications-administration services | Manual document routing and incomplete application forms | Automate routing and administer hardware and software together |
| Source: Mordor Intelligence | ||||
Hardware sales and applications administration capture value at different points in a printer deployment. Canon reported increased cut-sheet equipment sales, linking equipment-stage earnings to channel reach. In Ricoh’s global footwear-retailer engagement, consolidating printers, faxes and copiers into MFPs preserved an administration role for document routing and application handling, so fewer devices did not remove the associated service work.
Competitive Landscape
Market Concentration
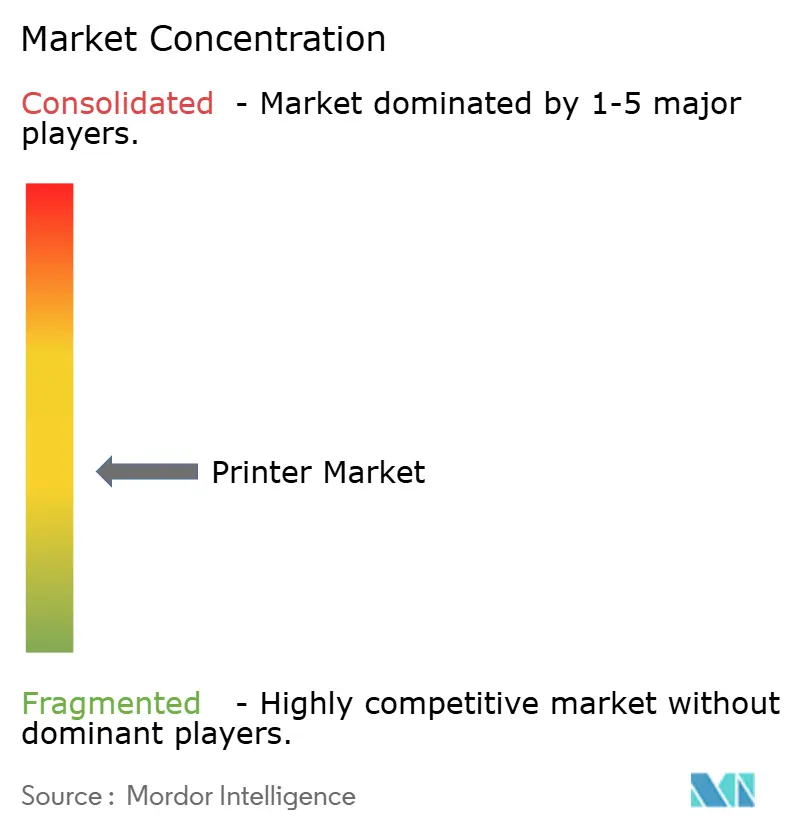
Competition is moderately concentrated around established manufacturers, with HP Inc., Canon Inc., Seiko Epson Corp., Brother Industries Ltd. and Xerox Corporation among the major participants. HP reported Printing net revenue of USD 3.9 billion in Q3 fiscal 2026, down 2% from Q3 fiscal 2025, with consumer revenue down 2% and commercial revenue down 1%. The segment included supplies, whose revenue fell 3%, while hardware units declined 7% over the same period. Competition consequently involves defending the value of an installed printing relationship as well as winning the next device sale.
Companies are using corporate consolidation and local platform alliances to broaden their printing businesses. On July 1, 2025, Xerox Holdings Corporation, the parent of Xerox Corporation, completed its acquisition of Lexmark International, Inc. for USD 1.5 billion, including net debt and assumed liabilities. In August 2025, Brother Industries Ltd. agreed a capital and business alliance with Dots for Inc. to expand its printer and All-in-One business in Africa, combining printer expertise with the partner’s local network. The acquisition consolidates an existing print business, while Brother’s agreed alliance addresses local access as an intended route to expansion in Africa.
Canon’s soft 2025 results and HP’s security-focused announcement illustrate feature differentiation alongside postponed office investment. Canon reported lower Printing Business Unit sales in 2025 amid postponed investment in Europe and the United States, with office multifunction device and commercial printing demand particularly soft in the United States. On March 24, 2026, HP announced LaserJet Pro 4000/4100 and Enterprise 5000/6000 series with quantum-resistant BIOS and firmware integrity protection. HP said its internal analysis found no in-class rival with a quantum-resistant scheme protecting BIOS and firmware integrity, as of January 2026 for SMB models and March 2025 for enterprise models. For SMB buyers, HP paired the announced printer protection with Workforce Experience Platform and optional Security Manager, connecting device integrity to fleet-wide security compliance and administration.
Printer Industry Leaders
-
HP Inc.
-
Canon Inc.
-
Seiko Epson Corp.
-
Brother Industries Ltd.
-
Xerox Corporation
- *Disclaimer: Major Players sorted in no particular order
Printer Market Companies Covered in this Report
- HP Inc.
- Canon Inc.
- Seiko Epson Corp.
- Brother Industries Ltd.
- Xerox Corporation
- Ricoh Co. Ltd.
- Konica Minolta Inc.
- FUJIFILM Business Innovation Corp.
- Kyocera Document Solutions
- Zebra Technologies Corp.
- Dell Technologies Inc.
- Toshiba Tec Corp.
- Sharp Corp.
- Mimaki Engineering Co.
- Roland DG Corp.
- Agfa-Gevaert N.V.
- Brady Corp. (Datamax-O’Neil)
- BIXOLON Co. Ltd.
- SATO Corp.
- TSC Auto ID Technology
Key Opportunities for Market Participants
These opportunities compare recurring catalog orders, security-focused sourcing and aggregated printer purchasing by US government buyers. Federal, state, local and tribal agencies can use GSA’s Governmentwide Printer BPAs during the September 6, 2024, to September 5, 2027, ordering period. The near-term supplier opening is to serve additional buyer orders through the existing vendor and OEM pairings.
Market Opportunities Table of Printer Market
| Opportunity | Why now | Buyer / lead segment | Recommended play | Main barrier | Likely beneficiaries |
|---|---|---|---|---|---|
| Recurring printer orders through agency catalogs | Configured catalogs refresh quarterly for technology and OEM product changes | Eligible agencies with recurring printer requirements | Build quantity and configuration plans into an agency catalog | BPA onboarding is closed to new vendors | ABM Federal with HP Inc. |
| Printer sourcing with supply-chain controls | The BPAs integrate NIST-based supply-chain-risk requirements and operational controls | Eligible government agencies prioritizing supply-chain controls | Match printer proposals and delivery processes to the required controls | Operational controls extend the task beyond selecting hardware | The Lioce Group Inc. with Canon Inc. |
| Coordinated higher-volume printer orders | GSA identifies demand aggregation and quantity discounts as potential savings mechanisms | Federal agencies combining printer requirements | Coordinate quantities and configurations before requesting volume pricing | Aligning requirements across participating buyers | MicroTechnologies LLC with Konica Minolta Inc. |
| Source: Mordor Intelligence | |||||
The BPA ordering period ends September 5, 2027, making this a near-term order channel for the listed vendor and OEM pairings. GSA says creating an agency catalog can reduce acquisition time to about 5 days. That conditional advantage favors usable specifications and prompt order responses, while closed BPA onboarding constrains direct entry by new vendors. Suppliers outside the roster need a different procurement route, and the listed firms have a limited window for converting catalogs into orders.
Recent Industry Developments in Printer Market
- Sep 2026: Seiko Epson Corp. announced CONTOURJET, a system combining inkjet technology and robotics for direct-to-shape printing on three-dimensional objects, including sports equipment, automotive parts and industrial products.
- Mar 2026: HP Inc. announced LaserJet Pro 4000/4100 and Enterprise 5000/6000 series with quantum-resistant BIOS and firmware integrity protection. HP said its internal analysis found no in-class rival with a quantum-resistant scheme protecting BIOS and firmware integrity, as of January 2026 for SMB models and March 2025 for enterprise models.
- Mar 2026: Canon U.S.A., Inc. introduced the imageFORCE C1935P compact color single-function printer and the 1643 Series desktop monochrome multifunction and single-function printers in the United States. The models were available for ordering and shipping.
Printer Market Report Scope and Research Methodology
Market Definition and Coverage
The global printer market measures annual manufacturer revenue from complete printer hardware sold worldwide. It covers printer devices for household, business, institutional, and public-sector use, including multifunction printers with integrated scanning.
Scope exclusions: Inks and toners, paper, printer servicing contracts, standalone scanners, and separately sold printer replacement parts are excluded.
Segments Covered in This Report
- By Printer Type
- Multi-functional
- Stand-alone/Single-function
- Large-format
- Industrial/Production
- By Technology Type
- Inkjet
- Laser
- LED
- Thermal (Direct and Transfer)
- Dot-Matrix
- By Connectivity/Interface
- Wired
- Wireless (Wi-Fi, NFC, BT)
- By Output Type
- Color
- Monochrome
- By End-user Application
- Residential
- Commercial and Retail
- Educational Institutions
- Enterprises
- Government
- Healthcare and Logistics
- By Geography
- North America
- United States
- Canada
- Mexico
- Europe
- Germany
- United Kingdom
- France
- Nordics
- Rest of Europe
- South America
- Brazil
- Rest of South America
- Asia-Pacific
- China
- Japan
- India
- Southeast Asia
- Rest of Asia-Pacific
- Middle East and Africa
- Middle East
- GCC
- Turkey
- Rest of Middle East
- Africa
- South Africa
- Rest of Africa
- Middle East
- North America
Data Sources, Market Sizing, and Validation
Desk Research
Public sources such as the Japan Electronics and Information Technology Industries Association (JEITA) annual printer shipment series offer an equipment-volume check, while U.S. Census Bureau international trade datasets help track imports and exports for relevant printer classifications. Eurostat's Prodcom statistics provide annual sold-production values and physical production measures for European manufacturers, and the World Intellectual Property Organization's IP statistics offer context on technology activity without serving as a sales measure.
Manufacturer filings and investor materials can separate printer devices from supplies and services and help interpret price and product mix, while reputable press, public procurement notices, and product announcements can corroborate regional activity and refresh timing. These sources are not exhaustive, and further sources inform collection, validation, and clarification.
Primary Interviews and Surveys
Interview and survey recruitment would cover printer manufacturer and brand leaders, component and channel sales or service leaders, managed-print providers, and procurement or fleet managers serving consumer, business, institutional, and public-sector buyers across global regions. Structured questions would test secondary estimates of device definitions, shipments, realized prices, replacement timing, product mix, channel coverage, and geographic weights, with representation across company sizes and senior, functional, and managerial roles. Conflicting evidence would trigger targeted follow-up and comparison with independent shipment, production, and trade indicators, while remaining gaps would be carried as documented ranges for analyst review.
Distribution of primary research fieldwork respondents
| Company type | Respondent position | Region |
|---|---|---|
| Top tier: 34% | CXOs: 20% | APAC: 42% |
| Mid tier: 46% | Functional/Unit leaders: 39% | EMEA: 33% |
| Smaller Players: 20% | Managers: 41% | Americas: 25% |
Market-Sizing & Forecasting
Once the boundary is aligned to complete printer-device sales, a top-down estimate of global manufacturer hardware revenue is built and allocated across regions and device classes using shipment volumes, shipment value and average selling price mix, manufacturer printing disclosures, production data, and trade flows. These indicators distinguish changes in units from shifts toward higher-value devices and help derive regional and segment shares from observed revenue and shipment patterns. A selective bottom-up check multiplies sampled device volumes by observed hardware prices across major classes and compares the result with supplier and channel roll-ups. Where direct coverage is thin, regional shipment, production, and trade ratios provide bounded estimates for review. For 2027-2032, scenario analysis carries forward the observed revenue and shipment trends while varying printer replacement, ink-tank mix, production and label demand, and digital substitution, with primary respondents checking whether each variable's direction and timing fit procurement and channel conditions. When the segment and regional estimates are reconciled to the global total, unexplained gaps remain identified for review rather than being assigned to unsupported categories.
Data Validation & Update Cycle
Analysts triangulate the market estimate against independent shipment, sold-production, trade, and manufacturer revenue signals, then check outliers and year-to-year or regional variances against source definitions and reporting periods. After the initial reconciliation, a second analyst reviews boundary treatment, calculations, and material assumptions, and unresolved anomalies trigger source checks or respondent re-contact before sign-off. The evidence base is refreshed annually, updated between cycles when material events alter printer demand or supply, and given a fresh pre-delivery review.
Mordor Intelligence's Printer Market Estimate Compared With Other Published Estimates
Published estimates can differ in the transactions and products they count and the inputs used to model demand. The global printer market measures annual manufacturer revenue from complete printer hardware sold worldwide.
Key Gap Drivers include the study's defined coverage and market-specific modeling choices. Once the boundary is aligned to complete printer-device sales, a top-down estimate of global manufacturer hardware revenue is built and allocated across regions and device classes using shipment volumes, shipment value and average selling price mix, manufacturer printing disclosures, production data, and trade flows. These indicators distinguish changes in units from shifts toward higher-value devices and help derive regional and segment shares from observed revenue and shipment patterns.
Benchmark comparison
| Source | Market Size | Gaps in Research Methodology |
|---|---|---|
| Mordor Intelligence | USD 73.46 B (2027) | |
| Global Market Research Publisher A | USD 78.9 B (2025) | At its 2025 base, this estimate is 7.4% above this report's 2027 value of USD 73.46 B, 2 years later. Its published revenue taxonomy includes 3D printers as a separate printer type, broadening the product universe. |
| Global Market Research Publisher B | USD 54.5 B (2025) | At its 2025 base, this estimate is 25.8% below this report's 2027 value of USD 73.46 B, 2 years later. Its forecast follows a more moderate revenue path after its base year, contributing to a lower later-year estimate. |
Mordor Intelligence's analysts triangulate the market estimate against independent shipment, sold-production, trade, and manufacturer revenue signals, then check outliers and year-to-year or regional variances against source definitions and reporting periods.
Key Questions Answered in the Report
What is the printer market size and growth outlook?
It is projected to expand from USD 73.46 billion in 2027 to USD 90.67 billion by 2032, registering a 4.3% CAGR from 2027 to 2032.
What drives demand for printer equipment?
Parcel handling, ink-tank running-cost economics and short-run label production support demand. China’s express-delivery volume reached 199 billion items in 2025.
Which printer type has the largest share?
Multi-functional printers held a 60.4% share in 2026. Large-format printers are forecast to grow fastest at a 4.75% CAGR from 2027 to 2032.
Which companies compete in printer hardware?
Major participants include HP Inc., Canon Inc., Seiko Epson Corp., Brother Industries Ltd. and Xerox Corporation.
How does digitization affect the outlook for printer suppliers?
Digital substitution can weaken transactional printing requirements. Checks accounted for 26% of B2B payments made by surveyed US and Canadian organizations in 2025, down 7 percentage points from 2022.
Which region leads printer equipment sales and growth?
Asia-Pacific held a 41.32% share in 2026 and is forecast to grow fastest at a 4.8% CAGR from 2027 to 2032.