Power Tools Market Size and Share
Power Tools Market Analysis by Mordor Intelligence
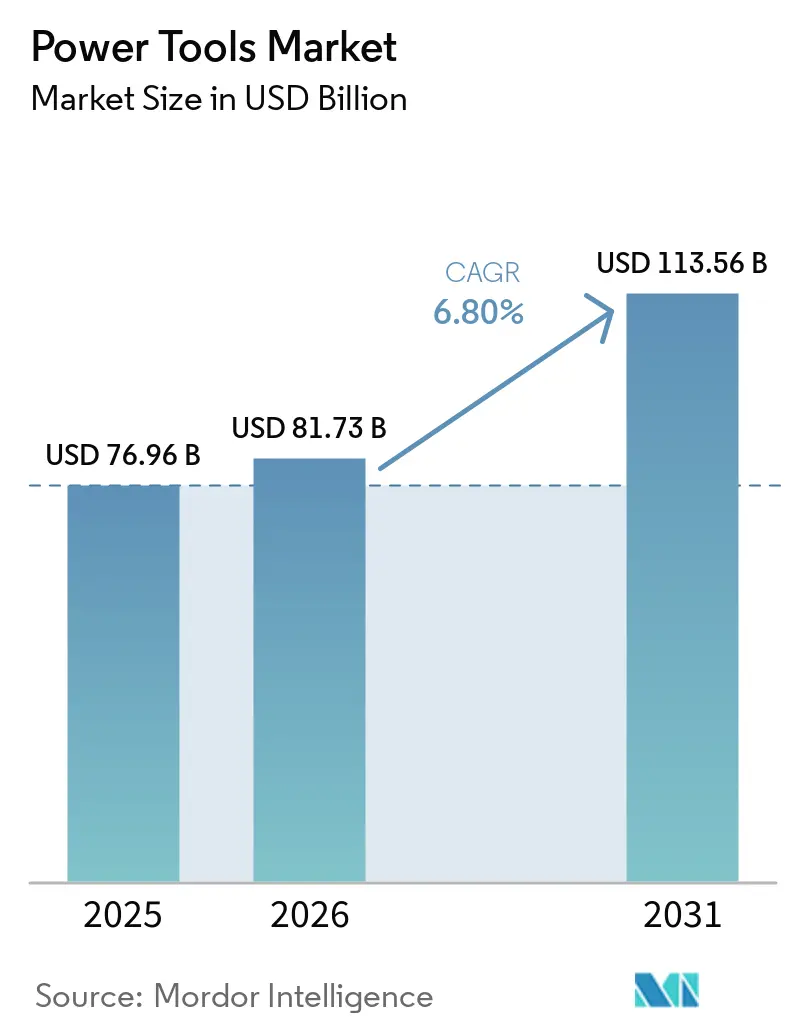
The power tools market size is projected to expand from USD 81.73 billion in 2026 and USD 87.29 billion in 2027 to USD 119.9 billion by 2032, registering a CAGR of 6.55% between 2027 and 2032.
Infrastructure investment in India and semiconductor construction in the United States create installation work, while cordless platforms extend battery operation into demanding construction tasks. Suppliers can address project requirements and equipment replacement through specialized tools, professional performance tiers and household offerings. Construction labor constraints complicate the conversion of that opportunity into sales, as do the Democratic Republic of the Congo's cobalt export quotas, introduced in October 2025 to replace a temporary export ban, which add uncertainty to battery input costs and supply. Sales therefore follow how quickly funded projects and available crews turn planned construction into purchases, with battery input costs shaping the price of cordless kits.
Key Report Takeaways
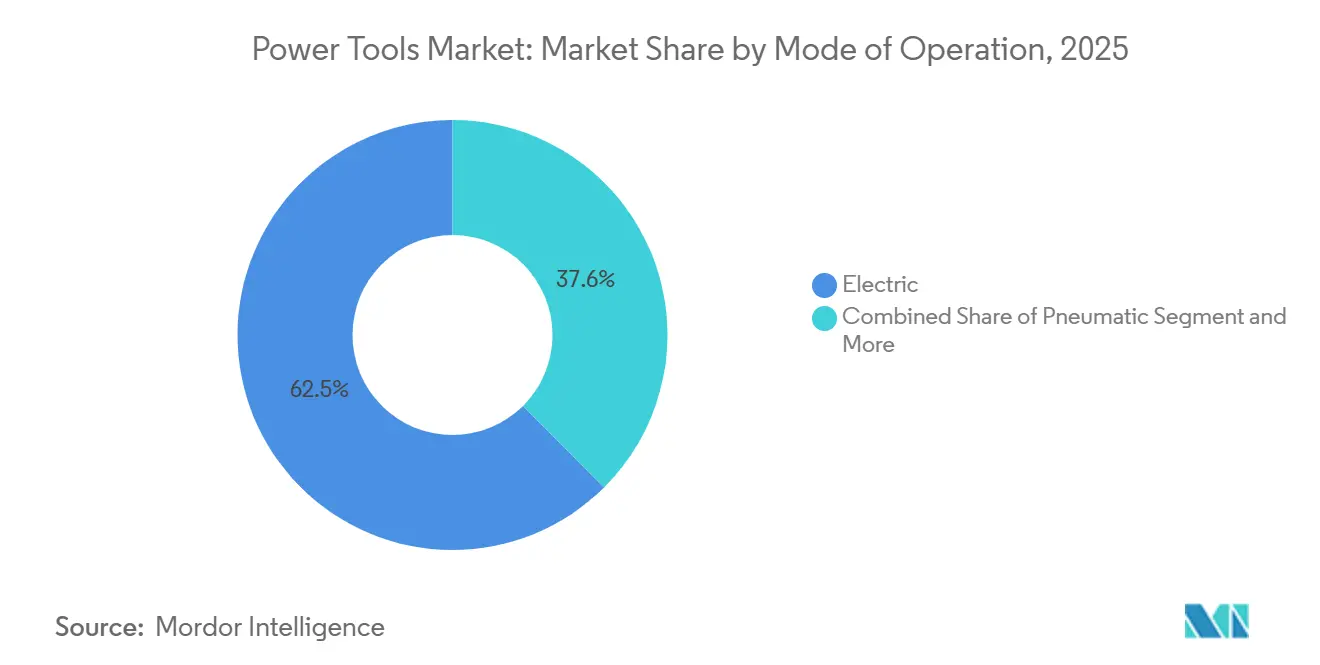
- By mode of operation, electric tools held a 62.78% power tools market share in 2026 and are forecast to lead growth at a 7.15% CAGR between 2027 and 2032.
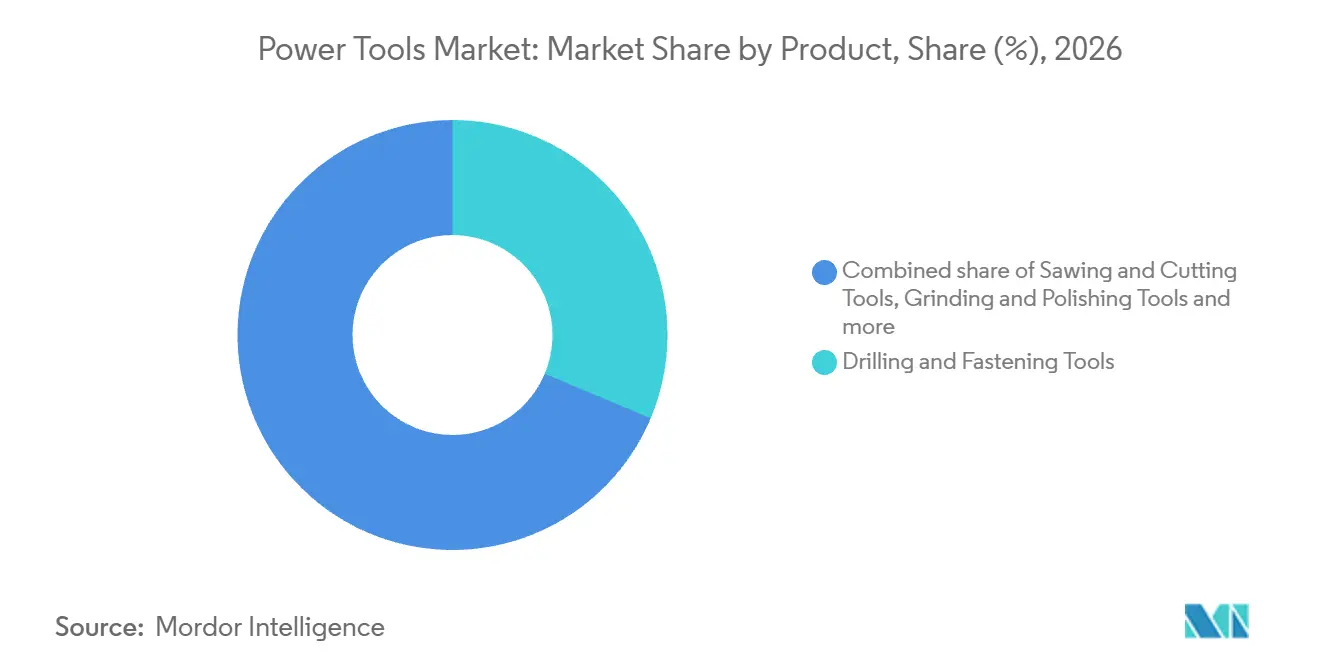
- Among product categories, drilling and fastening tools accounted for a 31.33% share of the power tools market size in 2026, while impact drivers and wrenches are forecast to grow fastest at a 7.8% CAGR between 2027 and 2032.
- Construction and infrastructure led end-user demand with a 45.74% share in 2026, while residential and DIY use is forecast to grow fastest at a 7.9% CAGR between 2027 and 2032.
- Across sales channels, offline sales led with a 78.62% share in 2026, whereas online sales are forecast to grow fastest at a 7.85% CAGR between 2027 and 2032.
- Geographically, Asia-Pacific held the largest share at 39.23% in 2026 and is forecast to grow fastest at a 7.6% CAGR between 2027 and 2032.
Note: Market numbers in this report are based on Mordor Intelligence's proprietary estimation framework, which combines nine months of actuals with Q4 projections for base year 2026.
Market Trends and Insights
Drivers Impact Analysis of Power Tools Market*
| Driver | (~) % Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
|---|---|---|---|
| Surging Public-Infrastructure Capex in India & Tier-2/3 City Projects Lifting Pro-Tool Demand | +2.2% | India's Tier-II and Tier-III cities | Medium term (2-4 years) |
| CHIPS-Act Semiconductor Megafab Build-outs in US Requiring High-Precision Installation Tools | +1.5% | Semiconductor construction sites in the United States | Long term (≥ 4 years) |
| Rapid Electrification of Heavy Construction Fleets Accelerating Shift to High-Voltage Cordless Platforms | +2.7% | North America and Europe | Medium term (2-4 years) |
| Job-Site Productivity Gains from AI-Enabled Smart Tools Expected to Drive Contractor Upgrades | +1.3% | North American industrial installation sites | Long term (≥ 4 years) |
| Government-Funded Hi-Tech Tool Rooms in India Catalyzing Indigenous Precision-Tool Manufacturing | +0.3% | Technology centers across India | Long term (≥ 4 years) |
| Community-Centric Construction Wave in Indonesia's Nusantara (Multi-Faith Complexes, Civic Amenities) Spurring Specialty Finishing-Tool Sales | +0.2% | Nusantara civic construction sites | Medium term (2-4 years) |
| Source: Mordor Intelligence | |||
Surging Public-Infrastructure Capex in India & Tier-2/3 City Projects Lifting Pro-Tool Demand
India budgeted higher public capital expenditure for FY2026-27 than the FY2025-26 revised estimate.[1] The Urban Challenge Fund was designed to mobilize nearly INR 4 trillion (USD 42.83 billion) through market-based financing. Its credit-guarantee sub-scheme supports smaller cities, including Tier-II and Tier-III cities, in accessing that financing. Central assistance is limited to 25% of project cost, while at least 50% of funding is to be mobilized through municipal bonds, bank loans and public-private partnerships. For professional-tool suppliers, this structure connects a broader pool of urban projects with prospective demand for construction and installation equipment. The commercial opening therefore depends on projects securing their financing, since a larger allocation becomes tool demand only when funded work proceeds.
CHIPS-Act Semiconductor Megafab Build-outs in US Requiring High-Precision Installation Tools
Semiconductor construction connects professional-tool demand to precision work across interconnected utility and building systems. The CHIPS Program Office awarded Micron funding through Micron New York Semiconductor Manufacturing LLC for the first 2 fabs in its planned 4-fab Clay complex for leading-edge DRAM production. Following the January 2026 groundbreaking in New York, Bechtel is delivering engineering, procurement and construction services for the initial fab and critical campus infrastructure. The work spans cleanroom systems, advanced electrical and mechanical systems, vibration-sensitive foundations and tightly controlled manufacturing environments. For tool suppliers, accessible demand follows the execution of these construction packages before semiconductor production begins, making progress through the build a more immediate commercial trigger than future chip output.
Rapid Electrification of Heavy Construction Fleets Accelerating Shift to High-Voltage Cordless Platforms
Heavy-duty cordless substitution becomes commercially tangible when rental fleets order battery equipment for construction work. After a November 2024 wet-concrete trial in Sweden, Skanska Rental ordered Milwaukee MX FUEL battery equipment, including cut-off saws, then ordered additional trowels about a year later. Hilti expanded its 22-volt Nuron platform with more than 60 heavy-duty tools and accessories, with initial launches beginning in Q4 2025. The additions covered breaking, concrete cutting, wood cutting and soil compaction, extending cordless capabilities into work traditionally served by corded or gas-powered equipment. Rental-fleet purchases can spread demand for these cordless tools across successive hires, creating sales opportunities beyond contractors equipping their own crews.
Job-Site Productivity Gains from AI-Enabled Smart Tools Expected to Drive Contractor Upgrades
Contractors considering intelligent tools need a work-specific reason to replace equipment that is mechanically usable. In its 2025 ESG report, Techtronic Industries Co. Ltd. (TTI) describes machine learning and AI in Milwaukee's M18 FUEL 7-1/4-inch circular saw with ONE-KEY. TTI says its AUTOSTOP Advanced Kickback Protection detects sudden bind-ups and automatically shuts off power, reducing kickback risk while maintaining productivity. TTI frames the feature as lowering kickback risk without reducing productivity, so the case for replacing a working saw rests on safer cuts at maintained output rather than on added power. That gives contractors a task-specific reason to retire a serviceable saw ahead of wear-out, with the trigger depending on how often crews face binding cuts.
Restraints Impact Analysis of Power Tools Market*
| Restraint | (~) % Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
|---|---|---|---|
| Cobalt-Price Spikes from DRC Export Quotas Inflating Li-ion Battery Pack Costs | -0.7% | Democratic Republic of the Congo and China | Short term (≤ 2 years) |
| Skilled-Labor Shortages at North-American Megafab Sites Causing Build Delays and Tool Fleet Idle Time | -0.6% | Construction sites across the United States | Medium term (2-4 years) |
| Stricter Hand-Arm Vibration Exposure Limits Rolling Out Across ASEAN Curbing Heavy-Duty Tool Adoption | -0.2% | Workplaces across Indonesia | Long term (≥ 4 years) |
| Fiscal Tightening & Political Apathy Slowing Indonesia's Nusantara Megaproject, Dampening Regional Tool Demand | -0.3% | Nusantara construction sites | Short term (≤ 2 years) |
| Source: Mordor Intelligence | |||
Cobalt-Price Spikes from DRC Export Quotas Inflating Li-ion Battery Pack Costs
The Democratic Republic of the Congo's temporary cobalt export ban, announced in February 2025 to protect national economic interests, gave way to quotas on October 16, 2025. Benchmark's cobalt hydroxide CIF Asia assessment stood at USD 17.25 per pound at the close of Q3 2026, against its mid-February 2025 delivered-to-China reading of USD 5.65 per pound, even after a 31% quarterly decline. DRC customs processes and quota implementation nevertheless remained a swing factor for cobalt inflows into China at quarter-end. LG Energy Solution includes nickel-cobalt-manganese chemistry among its materials for power-tool batteries. Battery suppliers using that chemistry therefore face exposure to material prices and supply timing that may move independently of finished-tool demand. The remaining constraint is uncertainty over material availability and cost, which can complicate pricing of new tools supplied with batteries even after benchmark prices ease.
Skilled-Labor Shortages at North-American Megafab Sites Causing Build Delays and Tool Fleet Idle Time
Construction-worker shortages constrain the timing of equipment demand when crews cannot complete the work needed to release later project stages. In AGC and NCCER's July-August 2026 U.S. construction-firm survey, 42% of respondents reported project delays caused by shortages of their own or subcontractors' workers. For a megafab contractor, a delayed work package can postpone the next trade's opportunity to use its tools. Tools already available for that later stage can consequently deliver fewer productive work hours while the sequence is blocked. Even where the eventual construction requirement holds, the immediate commercial effect can be deferred additions to tool fleets and a longer wait before equipment generates useful work.
*Our forecasts treat driver/restraint impacts as directional, not additive. The impact forecasts reflect baseline growth, mix effects, and variable interactions.
Power Tools Market Segment Analysis
By Mode of Operation:
Electric Readiness Meets Commercial ExpansionElectric tools accounted for a 62.78% share of the power tools market size in 2026 and are forecast to register a 7.15% CAGR between 2027 and 2032, making them the largest and fastest-growing segment. DEWALT's 2025 survey found 94% of surveyed U.S. concrete and masonry construction workers were confident their sites were adequately fitted for the transition to fully electric-powered tools. Such confidence lowers the perceived site-readiness barrier for buyers evaluating electric replacements within concrete and masonry work. The commercial opportunity centers on converting that readiness into purchases when existing equipment reaches a replacement decision.
For the fiscal year ended March 31, 2026, Makita reported 1.5% year-on-year growth in Oceania revenue, attributing the result to expanded cordless-product sales focused on its XGT series. That regional business covers power tools and outdoor power equipment. Makita achieved the increase amid a sluggish construction and building market in Oceania.

By Product:
Installation Breadth and Field-Service DemandDrilling and fastening tools represented a 31.33% power tools market share in 2026, making them the largest product segment. A cordless drill-driver combines hole preparation and screw installation, allowing a contractor to handle successive installation steps with one powered tool. Where both operations recur, that dual use can spread the equipment cost across more tasks than a dedicated tool covers. A contractor can therefore justify the initial purchase through repeated installation work before needing a wider range of specialized equipment.
Impact drivers and wrenches are forecast to register a 7.8% CAGR between 2027 and 2032, making them the fastest-growing product segment. VMAC's 2026 North American survey found pneumatic impact wrenches were the most-used pneumatic tool among mobile-service respondents. TTI describes Milwaukee's M18 FUEL Controlled Torque Compact Impact Wrench with ONE-KEY as using AI sensors and machine learning to learn from past use and control bolt tightness. Sawing and cutting tools also have a mobile-service application, with pneumatic saws appearing in the same survey. For buyers needing repeatable bolt installation, controlled tightening offers a reason to upgrade before mechanical failure, adding a demand trigger beyond equipping existing field-service work.
By End-user:
Construction Scale and Consumer Brand GrowthConstruction and infrastructure held a 45.74% share in 2026, making it the largest end-user segment. The U.S. Census Bureau estimated total construction spending in the United States at USD 2.17 trillion in 2025.[2] On November 12, 2025, UK construction contractor Knights Brown said it had entered a strategic partnership with Hilti to equip its teams with a new fleet of cordless tools. Such an agreement brings teams' equipment needs into a supplier relationship, giving construction buyers a fleet-level way to equip crews as projects require.
Residential and DIY use is forecast to register a 7.9% CAGR between 2027 and 2032, making it the fastest-growing end-user segment. TTI serves DIY users through its RYOBI brand. RYOBI Power Tools sales rose by a mid-single-digit percentage in the first half of 2026.
By Sales Channel:
Dealer Reach and Digital Trade SalesOffline sales held a 78.62% share in 2026, making offline the largest sales channel. In FY2025-26, Bosch Limited's Power Tools Division reached more than 20,000 Indian retail outlets through 2,000 dealers, using digital tools and traditional outreach for new launches. That dealer-led structure links product introductions to a large retail network within India, giving suppliers multiple points of contact with local trade. Dealer coordination can extend a manufacturer's launch across many outlets through a smaller set of relationships, making retail reach a practical advantage of this route.
Online sales are forecast to register a 7.85% CAGR between 2027 and 2032, making online the fastest-growing sales channel. In the 6 months ended July 31, 2026, Kingfisher's Screwfix e-commerce sales grew 7.5% in constant currency and accounted for 60% of its total sales. These figures cover Screwfix's retail range of tools and other products. For digital tool sellers, a route handling that much retail activity provides an established setting for reaching trade buyers. Success then depends on visibility and conversion within that established route, where tool offers compete alongside the retailer's wider assortment.
Geography Analysis
Asia-Pacific Power Tools Market
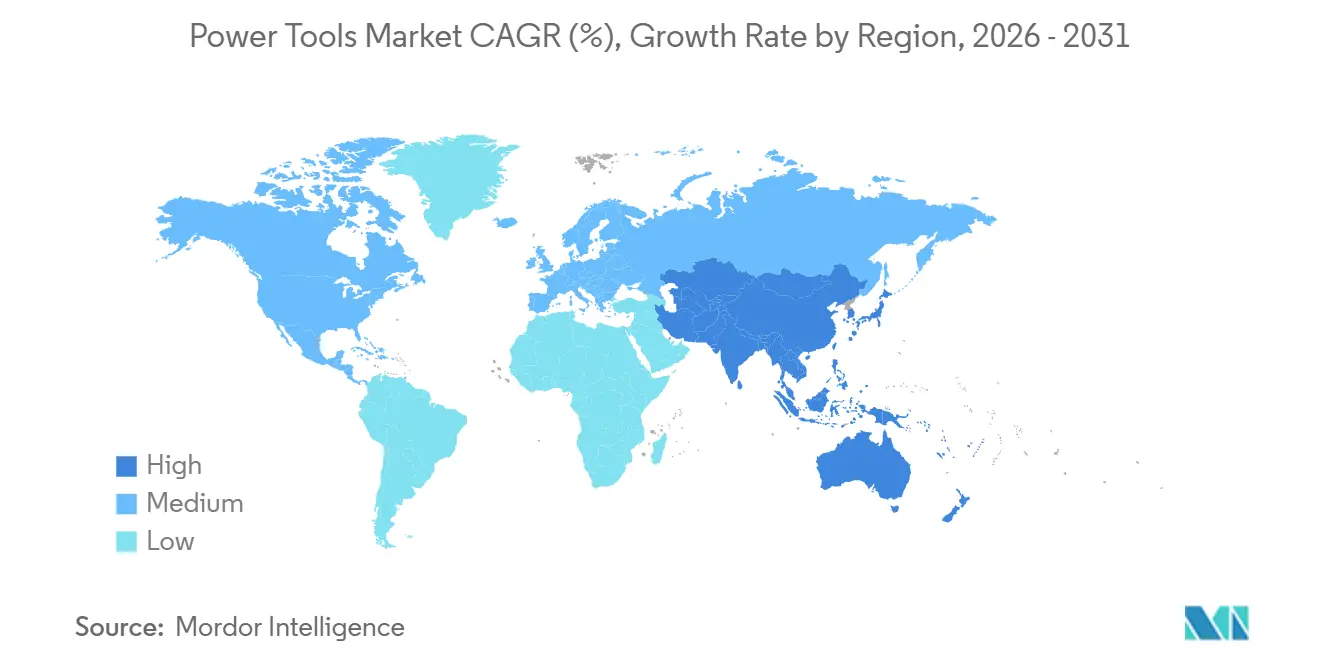
Asia-Pacific accounted for a 39.23% share of the power tools market size in 2026 and is forecast to register a 7.6% CAGR between 2027 and 2032, making it the largest and fastest-growing region. A 2025 NITI Aayog report put India's power-tool exports at USD 425 million. On April 16, 2025, the Asian Development Bank approved USD 1.45 billion as the final financing tranche for the Philippines' 53.1-kilometer Malolos-Clark Railway. Taiwan reported fewer residential units starting construction in 2025 than in 2024. India's power-tool exports and the financing of the Philippines' Malolos-Clark Railway are examples of supply and demand activity in the region, from export manufacturing to publicly financed rail construction.
In North America, Stanley Black & Decker attributed its Tools & Outdoor segment's 3% organic revenue growth in Q2 2026 primarily to power-tool strength in U.S. retail and commercial and industrial channels. That combination makes both consumer-facing and industrial routes relevant to suppliers seeking access to the country's tool users. In Europe, EU civil-engineering investment grew 3.8% in 2025 with transport, energy and water infrastructure investment and public funding, while Poland issued more building permits in 2025 than in 2024. The resulting commercial priorities differ, with U.S. channel execution connecting suppliers to demonstrated demand and EU infrastructure programs directing attention toward the contractors executing funded construction work.
In South America, Brazil's National Index of Civil Construction rose 5.63% in 2025, while Uruguay's 2025-29 budget, effective from January 1, 2026, prioritizes road rehabilitation and railway modernization. Brazil's higher project costs make tool productivity commercially relevant when equipment can reduce the time needed to complete construction tasks. The Middle East and Africa include Saudi Arabia, where the Saudi Contractors Authority counted 365,120 construction-sector establishments in 2025, while Kenya's construction activity returned to growth in 2025 after contracting in 2024. Saudi Arabia's extensive business base creates a potential customer pool extending beyond the contractors involved in a few prominent projects. Suppliers serving Saudi contractors therefore face a challenge of account reach, while a Brazilian proposition gains relevance when it demonstrates a credible reduction in work time.
Regulatory Framework and Outlook
This comparison of selected jurisdictions assesses suppliers of professional portable electric tools serving workplace buyers. The United Kingdom column covers Great Britain's machinery regime, where covered goods may use CE or UKCA marking subject to applicable safety and conformity-assessment conditions. Workplace-use duties, product certification with surveillance and conditional machinery-rule exclusions create different commercial obligations for suppliers and their customers.
Regulatory Table of Power Tools Market
| Decision factor | United States | United Kingdom | China | Brazil | South Africa |
|---|---|---|---|---|---|
| Primary authority | Occupational Safety and Health Administration | Health and Safety Executive for workplace use in Great Britain, with specified railway exceptions | Certification and Accreditation Administration of China | Ministry of Labor and Employment | Department of Employment and Labour |
| Key instruments or direction | 29 CFR 1910.243(a)(5), general-industry portable electric tools | Supply of Machinery (Safety) Regulations 2008, Great Britain | Trial CNCA-C05-01:2026, effective July 1, 2026 for listed electric drills, grinders and hammers | NR-12, item 12.1.4(e), conditional portable and transportable electric-tool exclusion | Electrical Machinery Regulations 2011, regulation 10(1), portable tools above 50 V to earth |
| Commercial effect | Covered employers must meet the applicable electrical requirements for portable electric tools | Applicable safety and conformity conditions govern the CE or UKCA marking route | Covered products require type testing, initial factory inspection and post-certification surveillance | Exclusion requires applicable national type-C construction standards, including general and specific parts, or applicable international type-C standards where national standards are absent | Use above 50 V to earth is conditional on a specified protection route, including standards-compliant earth-leakage protection or clear double/reinforced-insulation marking |
| Current policy attractiveness | Medium | High | Low | High | Medium |
| Future direction of policy attractiveness | No change | No change | No change | No change | No change |
| Source: Mordor Intelligence | |||||
Workplace electrical duties in the United States and China's operative certification process favor continuity, with the initial testing and ongoing surveillance burden lowering China's attractiveness for covered tool lines. Great Britain's indefinite CE recognition supports its higher rating, while the government's announced intention to update machinery rules represents a planned direction rather than an implemented new requirement. Brazil's conditional NR-12 exclusion favors qualifying tools, with the ongoing need to meet applicable type-C standards underpinning continuity in that commercial position. South Africa's voltage-triggered conditions support its medium rating and continuity judgment, because the 2025 General Machinery consultation addressed a separate regime from this portable-tool rule.
Value Chain Stages
The value chain compares how battery suppliers, tool producers, retail partners and repair operators capture revenue and manage different operational constraints. Stanley Black & Decker reported component delays and shortages resulting from China's April 2025 export restrictions on certain rare-earth minerals used in its product components. That exposure makes access to qualified components a separate resilience problem from the location of final tool production.
Value Chain Analysis Table of Power Tools Market
| Primary activity | Key participants | Value capture | Bottleneck | Resilience response |
|---|---|---|---|---|
| Battery-component supply | Battery suppliers such as LG Energy Solution and Samsung SDI | Cell, module and pack sales | Qualification of replacement battery designs | Validate alternative cell and pack designs before substitution |
| Tool production and brand supply | Power-equipment manufacturers such as Techtronic Industries Vietnam Manufacturing Company Limited; branded-tool producers such as Stanley Black & Decker | Newly built tool sales | Availability of qualified critical components | Qualify alternative component suppliers and designs |
| Retail distribution | Retail partners such as The Home Depot in North America and Bunnings in Australia and New Zealand | Retail margins on tool sales | Dependence on regional channel coverage | Develop additional routes to underserved buyers |
| Tool repair | Manufacturer repair services such as Milwaukee Tool | Repair and maintenance fees | Access to skilled repair capacity | Combine factory repair capability with authorized service partners |
| Source: Mordor Intelligence | ||||
Over several years through 2025, Milwaukee expanded production in Vietnam, Mexico and the United States to strengthen regional operational flexibility. Such diversification can widen fulfillment options, while component qualification determines whether upstream substitutions are technically feasible. Milwaukee Tool provides repairs through factory service centers and authorized service partners in the United States. Together, manufacturing flexibility and repair access make operational support part of the producer's commercial offering beyond the initial tool sale.
Competitive Landscape
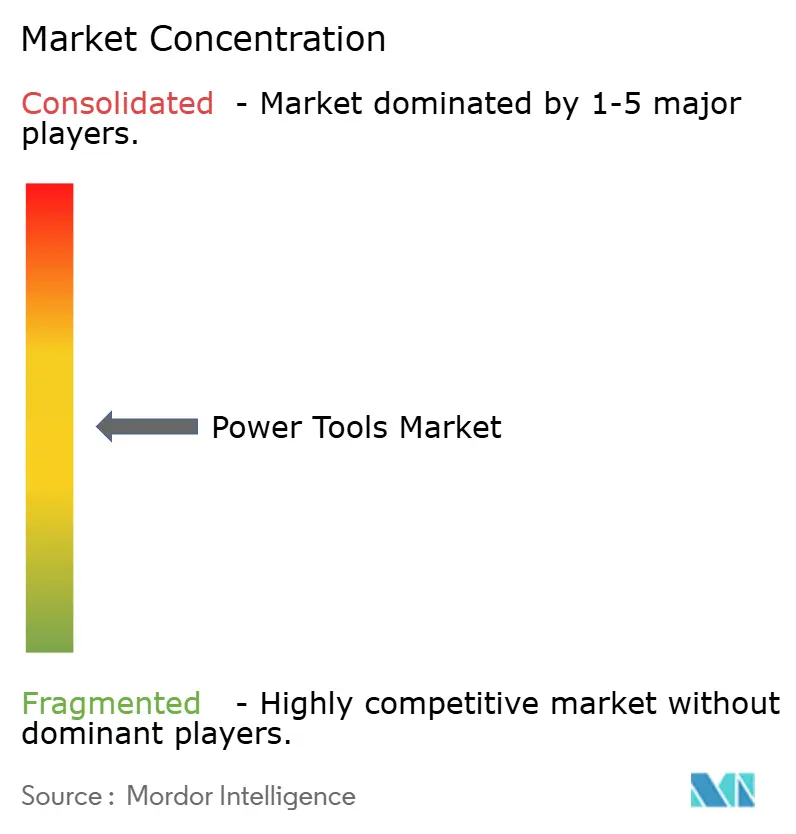
Competition centers on a moderately concentrated group of established international suppliers, with room for challengers focused on particular applications. Major suppliers include Stanley Black & Decker Inc., Robert Bosch GmbH, Techtronic Industries Co. Ltd., Makita Corporation and Hilti Corporation. Stanley Black & Decker's global Tools & Outdoor segment recorded USD 13.16 billion in net sales in 2025, down 1% from 2024.[3] TTI's Power Equipment segment generated USD 14.4 billion in sales in 2025, up 5.3% in reported currency. These broader businesses span multiple user groups, leaving specialists an opening around particular tool applications without requiring full-portfolio leadership.
In 2025, Bosch announced that its Expert line would expand into power tools and measuring technology from 2026, and introduced a Dremel tool line for DIY users. Makita's 2025 strategy report positioned its 40Vmax cordless line for heavy-load work typically handled by engine-powered or other products. Bosch's approach separates professional performance tiers from its DIY offering, allowing different propositions to address distinct users without relying on a single feature. Makita's positioning sets engine-powered equipment as the benchmark its cordless line must match in heavy-load work.
The next competitive hurdle is demonstrating that new capabilities solve defined work problems while satisfying the requirements of each destination market. Hilti launched more than 70 new products and services in 2025, reflecting the breadth of its development activity. Bosch Group's product-compliance system is designed to satisfy regulatory requirements relevant to its products in each market. Such systems make the ability to support compliance a complementary capability to hardware development for suppliers pursuing sales across jurisdictions. A specialist challenging these portfolios therefore needs a substantiated advantage in a particular task and the ability to carry that product through the applicable compliance process.
Power Tools Industry Leaders
-
Stanley Black & Decker Inc.
-
Robert Bosch GmbH
-
Techtronic Industries Co. Ltd.
-
Makita Corporation
-
Hilti Corporation
- *Disclaimer: Major Players sorted in no particular order
Power Tools Market Companies Covered in this Report
- Stanley Black & Decker Inc.
- Robert Bosch GmbH
- Techtronic Industries Co. Ltd.
- Makita Corporation
- Hilti Corporation
- Atlas Copco AB
- Ingersoll Rand Inc.
- Snap-on Incorporated
- Apex Tool Group
- Emerson Electric Co.
- Husqvarna AB
- Honeywell International Inc.
- KYOCERA Corporation
- Festool GmbH
- Cummins Inc. (Tool segment)
- Koki Holdings Co., Ltd. (HiKOKI)
- Illinois Tool Works (ITW)
- Ridgid (Emerson)
- Baier Power Tools
- Positec Tool Corporation
- Panasonic Life Solutions
- CEMBRE S.p.A.
- CSUN Power Tools
Key Opportunities for Market Participants
The opportunities compare household screwdriver sales, specialist concrete-work tools and new-tool supply to rental fleet operators. In January 2026, DEWALT made its DCN910B cordless duplex nailer available in the United States for concrete forming, temporary bracing and scaffolding. DEWALT positioned it as the industry's lightest battery-powered duplex nailer on a tool-only basis. This provides a defined professional application around which suppliers can build a more specific proposition than a general cordless-tool expansion.
Market Opportunities Table of Power Tools Market
| Opportunity | Why now | Buyer / lead segment | Recommended play | Main barrier | Likely beneficiaries |
|---|---|---|---|---|---|
| Compact household screwdrivers through mass retail | Bosch launched IXO and PSR-SELECT at Lowe's in September 2026 as a limited release while supplies last | U.S. household and DIY users | Develop focused screwdriver assortments for recurring household tasks | Securing repeat retail placement beyond a limited release | Bosch and Lowe's |
| Cordless duplex fastening for concrete work | Available cordless tool addresses forming, temporary bracing and scaffolding | U.S. construction and infrastructure contractors | Offer an explicitly specified tool and operating configuration | Battery, charger and compatible DEWALT DN275 8D or DN350 16D collated duplex nails are sold separately | Stanley Black & Decker through DEWALT |
| New-tool capacity for peak-demand rental fleets | Hilti's Fleet Management includes short-term tool rentals for peak demand | Rental fleet operators serving contractors | Supply newly built tools against justified additions to fleet capacity | Utilization must justify adding owned units | Tool producers serving rental fleets, including Hilti |
| Source: Mordor Intelligence | |||||
Specialist construction fastening offers the clearest opening because the equipment addresses defined professional tasks. Its commercial case depends on the complete working configuration, since the nailer requires separately sold batteries, a charger and compatible DEWALT collated duplex nails. Suppliers can make that decision easier by specifying the complete configuration alongside the tool, enabling contractors to assess task coverage and initial outlay together.
Recent Industry Developments in Power Tools Market
- Sep 2026: Bosch Power Tools launched its IXO and PSR-SELECT cordless screwdrivers for household tasks at Lowe's stores in the United States as a limited release while supplies last.
- Jul 2026: Hilti made the first of the more than 60 new heavy-duty Nuron products and accessories available in Germany.
- Jun 2026: Bosch Power Tools launched 39 new tools and accessories in North America for trade and construction work.
Power Tools Market Report Scope and Research Methodology
Market Definition and Coverage
Global power tools market measures annual spending on newly built hand-held and stationary powered tools for professional, industrial, commercial, and residential work. It covers tools powered by electricity, compressed air, hydraulic systems, or small engines, with batteries or motors shipped as part of a tool counted with that tool.
Scope exclusions: Rental revenue, stand-alone accessories, aftermarket parts, and medical or surgical powered instruments are excluded.
Segments Covered in This Report
- By Mode of Operation
- Electric
- Cordless
- Corded
- Pneumatic
- Hydraulic
- Engine-Driven
- Electric
- By Product
- Drilling & Fastening Tools
- Sawing & Cutting Tools
- Grinding & Polishing Tools
- Material Removal Tools (sanders, etc.)
- Demolition Tools (Breakers, Jackhammers)
- Impact Drivers & Wrenches
- Nailers & Staplers
- Others (heat guns, glue guns, mixers, specialty tools)
- By End-user
- Construction & Infrastructure
- Automotive
- Aerospace & Defense
- Energy & Power Generation
- Shipbuilding, Marine & Railways
- Manufacturing (Electronics, Metalworking, Wood Work, etc.)
- Residential / DIY
- Others (Utilities, Mining, etc.)
- By Sales Channel
- Offline
- Direct Industrial/ Distributor
- Mass Retail / Home Centers
- Online
- E-commerce Marketplaces
- Brand-Owned Digital Stores
- Offline
- By Geography
- North America
- United States
- Canada
- Mexico
- South America
- Brazil
- Argentina
- Peru
- Rest of South America
- Europe
- United Kingdom
- Germany
- France
- Italy
- Spain
- BENELUX (Belgium, Netherlands, and Luxembourg)
- NORDICS (Denmark, Finland, Iceland, Norway, and Sweden)
- Rest of Europe
- Asia-Pacific
- China
- India
- Japan
- Australia
- South Korea
- ASEAN (Indonesia, Thailand, Philippines, Malaysia, Vietnam)
- Rest of Asia-Pacific
- Middle East and Africa
- Saudi Arabia
- United Arab Emirates
- Qatar
- Kuwait
- Turkey
- Egypt
- South Africa
- Nigeria
- Rest of Middle East and Africa
- North America
Data Sources, Market Sizing, and Validation
Desk Research
Public sources such as the U.S. Census Bureau's construction spending estimates, NITI Aayog's India tools-sector report, the Occupational Safety and Health Administration's portable-tool requirements, the European Commission's machinery guidance, and the Bureau of Labor Statistics' construction productivity series help track project activity, trade context, operating requirements, and demand conditions across the market. These indicators inform the assessment of construction and industrial demand, regional context, product requirements, and the timing of replacement purchases.
Company annual results and investor materials, including Stanley Black & Decker's Tools & Outdoor reporting, help cross-check producer revenue trends and channel or product commentary, while reputable business reporting can clarify material events and market developments. These sources are illustrative and are not exhaustive, and further sources inform collection, validation and clarification.
Primary Interviews and Surveys
Interviews and structured surveys can include power-tool manufacturers and brand owners, distributors and dealers, professional contractors, industrial purchasing teams, and commercial or residential buyers across APAC, EMEA, and the Americas. Respondents can test secondary findings on product mix, channel movement, replacement timing, price and application demand, while helping explain differences between public indicators and reported business conditions. When public evidence conflicts or leaves a material gap, respondent follow-up can clarify the relevant assumption and support triangulation against independent company, trade, construction, and manufacturing evidence.
Distribution of primary research fieldwork respondents
| Company type | Respondent position | Region |
|---|---|---|
| Top tier: 30% | CXOs: 20% | APAC: 40% |
| Mid tier: 45% | Functional/Unit leaders: 35% | EMEA: 35% |
| Smaller Players: 25% | Managers: 45% | Americas: 25% |
Market-Sizing & Forecasting
The estimate starts with a top-down view of global manufacturer and brand-owner sales of newly built power tools, then checks selected totals through supplier roll-ups and sampled average selling price multiplied by unit volume. Useful indicators include construction spending and project activity, industrial production and maintenance demand, power-tool producer revenue trends, tool shipment or trade patterns, and the mix of cordless versus corded products. Together these indicate demand, supply and price or product-mix movement. Historical relationships among these indicators and market value can inform a multivariate regression. When project timing, battery adoption or input-cost conditions create materially different paths, scenario analysis can represent the alternatives. Product, operating-mode, end-user, channel and regional shares are built from the distribution of relevant tool sales and checked so that each partition reconciles with the global value, and gaps in supplier or channel evidence are bounded with comparable company disclosures and trade signals. Primary respondents can examine the reasonableness of variable-level assumptions and explain material departures, while unresolved gaps remain explicit inputs for analyst review rather than being filled with unsupported detail.
Data Validation & Update Cycle
Analysts triangulate company disclosures, trade and construction indicators, regulatory information, and respondent evidence, checking each signal against the market boundary and its measurement period. They investigate outliers, inconsistent growth or share movements, and differences between supplier, channel, and demand indicators, then document the supported explanation before sign-off through analyst review and an independent editorial check. Re-contact is appropriate when a material assumption remains inconsistent, a respondent's scope is unclear, or a new event changes the interpretation of a key input. The dataset is refreshed annually, updated between cycles after material market events, and given a fresh pre-delivery review.
Mordor Intelligence's Power Tools Market Size Compared With Other Published Estimates
Published estimates can differ in the transactions and products they count and the inputs used to model demand. Global power tools market measures annual spending on newly built hand-held and stationary powered tools for professional, industrial, commercial, and residential work.
Key Gap Drivers include the study's defined coverage and market-specific modeling choices. Useful indicators include construction spending and project activity, industrial production and maintenance demand, power-tool producer revenue trends, tool shipment or trade patterns, and the mix of cordless versus corded products.
Benchmark comparison
| Source | Market Size | Gaps in Research Methodology |
|---|---|---|
| Mordor Intelligence | USD 87.29 B (2027) | |
| Global Consultancy A | USD 46.84 B (2025) | At its 2025 base, this estimate is 46.3% below this report's 2027 value of USD 87.29 B, 2 years later. Its published estimate uses an earlier base year, and its stated forecast rate is slightly below the rate used for the approved period. |
| Industry Research Publisher B | USD 35.5 B (2025) | At its 2025 base, this estimate is 59.3% below this report's 2027 value of USD 87.29 B, 2 years later. Its estimate uses an earlier base year, while its higher stated forecast rate partially narrows the gap by the later comparison year. |
Mordor Intelligence's analysts triangulate company disclosures, trade and construction indicators, regulatory information, and respondent evidence, checking each signal against the market boundary and its measurement period.
Key Questions Answered in the Report
What is the power tools market size and growth outlook?
The size is projected to rise from USD 87.29 billion in 2027 to USD 119.9 billion by 2032, registering a CAGR of 6.55% between 2027 and 2032.
What is driving demand for professional power tools?
Higher budgeted public capital expenditure in India for FY2026-27 and CHIPS-supported semiconductor construction in the United States create opportunities for professional tools.
Which power-tool product category has the largest share?
Drilling and fastening tools led product sales with a 31.33% share in 2026.
Which companies are major power-tool suppliers?
Major suppliers include Stanley Black & Decker Inc., Robert Bosch GmbH, Techtronic Industries Co. Ltd., Makita Corporation and Hilti Corporation.
What could constrain growth in cordless and professional tools?
Worker shortages delayed projects for 42% of respondents in the July-August 2026 U.S. construction-firm survey, while DRC cobalt quota implementation adds input-supply uncertainty.
Which region leads power-tool sales and growth?
Asia-Pacific held a 39.23% share in 2026 and is forecast to grow fastest at a 7.6% CAGR between 2027 and 2032.