
Market Overview
| Study Period | 2019 - 2032 |
|---|---|
| Forecast Data Period | 2027 - 2032 |
| Base Year Market Size (2026) | USD 1.96 Billion |
| Market Size (2027) | USD 2.30 Billion |
| Market Size (2032) | USD 5.09 Billion |
| Growth Rate (2027 - 2032) | 17.22 % |
| Market Concentration | Low |
Major Players *Disclaimer: Major Players sorted in no particular order Image © Mordor Intelligence. Reuse requires attribution under CC BY 4.0. | |
North America Agricultural Robots and Mechatronics Market Analysis by Mordor Intelligence
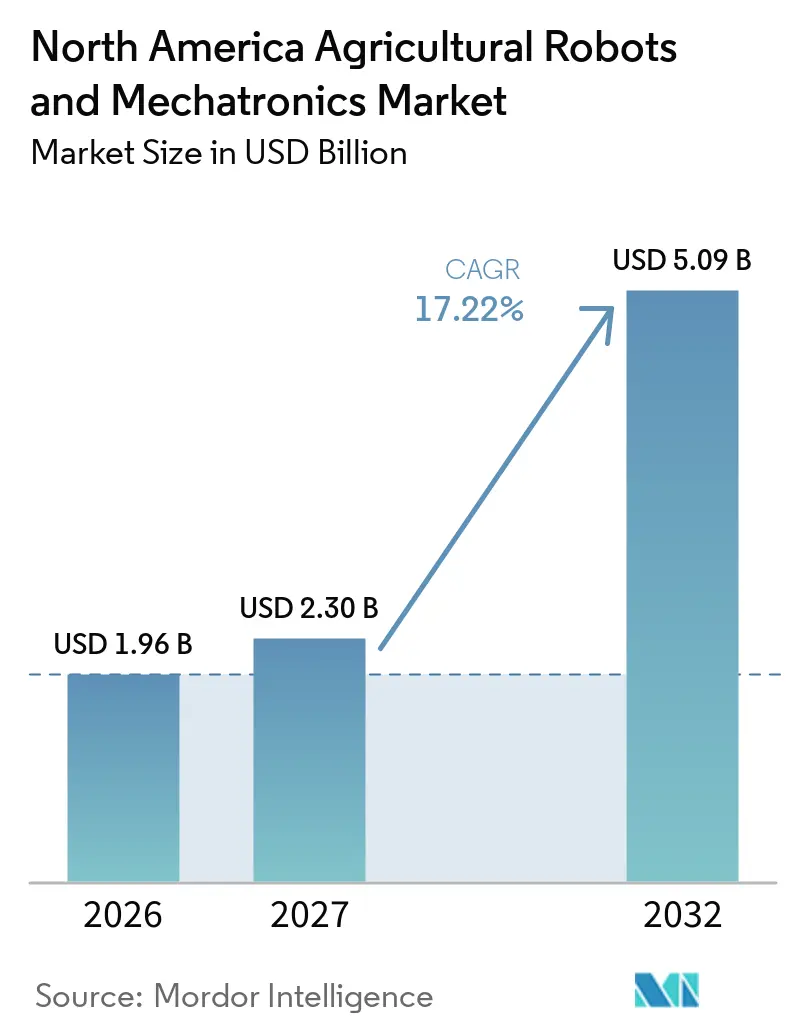
The North America agricultural robots and mechatronics market size was valued at USD 1.96 billion in 2026 and is projected to grow from USD 2.30 billion in 2027 to USD 5.09 billion by 2032, at a CAGR of 17.22% during the forecast period 2027 to 2032. The market is growing due to increased demand for automation, productivity requirements, and labor shortages in farming. The market encompasses robots for planting, harvesting, spraying, and crop monitoring, as well as mechatronics solutions that integrate mechanical, electrical, and computer engineering to enhance efficiency. The adoption of robotics and mechatronics in North America, particularly in the United States and Canada, is accelerating due to the agricultural sector's focus on sustainable farming practices and precision agriculture techniques.
The shortage of manual labor in agriculture, driven by demographic changes, is a key driver of the agricultural robotics market. According to World Bank data, the United States agricultural employment fell from 1.74% in 2021 to 1.66% in 2022. Robots can replace or complement human labor for tasks such as harvesting, weeding, and planting, helping farms continue operations even with fewer workers. Companies like FFRobotics have developed harvesting robots for orchards, addressing labor shortages by automating fruit-picking tasks.
With growing concerns over environmental impact, robots that can perform tasks like precise pesticide spraying, reducing chemical runoff, or optimizing water usage are gaining popularity. These technologies contribute to more sustainable agricultural practices. For instance, in 2021, Monarch Tractors launched a fully electric smart autonomous tractor, tailored for vineyards, emphasizing sustainable and efficient farming.
North America Agricultural Robots and Mechatronics Market Trends and Insights
Crop Production Holds a Significant Segment by Application
The increasing need to boost crop production in North America is significantly driving the demand for agricultural robots and mechatronics, as technology is increasingly being leveraged to address both operational challenges and the growing demands for efficiency, sustainability, and scalability. These advanced systems are transforming the landscape of modern agriculture, making it more efficient, less reliant on manual labor, and better equipped to meet the needs of a growing population.
The production of cereals, oilseeds, fruits, and vegetables in North America drives the demand for agricultural robotic machinery. According to FAOSTAT, cereal production in North America increased from 473.94 million metric tons in 2021 to 521.87 million metric tons in 2023. The need to increase the production of staple crops like wheat, corn, and rice to meet growing food and biofuel demands has made robotic machinery essential for maximizing efficiency. Autonomous harvesters, such as those manufactured by John Deere, improve harvesting operations for cereal crops through GPS, AI, and machine learning systems that enable operation with minimal human intervention. This automation reduces labor costs and increases harvesting precision. Autonomous seeders and planters improve crop yield by ensuring optimal spacing and planting depth through accurate seed sowing.
The growing demand for fresh produce, including fruits like berries and apples and vegetables like tomatoes and leafy greens, has accelerated the adoption of robotic technologies in North America's agricultural sector. These crops require higher precision in harvesting and post-harvest handling compared to grains or oilseeds.

United States Dominates the Market
The United States is the dominant force in the North America agricultural robotics and mechatronics market. The United States agricultural sector is one of the first to adopt and scale robotic technologies for a range of applications, including autonomous tractors, robotic harvesters, and precision planting systems. This early adoption by large-scale farms in regions such as the Midwest, California, and the Pacific Northwest gives US companies a competitive edge in developing reliable, high-performance systems that are trusted by farmers.
The United States is experiencing increased demand for autonomous tractors, driven by broader investments in agricultural robotics. Major manufacturers like John Deere, CNH Industrial (Case IH and New Holland), and Kubota have advanced their autonomous tractor development and commercialization efforts. The market has become increasingly competitive with the entry of innovative startups. The adoption of autonomous technology by farmers has contributed to the expansion of the North America agricultural robotics market. Sales of high-horsepower tractors in the United States reflect this growth, with units above 100 HP increasing from 26,387 in 2022 to 27,750 in 2023, according to the Association of Equipment Manufacturers.
Government incentives and policies aimed at promoting sustainable farming practices also support the adoption of agricultural robots and mechatronics. For instance, in 2022, the United States Department of Agriculture (USDA) allocated a significant USD 300 million to an organic transition initiative. This initiative not only aimed at cultivating new markets for farmers but also provided financial assistance for machinery acquisitions, including autonomous tractors, bolstered crop insurance, and extensive technical support, featuring farmer mentorship.

Competitive Landscape
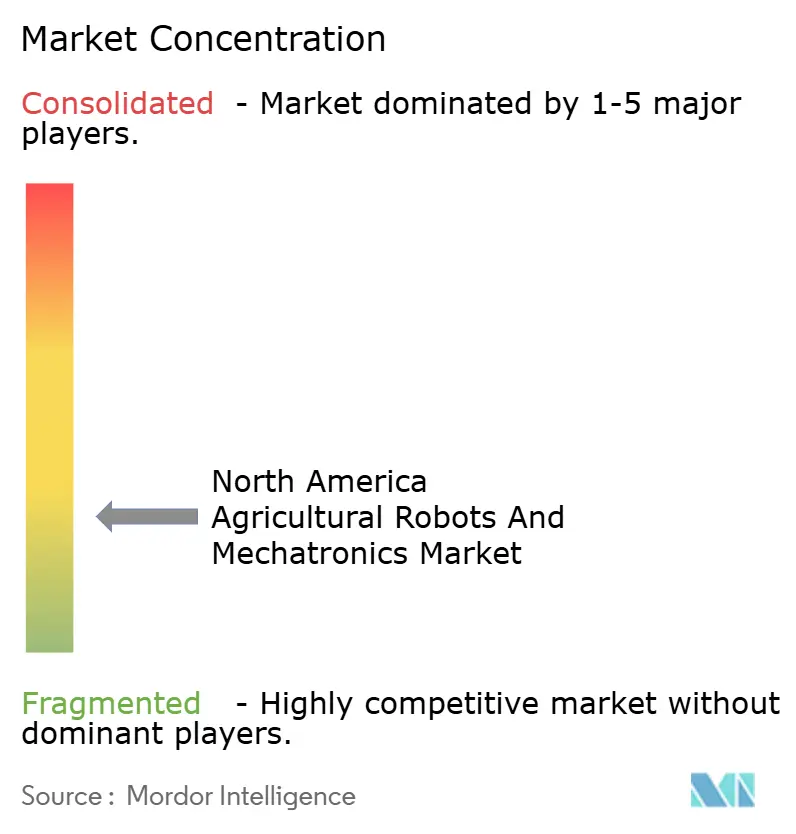
North America's agricultural robots and mechatronics market is fragmented, with several players operating across the market. The major players include AG Leader Technology, Agribotix LLC., Harvest Automation, DroneDeploy, and Blue River Technology. Several companies are expanding their presence in the market through product development, technological advancements, and strategic initiatives.
North America Agricultural Robots and Mechatronics Industry Leaders
-
DroneDeploy
-
Blue River Technology
-
AG Leader Technology
-
Agrobotix LLC
-
Harvest Automation Inc.
- *Disclaimer: Major Players sorted in no particular order
Recent Industry Developments
- July 2024: AGCO launched Autonomous Tractor Retrofit Kits for mixed fleets. AGCO is focused on a retrofit-first, mixed-fleet approach to tractor autonomy. Their OutRun autonomous system will allow the “continuation of the American farm”.
- December 2023: DeLaval, a global leader in dairy farming solutions, has launched the next generation of its automated teat sprayer, the DeLaval teat spray robot TSR2. The re-designed solution optimises the task of pre- and post-teat spray application for rotary milking systems offering improved cow health, faster operation, and a safer, more robust design—all of which help contribute to a reduction in labour and better cash flow.
North America Agricultural Robots and Mechatronics Market Report Scope
An agricultural robot is defined as any robotic device that can improve agricultural processes, by taking over many of the farmer's duties that are slow or labor intensive. North America Agricultural Robots and Mechatronics Market is Segmented by Type (Autonomous Tractors, UAVs, Milking Robots, and Other types), By Application (Crop Production, Animal Husbandry, Forest Control, and Other Applications), and By Geography (the United States, Canada, Mexico, and Rest of North America).
Type
| Autonomous Tractors |
| Unmanned Aerial Vehicles (UAVs) |
| Milking Robots |
| Other Types |
Application
| Crop Production |
| Animal Husbandry |
| Forest Control |
| Other Applications |
Geography
| United States |
| Canada |
| Mexico |
| Rest Of North America |
| Type | Autonomous Tractors |
| Unmanned Aerial Vehicles (UAVs) | |
| Milking Robots | |
| Other Types | |
| Application | Crop Production |
| Animal Husbandry | |
| Forest Control | |
| Other Applications | |
| Geography | United States |
| Canada | |
| Mexico | |
| Rest Of North America |
Key Questions Answered in the Report
What is the size of the North America agricultural robots and mechatronics market?
The North America agricultural robots and mechatronics market was valued at USD 1.96 billion in 2026 and is forecast to grow at a CAGR of 17.22% from 2027 to 2032.
What are agricultural robots and mechatronics?
Agricultural robots are robotic devices that perform or assist with agricultural activities that are slow or labor-intensive. The market also covers mechatronics solutions that integrate mechanical, electrical, and computer engineering to improve agricultural efficiency.
Who are the key players in North America agricultural robots and mechatronics market?
AG Leader Technology, Agribotix LLC, Harvest Automation Inc., DroneDeploy and Blue River Technology are the major companies operating in the North America agricultural robots and mechatronics market.
Which country dominates the North America agricultural robots and mechatronics market?
The United States dominates the market, supported by early adoption and scaling of autonomous tractors, robotic harvesters, and precision planting systems.