
Market Overview
| Study Period | 2019 - 2031 |
|---|---|
| Forecast Data Period | 2026 - 2031 |
| Base Year Market Size (2025) | USD 1.24 Billion |
| Market Size (2026) | USD 1.26 Billion |
| Market Size (2031) | USD 1.37 Billion |
| Growth Rate (2026 - 2031) | 1.69 % |
| Market Concentration | Medium |
Major Players *Disclaimer: Major Players sorted in no particular order Image © Mordor Intelligence. Reuse requires attribution under CC BY 4.0. | |
Middle East and Africa Military Helicopters Market Analysis by Mordor Intelligence
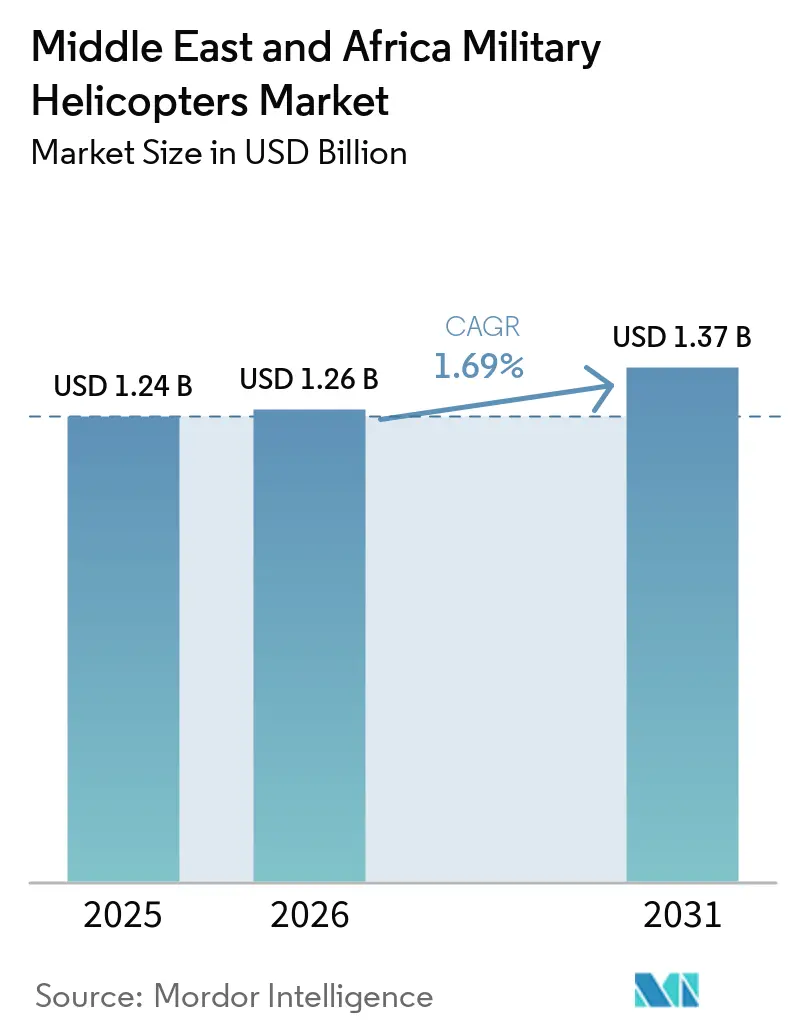
The Middle East and Africa military helicopters market size was valued at USD 1.24 billion in 2025 and is forecast to grow from USD 1.26 billion in 2026 to USD 1.37 billion by 2031, registering a 1.69% CAGR between 2026 and 2031. Fleet renewal, maritime security tasks, and continuing counter-terrorism requirements support demand. Gulf governments are pairing aircraft purchases with commitments to local maintenance, assembly, and training. This approach changes the competition because suppliers must offer both industrial participation and aircraft capability. African procurement remains shaped by security needs, but funding limits and maintenance capacity affect the pace of orders. Unmanned aircraft are taking some surveillance and light-strike tasks, while crewed helicopters remain important for transport, rescue, and complex operations.
Key Report Takeaways
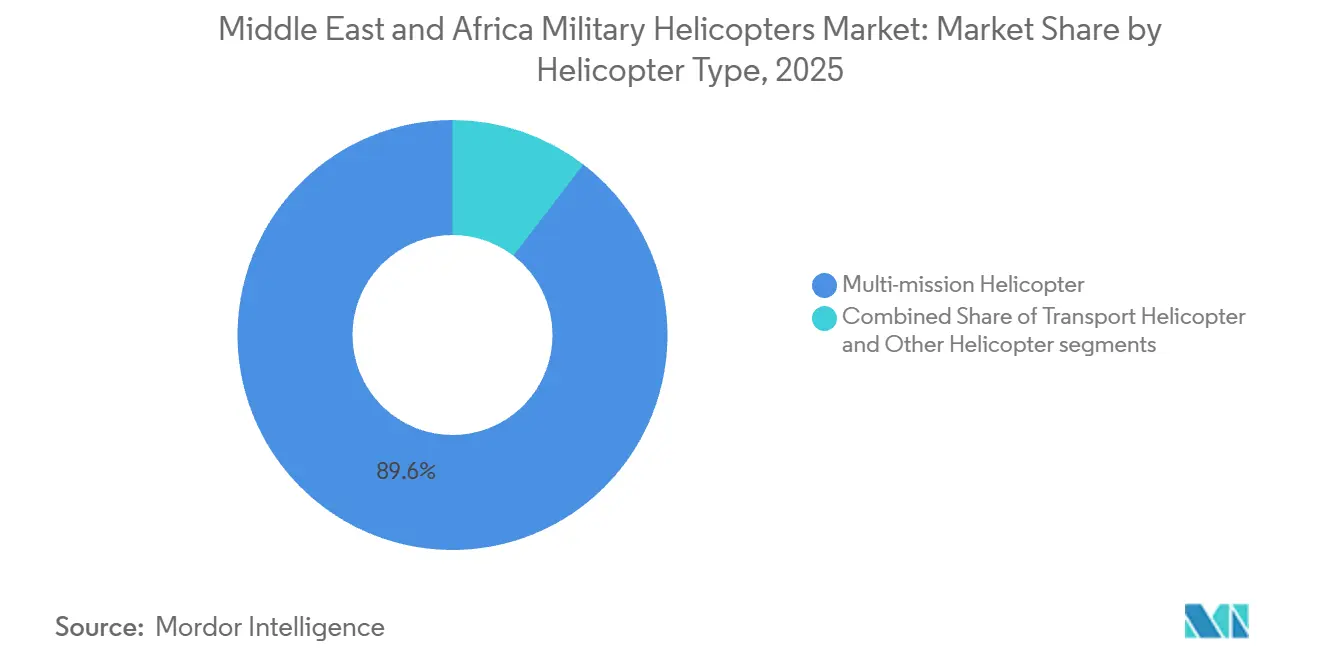
- By helicopter type, multi-mission helicopters accounted for 89.58% of the Middle East and Africa military helicopters market share in 2025, while the other helicopter segment is forecast to grow at a 3.62% CAGR through 2031.
- By end-user service, Army Aviation accounted for 43.87% of the Middle East and Africa military helicopters market share in 2025, while Naval/Marine Corps Aviation is forecast to grow at a 3.12% CAGR through 2031.
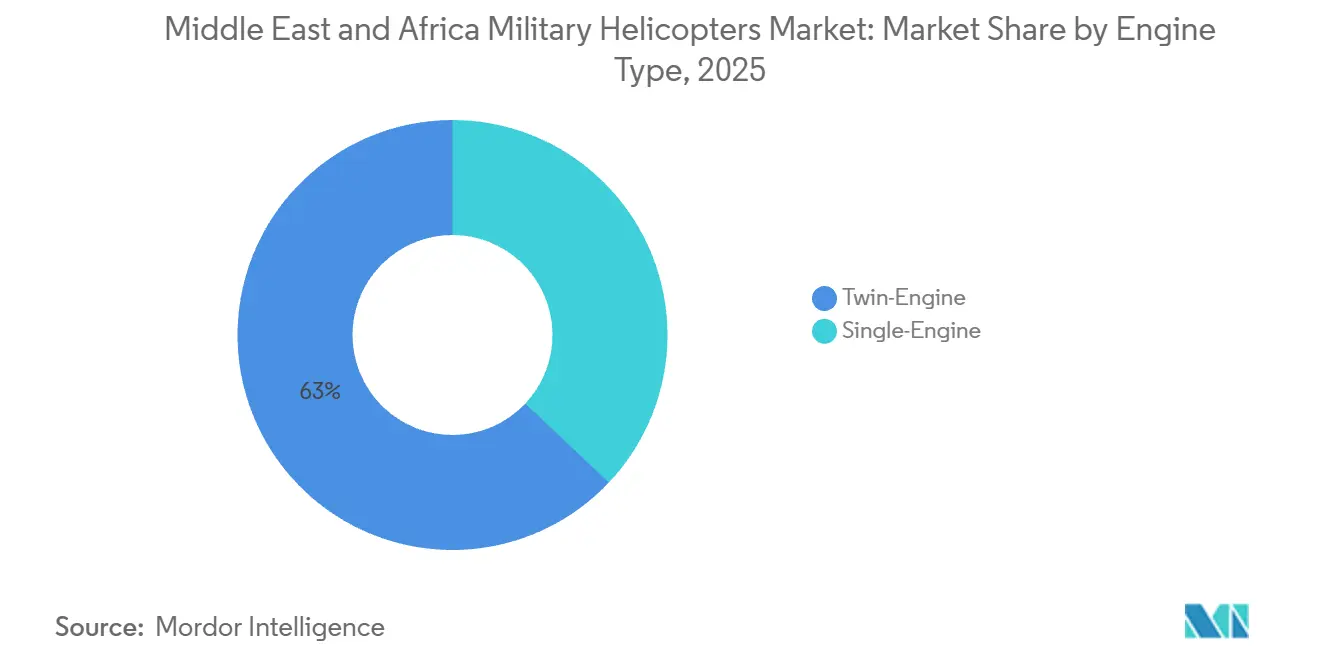
- By engine type, twin-engine configurations accounted for 62.97% of the Middle East and Africa military helicopters market share in 2025, while single-engine platforms are forecast to grow at a 2.75% CAGR through 2031.
- By application, combat and close air support accounted for 41.41% of the Middle East and Africa military helicopters market share in 2025, while humanitarian and disaster relief are forecast to grow at a 2.97% CAGR through 2031.
- By country, Saudi Arabia held 39.95% of the Middle East and Africa military helicopters market share in 2025, while Qatar is forecast to grow at a 3.03% CAGR through 2031.
Note: Market size and forecast figures in this report are generated using Mordor Intelligence’s proprietary estimation framework, updated with the latest available data and insights as of January 2026.
Middle East and Africa Military Helicopters Market Trends and Insights
Drivers Impact Analysis*
| Driver | (%) Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
|---|---|---|---|
| Replacement of aging rotorcraft fleets | +0.50% | Gulf States, North Africa, Sub-Saharan Africa | Medium term (2-4 years) |
| Gulf-led multi-mission modernization | +0.40% | Saudi Arabia, UAE, Qatar | Short term (≤ 2 years) |
| Counter-terrorism and border-security operations | +0.30% | Nigeria, Somalia, Sahel, North Africa | Short term (≤ 2 years) |
| Indigenous manufacturing, MRO, and technology-transfer mandates | +0.20% | Saudi Arabia, UAE | Long term (≥ 4 years) |
| Maritime security demand in the Red Sea, the Gulf of Aden, and Coastal Africa | +0.20% | Saudi Arabia, UAE, Egypt, East Africa | Medium term (2-4 years) |
| Manned-unmanned teaming and networked precision effects | +0.10% | Saudi Arabia, UAE, Israel | Long term (≥ 4 years) |
| Source: Mordor Intelligence | |||
Replacement of Aging Rotorcraft Fleets
Aging fleets are moving replacement decisions up the defense procurement agenda across the region. Older aircraft require more maintenance, and parts availability can weaken operational readiness. Governments also face pressure to improve aircraft survivability, communications, and mission equipment. Egypt’s approved CH-47F program illustrates the continuing role of heavy-lift fleet replacement in North Africa. The Middle East and Africa military helicopters market, therefore, benefits from operators replacing aircraft that no longer meet transport or operational requirements. Replacement programs can also create longer service opportunities for maintenance, pilot training, and logistics support.
Fleet replacement is not limited to large Gulf air arms. African operators must balance modern capability requirements against available technical staff and operating budgets. A modern platform can improve availability when a dependable spares and training plan supports it. The procurement case is stronger when one airframe can support transport, medical evacuation, and security missions. Suppliers that structure long-term support commitments can reduce the operational risk of moving away from legacy fleets. This makes lifecycle planning as important as aircraft acquisition in the Middle East and Africa military helicopters market.
Gulf-Led Multi-Mission Modernization
Gulf operators continue to favor helicopters capable of performing multiple tasks with a single fleet. This preference supports purchases of aircraft with adaptable cabins, sensors, communications equipment, and mission kits. It also reflects the need to use limited aircraft inventories across dispersed operational areas. Saudi Arabia’s defense spending reached USD 83.2 billion in 2025, providing a substantial defense funding base.[1] The Middle East and Africa military helicopters market gains from this spending when modernization budgets include air mobility and maritime operations. Procurement choices increasingly consider maintenance access and local industrial participation alongside performance.
Multi-mission fleets allow operators to use common training and support arrangements across several mission sets. This can reduce the burden of managing separate aircraft types for transport, rescue, and surveillance. The approach is particularly relevant where operational priorities can change quickly. It also favors aircraft suppliers that can integrate equipment without creating separate sustainment systems. Gulf procurement is shaping expectations elsewhere because regional buyers observe its emphasis on availability and mission flexibility. These conditions support continued demand for versatile aircraft in the market.
Counter-terrorism and Border Security Operations
Counter-terrorism and border security needs sustain demand for helicopters capable of operating from limited infrastructure. Rotary-wing aircraft provide mobility where roads are unreliable and ground movement is slow. They also support troop insertion, medical evacuation, surveillance, and resupply. Africa’s military expenditure rose 8.5% to USD 58.2 billion in 2025, while Nigeria’s expenditure increased 55% to USD 2.1 billion. These budget movements broaden the funding base for aviation programs, although not all spending becomes helicopter procurement. The Middle East and Africa military helicopters market is supported when security priorities require a rapid response across large territories.
Demand is often concentrated in smaller orders rather than in a single large fleet program. That pattern can favor platforms with lower operating demands and adaptable mission equipment. Operators also need training and maintenance support that matches local conditions. Border and internal security missions can continue even when larger modernization plans are delayed. This gives rotary-wing procurement a role in near-term defense readiness. It also creates a practical opening for suppliers capable of delivering aircraft and support packages quickly.
Indigenous Manufacturing, MRO, and Technology Transfer Mandates
Local industrial participation is becoming a central condition in major Gulf helicopter programs. Governments seek domestic capability in maintenance, repair, overhaul, training, and selected production work. This policy can extend the economic value of a purchase beyond initial aircraft delivery. It can also give operators greater control over availability during periods of high demand. The Middle East and Africa military helicopters industry is therefore becoming more dependent on partnerships that develop local technical capacity. Suppliers that provide credible training and sustainment plans are better positioned for long procurement cycles.
Local support arrangements can reduce dependence on overseas repair facilities and imported labor. They also make it easier to manage spare parts, component repair, and workforce development, bringing these activities closer to the operator. The benefits depend on the scope of technology transfer and the durability of the local supply base. In-country requirements may raise the complexity of bids, especially for smaller suppliers. However, they can establish lasting maintenance revenue after the aircraft enters service. This shift makes support capability a meaningful competitive factor in the Middle East and Africa military helicopters market.
Restraints Impact Analysis*
| Restraint | (%)Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
|---|---|---|---|
| High lifecycle cost and budget trade-offs | -0.30% | Sub-Saharan Africa, Iraq | Medium term (2-4 years) |
| Export controls and technology-transfer friction | -0.20% | Africa, Russian-legacy fleets, Global FMS | Short term (≤ 2 years) |
| Armed-UAV substitution in selected strike and ISR missions | -0.10% | UAE, Saudi Arabia, Israel | Long term (≥ 4 years) |
| Maintenance skills and readiness gaps in Tier-2 African markets | -0.10% | Sub-Saharan Africa, North Africa | Medium term (2-4 years) |
| Source: Mordor Intelligence | |||
High Lifecycle Cost and Budget Trade-Offs
Military helicopters require spending beyond the initial aircraft contract. Operators must fund spare parts, maintenance facilities, simulators, crew training, and mission equipment. These costs can be difficult for smaller defense budgets to sustain. Africa’s rise in military expenditure does not remove competing requirements for air defense, ground forces, and unmanned systems. The Middle East and Africa military helicopters market can therefore face delays when aircraft programs compete with other urgent priorities. Long-term support packages can reduce uncertainty but may increase the visible contract value.
Twin-engine aircraft with advanced sensors can be especially expensive to operate over their service lives. Operators must weigh their higher capability against recurring maintenance and training costs. Mixed fleets can add complexity because each type needs separate parts, tools, and technical skills. Lower-cost aircraft may meet limited transport or training needs, but they cannot replace every mission type. Budget decisions can therefore favor fewer highly capable aircraft or gradual fleet modernization. This restraint is strongest where operating funds do not rise with acquisition ambitions.
Export Controls and Technology Transfer Friction
Export controls can affect delivery schedules, configuration choices, and the availability of subsystems. These rules matter when platforms depend on components from several countries. They can also limit the scope of technology transfer that a customer seeks. Such limits are important in a region where local production and maintenance are increasingly important in procurement. The Middle East and Africa military helicopters market is affected when approvals add uncertainty to an already lengthy acquisition process. Operators may respond by considering platforms with less restrictive supply chains.
Technology-transfer requirements can create similar friction even when a platform is otherwise suitable. Suppliers must balance customer expectations with their own regulatory obligations and intellectual property controls. This can change competitive outcomes in tenders focused on local assembly or repair capability. It may also encourage countries to diversify their supplier base rather than rely on one source. The effect is most visible in programs with ambitious domestic capability goals. Procurement competition is consequently shaped by exportability, access to support, and local participation.
*Our forecasts treat driver/restraint impacts as directional, not additive. The impact forecasts reflect baseline growth, mix effects, and variable interactions.
Segment Analysis
By Helicopter Type: Multi-Mission Platforms Lead, While Other Types Grow Faster
Multi-mission helicopters accounted for 89.58% of the Middle East and Africa military helicopters market size in 2025. Their position reflects the value operators place on flexible use across transport, escort, medical evacuation, and maritime roles. A common platform can simplify training, maintenance, and parts planning. This is useful for forces managing diverse requirements with limited fleet numbers. The segment also fits Gulf procurement preferences for adaptable aircraft and enduring support. Its scale gives suppliers with established multi-mission fleets a strong base in the region.
Other helicopter types are forecast to grow at a 3.62% CAGR through 2031. This category includes aircraft acquired for more focused attack and reconnaissance requirements. Demand is linked to counter-terrorism operations and the need for a dedicated combat capability. Specialized aircraft can complement multi-mission fleets rather than replace them. Transport helicopters also remain relevant for heavy lift and force mobility. The Middle East and Africa military helicopters market will continue to require a balance between versatile fleets and mission-specific capability.

By End-User Service: Army Aviation Holds the Largest Position, While Naval Aviation Expands
Army Aviation accounted for 43.87% of the Middle East and Africa military helicopters market in 2025. Large land forces use helicopters for mobility, support, resupply, and emergency response. This role remains important in countries with expansive deserts, remote borders, and dispersed security operations. Army fleets also support the rapid movement of personnel and equipment. Their operational breadth helps explain the segment’s leading position. Demand remains linked to ground-force readiness and fleet availability.
Naval/Marine Corps Aviation is forecast to expand at a 3.12% CAGR through 2031. The segment benefits from increased attention to security in the Red Sea and the Gulf of Aden. Shipborne aircraft are needed for surveillance, rescue, transport, and maritime coordination. Egypt’s leadership of Combined Task Force 153 shows the continuing importance of regional maritime cooperation. Naval aircraft programs also involve ship integration and specialized crew training. These factors support a sustained service requirement in the regional market.
By Engine Type: Twin-Engine Platforms Lead, While Single-Engine Aircraft Gain Ground
Twin-engine configurations commanded 62.97% of the Middle East and Africa military helicopters market share in 2025. Their leading role reflects requirements for redundancy, payload, and longer-range operations. These features are relevant in maritime settings, rugged terrain, and demanding security missions. The UAE received approval for 6 CH-47F Block II helicopters valued at USD 1.32 billion in May 2025. [2] The package included extended-range fuel systems and mission equipment. Such programs demonstrate continued investment in capable twin-engine fleets.
Single-engine platforms are projected to grow at a 2.75% CAGR through 2031. They can be suitable for training, border surveillance, and lighter utility missions. Their lower operating burden can be relevant for users with constrained budgets. They also help operators retain flight training capacity without committing every flying hour to heavier aircraft. The category does not replace twin-engine platforms in all operational environments. Instead, it addresses missions where cost and simpler support requirements are more important.
By Application: Combat and Close Air Support Remain Central, While Disaster Relief Grows
Combat and close air support accounted for 41.41% of the Middle East and Africa military helicopters market size in 2025. The segment is tied to the need for rapid support in counter-terrorism and internal security operations. Helicopters can deliver reconnaissance, mobility, and direct support in locations that are difficult for ground forces to reach. These missions require reliable availability and trained crews. They also support demand for aircraft with protected systems and adaptable equipment. Combat capability, therefore, remains a core requirement across several national fleets.
Humanitarian and disaster relief is forecast to grow at a 2.97% CAGR through 2031. Military aircraft are frequently used to move supplies, evacuate people, and provide support after severe events. Multi-mission helicopters are well-suited to these tasks because their cabins and equipment can be quickly adapted. The role can justify investments in lift capacity even outside combat planning. It also strengthens the case for airframes available year-round. This application adds a broader public-response role to the regional market.
Geography Analysis
Saudi Arabia held 39.95% of the Middle East and Africa military helicopters market share in 2025. It remains the region’s principal source of helicopter demand because it operates aircraft across multiple military services. The country is also moving toward procurement models that include more domestic maintenance and industrial participation. Its USD 83.20 billion defense expenditure in 2025 provides a strong funding base for long-term capability programs. This mix of spending capacity and industrial policy makes Saudi Arabia central to regional supplier strategies.
Qatar is forecast to grow at a 3.03% CAGR through 2031, while the UAE remains another major Gulf demand center, with the approved USD 1.32 billion CH-47F Block II package highlighting heavy-lift requirements. Gulf buyers are increasingly interested in aircraft availability, local support, and flexible mission systems. Their programs can support high-value platforms as well as long-term sustainment activity. Maritime needs add further demand for aircraft capable of operating from coastal bases and naval vessels.
Africa’s military expenditure increased 8.5% to USD 58.2 billion in 2025, which supports a wider security funding base. Nigeria’s 55% increase to USD 2.1 billion was particularly significant. Demand is driven by border security, internal conflict, transport needs, and maritime operations. However, procurement is constrained by maintenance capacity and competition from other defense priorities. Egypt’s participation in Red Sea security also strengthens North Africa’s relevance for naval aviation planning. The Middle East and Africa military helicopters market therefore combines high-value Gulf programs with smaller but important African requirements.
Competitive Landscape
The Middle East and Africa military helicopters market is moderately consolidated among major OEMs. Airbus, Boeing, Leonardo, and Sikorsky have strong positions in Gulf procurement through established aircraft fleets and support arrangements. Their advantages include trained operator communities, mission equipment, and sustainment experience. Boeing’s approved CH-47F Block II program for the UAE demonstrates the importance of government-backed acquisition routes for high-value platforms. These suppliers compete on aircraft capability, delivery confidence, and long-term support. They must also respond to customer expectations for domestic participation.
Airbus has advanced a crewed-uncrewed teaming offering through HTeaming, introduced in June 2025. Airbus also received Ghana’s first order for 2 H175M multi-mission helicopters in January 2026. In July 2026, The Helicopter Company ordered 8 additional Airbus H145 helicopters under its existing framework. These moves show how product range, local operating relevance, and support relationships can reinforce a supplier’s regional position. Boeing remains important in heavy-lift, while other established manufacturers retain positions in the utility, naval, and combat helicopter categories.
Competition is widening as customers seek local assembly, maintenance, and technology participation. New suppliers can gain attention by offering flexible industrial terms or lower support costs. At the same time, complex mission systems and established training networks create barriers for new entrants. Leading global manufacturers hold a substantial share of Gulf contract value, but the supplied material does not achieve a combined top-5 share of 80% or more. Competition will remain strongest in countries where procurement combines fleet replacement with localization requirements. The Middle East and Africa military helicopters industry will reward suppliers that can provide a reliable aircraft, enduring support, and a credible local capability plan.
Middle East and Africa Military Helicopters Industry Leaders
-
Airbus SE
-
The Boeing Company
-
Leonardo S.p.A.
-
Russian Helicopters (Rostec)
-
Lockheed Martin Corporation
- *Disclaimer: Major Players sorted in no particular order
Recent Industry Developments
- January 2026: Ghana's MoD contracted Airbus Helicopters for 2 H175M multi-mission platforms for transport, SAR, and disaster relief operations, alongside 1 ACH175 and 1 ACH160, marking Airbus' return to the West African country and expanding its military helicopter footprint in Africa.
- May 2025: The US State Department approved USD 1.32 billion CH-47F Block II Chinook FMS to the UAE. The DSCA cleared 6 CH-47F Block II helicopters with extended-range fuel systems, air-to-air refueling probes, WESCAM MX-15HDi EO systems, and AN/AAR-57 CMWS for the UAE Joint Aviation Command, with Boeing and Honeywell as principal contractors.
Middle East and Africa Military Helicopters Market Report Scope
Military helicopters are rotary-wing aircraft designed for defense and security missions across land and maritime domains. Equipped with mission-specific avionics, weapon systems, survivability features, and advanced propulsion systems, they support tactical, strategic, and humanitarian operations, including combat support, troop transport, reconnaissance, search and rescue, logistics, and disaster relief in diverse and contested environments.
The Middle East and Africa military helicopters market is segmented by helicopter type, end-user service, engine type, application, and geography. By helicopter type, the market is segmented into multi-mission, transport, and other helicopters. By end-user service, the market is segmented into air force, army aviation, naval/marine corps aviation, joint/special operations, and paramilitary and coast guard. By engine type, the market is segmented into single-engine and twin-engine helicopters. By application, the market is segmented into combat and close air support, troop transport, humanitarian and disaster relief, and pilot training. The report also covers the market sizes and forecasts for the Middle East and Africa military helicopters market in five countries across the region. For each segment, the market size is provided in terms of value (USD).
By Helicopter Type
| Multi-mission Helicopter |
| Transport Helicopter |
| Other Helicopter |
By End-User Service
| Air Force |
| Army Aviation |
| Naval/Marine Corps Aviation |
| Joint/Special Operations |
| Paramilitary and Coast Guard |
By Engine Type
| Single-Engine |
| Twin-Engine |
By Application
| Combat and Close Air Support |
| Troop Transport |
| Humanitarian and Disaster Relief |
| Pilot Training |
By Geography
| South Africa |
| Nigeria |
| Qatar |
| Saudi Arabia |
| United Arab Emirates |
| Rest of Middle East and Africa |
| By Helicopter Type | Multi-mission Helicopter |
| Transport Helicopter | |
| Other Helicopter | |
| By End-User Service | Air Force |
| Army Aviation | |
| Naval/Marine Corps Aviation | |
| Joint/Special Operations | |
| Paramilitary and Coast Guard | |
| By Engine Type | Single-Engine |
| Twin-Engine | |
| By Application | Combat and Close Air Support |
| Troop Transport | |
| Humanitarian and Disaster Relief | |
| Pilot Training | |
| By Geography | South Africa |
| Nigeria | |
| Qatar | |
| Saudi Arabia | |
| United Arab Emirates | |
| Rest of Middle East and Africa |
Market Definition
- Aircraft Type - All the military rotorcraft which are used for various applications are included in this study.
- Sub-Aircraft Type - For this study, all the military helicopters based on their application are considered.
- Body Type - Multi-Mission Helicopters, Transport Helicopters, Training Helicopters and various other rotorcraft are considered in this study.
| Keyword | Definition |
|---|---|
| IATA | IATA stands for the International Air Transport Association, a trade organization composed of airlines around the world that has an influence over the commercial aspects of flight. |
| ICAO | ICAO stands for International Civil Aviation Organization, a specialized agency of the United Nations that supports aviation and navigation around the globe. |
| Air Operator Certificate (AOC) | A certificate granted by a National Aviation Authority permitting the conduct of commercial flying activities. |
| Certificate Of Airworthiness (CoA) | A Certificate Of Airworthiness (CoA) is issued for an aircraft by the civil aviation authority in the state in which the aircraft is registered. |
| Gross Domestic Product (GDP) | Gross domestic product (GDP) is a monetary measure of the market value of all the final goods and services produced in a specific time period by countries. |
| RPK (Revenue Passenger Kilometres) | The RPK of an airline is the sum of the products obtained by multiplying the number of revenue passengers carried on each flight stage by the stage distance - it is the total number of kilometers traveled by all revenue passengers. |
| Load Factor | The load factor is a metric used in the airline industry that measures the percentage of available seating capacity that has been filled with passengers. |
| Original Equipment Manufacturer (OEM) | An original equipment manufacturer (OEM) traditionally is defined as a company whose goods are used as components in the products of another company, which then sells the finished item to users. |
| International Transportation Safety Association (ITSA) | International Transportation Safety Association (ITSA) is an international network of heads of independent safety investigation authorities (SIA). |
| Available Seats Kilometre (ASK) | This metric is calculated by multiplying Available Seats (AS) in one flight, defined above, multiplied by the distance flown. |
| Gross Weight | The fully-loaded weight of an aircraft, also known as “takeoff weight,” which includes the combined weight of passengers, cargo, and fuel. |
| Airworthiness | The ability of an aircraft, or other airborne equipment or system, to operate in flight and on the ground without significant hazard to aircrew, ground crew, passengers or to other third parties. |
| Airworthiness Standards | Detailed and comprehensive design and safety criteria applicable to the category of aeronautical product (aircraft, engine or propeller). |
| Fixed Base Operator (FBO) | A business or organization that operates at an airport. An FBO provides aircraft operating services like maintenance, fueling, flight training, charter services, hangaring, and parking. |
| High Net worth Individuals (HNWIs) | High Net worth Individuals (HNWIs) are individuals with over USD 1 million in liquid financial assets. |
| Ultra High Net worth Individuals (UHNWIs) | Ultra High Net worth Individuals (UHNWIs) are individuals with over USD 30 million in liquid financial assets. |
| Federal Aviation Administration (FAA) | The division of the Department of Transportation is concerned with aviation. It operates Air Traffic Control and regulates everything from aircraft manufacturing to pilot training to airport operations in the United States. |
| EASA (European Aviation Safety Agency) | The European Aviation Safety Agency is a European Union agency established in 2002 with the task of overseeing civil aviation safety and regulation. |
| Airborne Warning and Control System (AW&C) aircraft | Airborne Warning and Control System (AEW&C) aircraft is equipped with a powerful radar and on-board command and control center to direct the armed forces. |
| The North Atlantic Treaty Organization (NATO) | The North Atlantic Treaty Organization (NATO), also called the North Atlantic Alliance, is an intergovernmental military alliance between 30 member states – 28 European and two North American. |
| Joint Strike Fighter (JSF) | Joint Strike Fighter (JSF) is a development and acquisition program intended to replace a wide range of existing fighter, strike, and ground attack aircraft for the United States, the United Kingdom, Italy, Canada, Australia, the Netherlands, Denmark, Norway, and formerly Turkey. |
| Light Combat Aircraft (LCA) | A light combat aircraft (LCA) is a light, multirole jet/turboprop military aircraft, commonly derived from advanced trainer designs, designed for engaging in light combat. |
| Stockholm International Peace Research Institute (SIPRI) | Stockholm International Peace Research Institute (SIPRI) is an international institute that provides data, analysis, and recommendations for armed conflict, military expenditure, and arms trade as well as disarmament and arms control. |
| Maritime Patrol Aircraft (MPA) | A maritime patrol aircraft (MPA), also known as maritime reconnaissance aircraft is a fixed-wing aircraft designed to operate for long durations over water in maritime patrol roles, in particular, anti-submarine warfare (ASW), anti-ship warfare (AShW), and search and rescue (SAR). |
| Mach Number | The Mach number is defined as the ratio of true airspeed to the speed of sound at the altitude of a given aircraft. |
| Stealth Aircraft | Stealth is a Common term applied to low observable (LO) technology and doctrine, that makes an aircraft near invisible to radar, infrared or visual detection. |
Research Methodology
Mordor Intelligence follows a four-step methodology in all our reports.
- Step-1: Identify Key Variables: In order to build a robust forecasting methodology, the variables and factors identified in Step-1 are tested against available historical market numbers. Through an iterative process, the variables required for market forecast are set and the model is built on the basis of these variables.
- Step-2: Build a Market Model: Market-size estimations for the historical and forecast years have been provided in revenue and volume terms. For sales conversion to volume, the average selling price (ASP) is kept constant throughout the forecast period for each country, and inflation is not a part of the pricing.
- Step-3: Validate and Finalize: In this important step, all market numbers, variables and analyst calls are validated through an extensive network of primary research experts from the market studied. The respondents are selected across levels and functions to generate a holistic picture of the market studied.
- Step-4: Research Outputs: Syndicated Reports, Custom Consulting Assignments, Databases & Subscription Platforms


