Indonesia Health and Medical Insurance Market Analysis by Mordor Intelligence
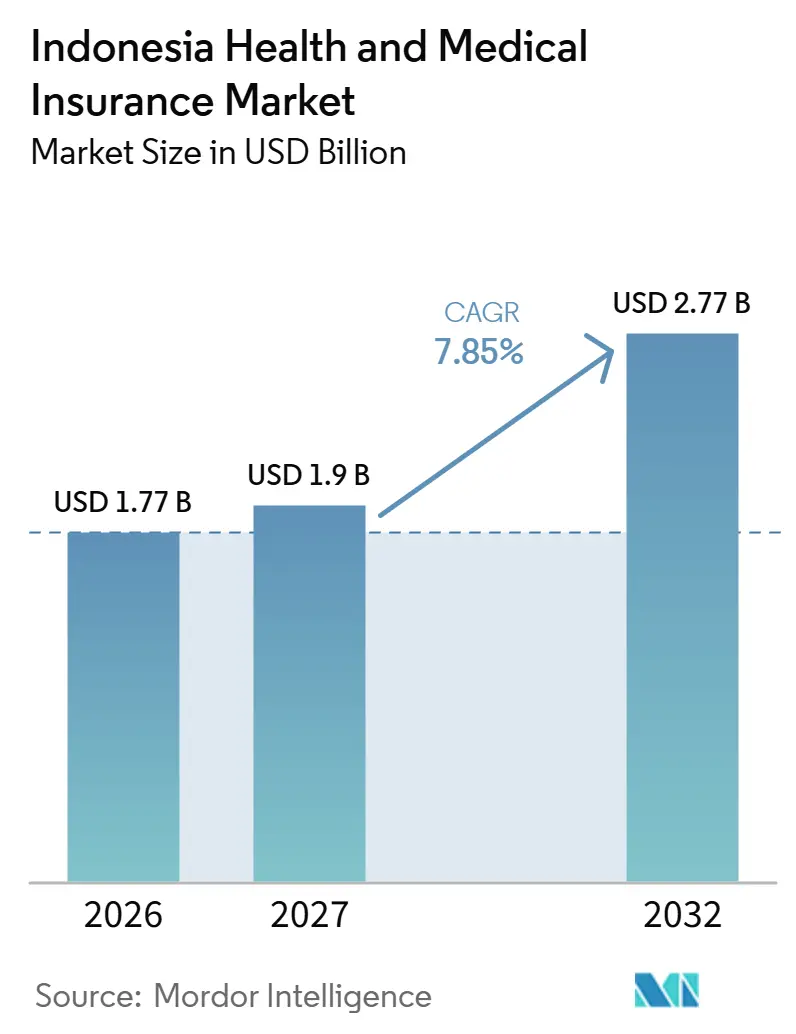
The Indonesia health and medical insurance market size is expected to increase from USD 1.77 billion in 2026 to USD 1.9 billion in 2027 and reach USD 2.77 billion by 2032, growing at a CAGR of 7.85% over 2027-2032.
Broad registration in Indonesia’s national health insurance scheme, Jaminan Kesehatan Nasional (JKN), makes sustained participation central to future insurance demand. Private top-up plans can complement this base when insurer and provider arrangements make additional benefits usable. Rising claims costs create premium-repricing pressure while constraining how broadly insurers can extend medical protection. Insurers can respond through benefit design and better coordination with hospitals, linking coverage choice with the settlement of care. With JKN registering most residents, private insurers compete for cover above that entitlement, favoring plans whose pricing absorbs rising claims costs while preserving usable access to contracted hospitals.
Key Report Takeaways
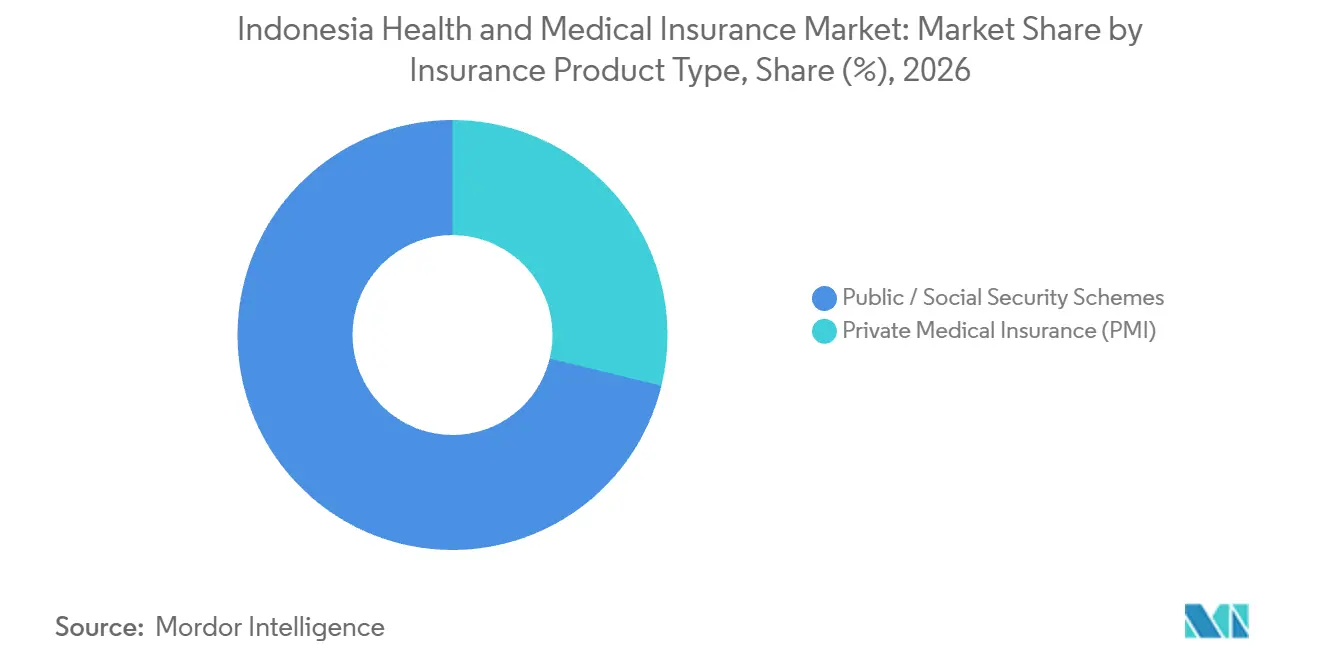
- By insurance product type, public and social security schemes led with a 71.21% Indonesia health and medical insurance market share in 2026, while private medical insurance (PMI) is forecast to grow fastest at a CAGR of 9.4% during 2027-2032.
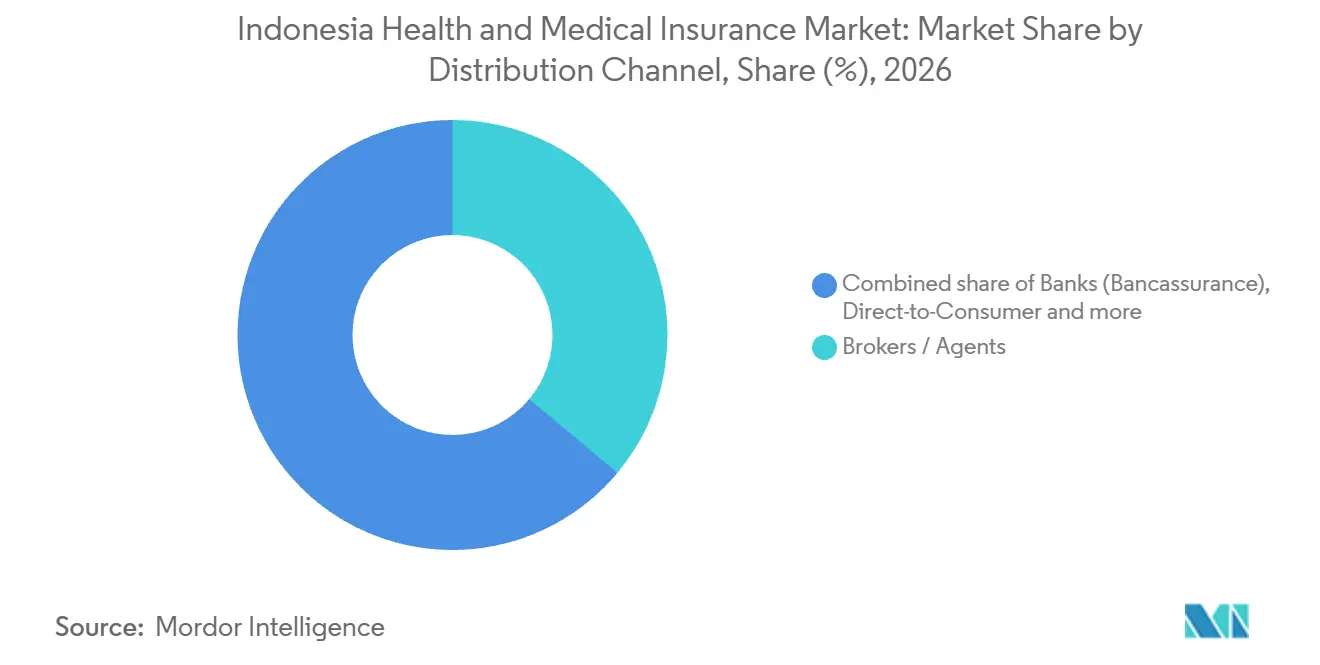
- Distribution through brokers and agents accounted for a 36.08% share of the Indonesia health and medical insurance market size in 2026, and direct-to-consumer coverage is forecast to grow fastest at a CAGR of 8.9% during 2027-2032.
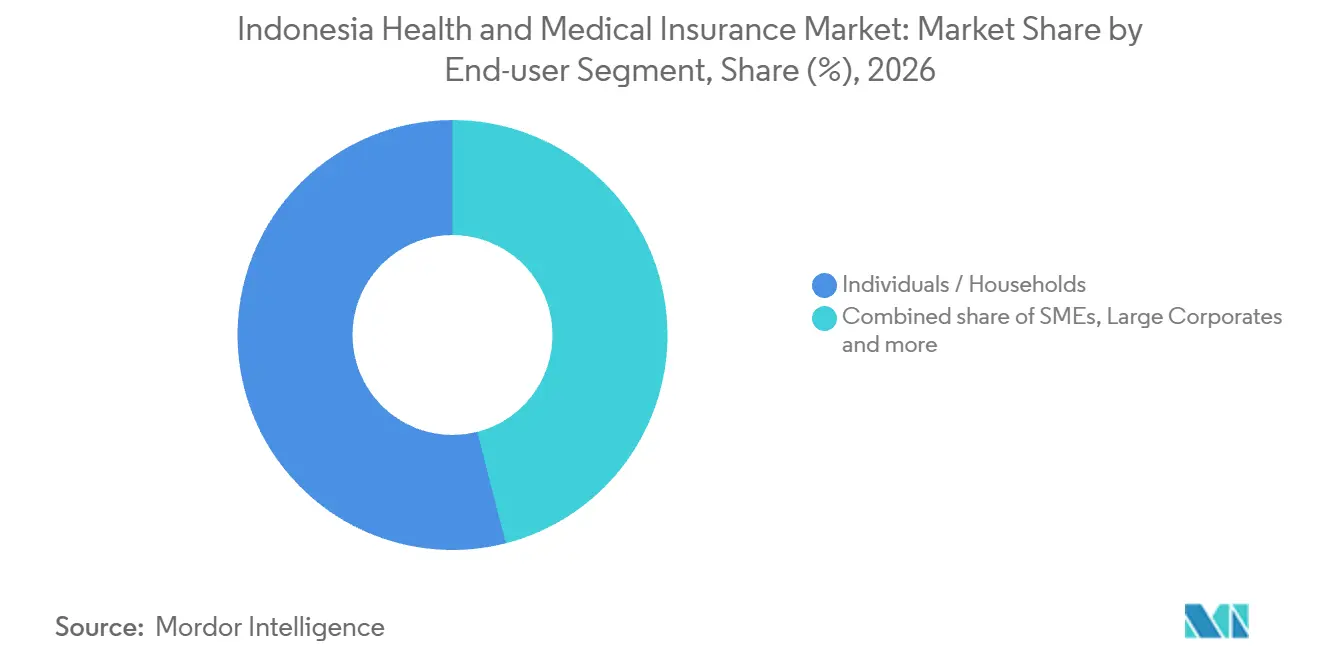
- Among end users, individuals and households led with a 53.99% share of the market in 2026, while small and medium-sized enterprises (SMEs) are forecast to grow fastest at a CAGR of 9.7% during 2027-2032.
Note: Market numbers in this report are based on Mordor Intelligence's proprietary estimation framework, which combines nine months of actuals with Q4 projections for base year 2026.
Indonesia Health and Medical Insurance Market Trends and Insights
Drivers Impact Analysis*
| Driver | (~) % Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
|---|---|---|---|
| Near-universal JKN coverage expansion | +3% | Nationwide | Medium term (2-4 years) |
| Rising middle-class demand for private top-up plans | +2.6% | Nationwide | Short term (≤ 2 years) |
| Double-digit medical-cost inflation boosting employer group cover | +2.2% | Nationwide | Short term (≤ 2 years) |
| Stricter OJK conduct rules raising consumer confidence | +1.4% | Nationwide | Medium term (2-4 years) |
| Digital bank and e-wallet distribution unlocking micro-insurance | +0.9% | Nationwide | Medium term (2-4 years) |
| 2025 government-funded annual check-ups creating new risk pools | +0.6% | Nationwide | Long term (≥ 4 years) |
| Source: Mordor Intelligence | |||
Near-universal JKN coverage expansion
Recurring JKN contributions link participants’ financing decisions with the public scheme’s ability to sustain insured care. A BPJS Kesehatan Medan branch official reported approximately 284.5 million JKN participants nationally as of August 31, 2026, representing more than 98% of Indonesia’s population. At NADI JKN’s August 4, 2026 launch, BPJS Kesehatan reported 3,000 online motorcycle driver partners had joined its contribution-savings program, with daily, weekly, or monthly schedules. BPJS Kesehatan administers the program with GoTo as its partner, and deductions depend on participants agreeing to the applicable terms. Selectable saving intervals can make a recurring contribution easier to organize, connecting a broad registration base with a practical financing mechanism. At near-universal registration, contribution continuity becomes a route to deeper public insurance financing that does not depend on large increases in first-time enrollment.
Rising middle-class demand for private top-up plans
Private top-up coverage becomes more usable when its additional benefits can work alongside a household’s existing JKN protection. In 2026, BPJS Kesehatan signed coordination agreements with 18 supplemental health insurers, bringing its reported partner count to 31. Eligibility requires active JKN and supplemental policies, with care delivered at a facility contracted with both parties. That structure makes the overlap between payer networks commercially important because a wider private benefit promise needs an accessible route to coordinated treatment. The coordinated service depends on keeping both memberships active through a claim, making ongoing eligibility as important as initial policy acquisition. For households choosing a top-up, overlap with their intended treatment facility is more consequential than the number of insurers participating nationally.
Double-digit medical-cost inflation boosting employer group cover
Employers confronting higher medical claims need group coverage whose benefits can be sustained as the price of protection rises. Aon forecast gross annual medical-cost growth for Indonesian employer-sponsored medical plans at 17.3% in 2027, compared with 16.9% in 2026. IFG Progress’s Q2 2026 report identified employee-benefit consultants among several channels recording increased premium income in conventional life insurance. Its Q1 2025 analysis linked increased group-health premiums to repricing in response to rising health-insurance claims. That earlier mechanism shows how higher claims can increase employer spending on cover without requiring additional employees to become insured. Employee-benefit distributors can turn that repricing need into recurring renewal work, with benefit design determining what protection the employer retains.
Stricter OJK conduct rules raising consumer confidence
Consumer protection can support insurance demand by making the relationship with an insurer less dependent on promises made during a sale. Regulation 22/2023 issued by Otoritas Jasa Keuangan (OJK) took effect on December 22, 2023, replacing the 2022 rule and requiring financial-services providers, including insurers, to apply consumer-protection principles. For health insurers, that obligation makes treatment of policyholders part of the competitive proposition alongside the benefits being offered. A common conduct framework can also reduce the uncertainty facing households when they compare commitments that will be tested after illness occurs. The rule covers banks as well as insurers, so the same consumer-protection principles frame a household’s health-policy purchase whether it reaches an insurer directly or through a partner bank.
Restraints Impact Analysis*
| Restraint | (~) % Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
|---|---|---|---|
| JKN funding deficits posing risks to provider reimbursements | -1.2% | Nationwide | Short term (≤ 2 years) |
| Accelerating medical inflation squeezing insurer margins | -1% | Nationwide | Short term (≤ 2 years) |
| Data-localization and PDP law compliance costs | -0.4% | Nationwide | Medium term (2-4 years) |
| Low health-insurance literacy in rural provinces | -0.3% | Negeri Liang, Central Maluku | Long term (≥ 4 years) |
| Source: Mordor Intelligence | |||
JKN funding deficits posing risks to provider reimbursements
A gap between JKN contributions and benefit payments makes provider reimbursement capacity dependent on financing beyond collected premiums. BPJS Kesehatan reported an approximate IDR 14 trillion (USD 770 million) cash-flow deficit through September 2026, comparing premiums collected with healthcare benefits paid. For participating health facilities, that imbalance creates payment risk when considering how much additional insured care to accommodate. The constraint can therefore weaken the commercial link between broad enrollment and providers’ willingness to expand insured services. In September 2026, the government planned additional IDR 20 trillion (USD 1.1 billion) for October and November to support BPJS Kesehatan’s hospital claim payments. Additional funding can support payments, but expanding care commitments requires financing that can keep pace with benefit costs.
Accelerating medical inflation squeezing insurer margins
Rising claims costs can make additional health premiums less attractive when insurers cannot preserve underwriting returns. Indonesia’s general-insurer health-insurance claims ratio rose from 58.2% at the end of 2024 to 67.3% at the end of 2025. Separately, Maximus Insurance said medical inflation contributed to its health line missing loss-ratio and underwriting-profitability targets at year-end 2025.[1] These pressures make benefit breadth and acceptance terms commercial constraints, since additional coverage also brings exposure to expensive treatment. By February 27, 2026, Maximus Insurance reported tightening underwriting, evaluating benefit design, and strengthening cost containment. Such responses can limit exposure, but the underlying claims burden leaves insurers balancing broader access against the cost of protecting each additional policyholder.
*Our forecasts treat driver/restraint impacts as directional, not additive. The impact forecasts reflect baseline growth, mix effects, and variable interactions.
Segment Analysis
By Insurance Product Type: Public Service Scale and Private Premium Growth
Public and social security schemes accounted for a 71.21% share of the Indonesia health and medical insurance market size in 2026. Indonesia’s National Social Security Council (DJSN) reported an 80.25% participant activity rate within JKN as of June 30, 2026.[2] BPJS Kesehatan also reported 725.3 million healthcare visits through JKN in 2025. For this largest segment, the activity rate separates registration from the eligibility that makes a healthcare encounter insurable. The service volume makes JKN commercially significant to providers through recurring treatment, while inactive registrations represent potential demand that requires restored eligibility.
Private medical insurance (PMI) is forecast to be the fastest-growing segment, at a CAGR of 9.4% during 2027-2032. Health-insurance premium income in Indonesia’s life-insurance industry rose 12.04% in the first half of 2026 from the same period of 2025. AAJI also reported 2.08 million group health-claim beneficiaries among life insurers in January-June 2026, up 6.4% from the same period of 2025. The growing group claims population gives that premium expansion an operating counterpart, making capacity to administer covered treatment relevant to private insurers’ growth as well as their ability to sell protection.

By Distribution Channel: Advisory Scale and the Direct Service Proposition
Brokers and agents represented a 36.08% Indonesia health and medical insurance market share in 2026. PT Talisman Insurance Brokers serves employee and individual programs and has more than 110 professionals across its business. For this largest segment, professional organization can support the advisory work involved in translating medical-protection needs into a contractual insurance arrangement. Medical policies connect expectations about care with payment conditions, giving advice a potential role in explaining both benefits and obligations. Talisman’s broad insurer relationships across employee and individual programs let one intermediary set several insurers’ medical terms side by side for the same client.
Direct-to-consumer is forecast to be the fastest-growing segment, at a CAGR of 8.9% during 2027-2032. In 2025, PT Lippo General Insurance reported that its health-insurance product on MyPro+, its own online portal, reached more customers. An insurer-owned portal can expand access without requiring a bank-customer relationship, giving buyers a route to medical cover outside branch-led distribution. Banks, through bancassurance, offer another route, with Great Eastern Life Indonesia providing health insurance among the solutions offered to OCBC Bank customers. MyPro+ also offers car, home, travel, and personal accident cover, so insured customers of other lines can find the insurer’s health product on the same portal.
By End-user Segment: Household Protection and Small-Group Access
Individuals and households held 53.99% of the market in 2026 and were the largest segment. Indonesia’s life-insurance association, AAJI, reported IDR 16.59 trillion (USD 1.01 billion) in individual health claims paid by life insurers in 2025. Those payments show the financial role of individual policies when covered treatment becomes an expense that needs to be settled. A servicing model designed for individual policyholders can connect eligibility questions and claim follow-up within a continuing relationship with the household.
SMEs are forecast to be the fastest-growing segment, at a CAGR of 9.7% during 2027-2032. In 2025, Roojai launched Asuransi Karyawan HealthCare+ for Indonesian SMEs with a minimum of 3 participants, supported by Sompo Insurance. Lifepal, an insurance broker, also introduced prepackaged SME employee-health products in 2025, using an online form followed by assistance from its employee-benefits team. The commercial opportunity lies in combining an accessible group structure with help choosing benefits, allowing the offer to address small-employer needs without requiring a large employee pool.
Geography Analysis
Jakarta illustrates the scale of public health-insurance participation that insurers and providers accommodate within a single provincial market. In June 2026, DKI Jakarta reported 10.87 million JKN participants, including 4.07 million in its largest participant category (labeled “PBPU dan BP PEMDA”). For private insurers, a substantial public participant base creates a potential audience for supplemental benefits that can work alongside the underlying public entitlement. The dashboard also reports 10.88 million residents, placing JKN registration close to population scale. That reach leaves supplemental insurers to differentiate what a second policy adds.
Within Java and Bali, Bali shows how JKN financing reaches a defined set of local hospitals through payments for treatment. In 2025, BPJS Kesehatan paid IDR 300 billion (USD 18.3 million) for services at 4 Bali hospitals, including Bali Mandara Hospital and Bali Mandara Eye Hospital. The payment illustrates realized demand for insured treatment in Bali, giving the identified provider group a service-revenue relationship with the public scheme. Unlike an enrollment total, that spending identifies care already financed, placing the commercial emphasis on sustaining the hospitals’ capacity to deliver JKN services.
Local understanding of benefits creates a different access question from the registration scale and provider financing seen in other parts of Indonesia. In Negeri Liang, Central Maluku, interviews with local authorities and health workers found limited understanding of JKN procedures and benefits. For administrators communicating with households in this community, the reported problem concerns explaining existing benefits and the procedures attached to them. Separately, as of May 31, 2026, North Maluku had 271 BPJS Kesehatan-contracted facilities serving JKN participants, comprising 210 primary-care facilities, 19 referral hospitals, and 42 supporting facilities. That mix makes coordination across care levels an operating consideration alongside the communication needs identified in Negeri Liang.
Regulatory Framework and Outlook
This comparison of selected jurisdictions assesses authorization and public-coverage coordination from the perspective of a private health insurer operating in Indonesia. Under POJK 36/2025, OJK requires private insurers to obtain approval for the health-insurance business line and to conduct utilization reviews, and the regulation expressly excludes JKN. Jakarta’s Health Office administers registration guidance and contribution payments to BPJS Kesehatan for a defined category of residents registered by the province. The distinction matters commercially because national permission to provide private coverage and local administration of public participation involve different authorities and responsibilities.
Regulatory Table
| Decision factor | Indonesia | Jakarta |
|---|---|---|
| Primary authority | OJK for private health insurers | OJK for private insurers; Jakarta Health Office for provincial JKN administration |
| Key instruments or direction | POJK 36/2025 authorization and utilization-review duties | National POJK 36/2025; Governor Regulation 26/2026 for provincial JKN registration and data updates |
| Commercial effect | Alignment of existing health products and approval of existing health-insurance lines | National insurer obligations plus public registration and contribution administration for a defined province-enrolled category |
| Current policy attractiveness | Medium | Medium |
| Future direction of policy attractiveness | Hardening | Hardening |
| Source: Mordor Intelligence | ||
Indonesia receives a Medium rating because authorization and review obligations link market access to continuing operating responsibilities. Hardening reflects the December 22, 2026 deadline to align previously approved or reported health products and obtain approval for existing health-insurance lines. Jakarta is also Medium because provincial contribution administration can underpin public and private coverage coordination, while the national authorization deadline applies to private insurers operating there. Under Governor Regulation 26/2026, the governor’s data-update guidance is due within 6 months of October 5, 2026, and the specified province-registered participants must complete their initial data updates within one year.
Value Chain Stages
The value chain compares policy underwriting and distribution, medical-service delivery, and claims administration, each with a different basis for supplier earnings. AXA Mandiri, a joint venture between Bank Mandiri and AXA Group, sells life and health insurance through more than 1,500 financial advisers across more than 1,500 Bank Mandiri branches. Hospital operators capture revenue from delivering care, with Siloam identifying private insurers among its sources of revenue. AdMedika, a third-party administrator (TPA), supplies claims and provider-network management, making administrative coordination a separate commercial capability from accepting insurance risk or treating patients.
Value Chain Analysis Table
| Primary activity | Key participants | Value capture | Bottleneck | Resilience response |
|---|---|---|---|---|
| Policy underwriting and distribution | Health insurers such as AXA Mandiri, with bank distribution partners such as Bank Mandiri | Insurer premium income | Translating benefit terms into an offer that can be consistently explained | Align product rules and adviser guidance before expanding distribution |
| Medical-service delivery | Hospital operators such as RS Pondok Indah and Siloam Hospitals | Medical-service revenue paid by insurers | Coordinating covered treatment with the relevant payer | Establish clear authorization and billing responsibilities with insurer partners |
| Claims administration | Third-party administrators such as AdMedika, part of Fullerton Health | Administration-service contract revenue | Reconciling member eligibility, provider information, and claim records | Link verification and authorization processes across participating organizations |
| Source: Mordor Intelligence | ||||
Value can shift toward coordination when a policy, a hospital encounter and its settlement must function as a connected service. On December 16, 2025, AdMedika described real-time member verification and cashless-service authorization intended to shorten administration waits at facilities. Malacca Trust Wuwungan Insurance reported that AdMedika provides health-insurance administration services under an agreement signed March 25, 2021, with no termination notice received by the completion of its March 2026 financial statements.
Competitive Landscape
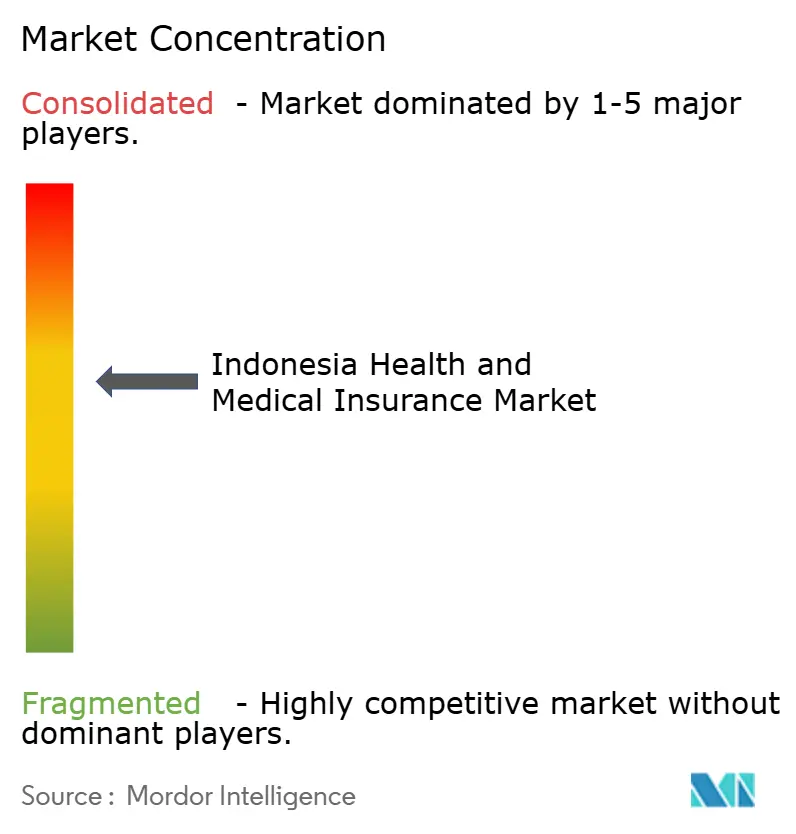
Competition combines a substantial public scheme with private insurers differentiated by benefit structure, distribution and access to healthcare providers. BPJS Kesehatan administers JKN, while Prudential Indonesia, Allianz Life Indonesia, AIA Financial Indonesia, and AXA Mandiri Financial Services provide private health protection. In 2025, Prudential’s PRUPriority Hospitals network included more than 1,700 hospitals across more than 500 Indonesian cities and regencies, including Ministry of Health-affiliated vertical hospitals.[3] That reach makes provider relationships commercially significant, since entrants seeking a similarly broad proposition must consider the service arrangements behind coverage as well as policy benefits.
Allianz Life Indonesia and Allianz Syariah paid combined health claims of IDR 3.7 trillion (USD 225.7 million) during 2025. In 2025, Allianz Life Indonesia and Allianz Syariah introduced Allianz Flexi Medical Plan and AlliSya Flexi Medical Plan as inpatient and surgical riders attached to unit-linked life products. On August 27, 2026, AIA Financial Indonesia introduced AIA Nura Care, an individual sharia health top-up designed to supplement existing benefits through working life and retirement. The distinction gives buyers a concrete choice between adding medical protection within a life policy and supplementing benefits already held, making the fit with existing coverage central to product selection.
Operational coordination creates another route to differentiation because the insurance promise depends on transactions involving providers and administrators. On December 4, 2025, AXA Mandiri, AdMedika and Mitra Keluarga agreed to align service tariffs and strengthen systems integration for participant verification, administration and claim finalization. The agreement links insurer, administrator and hospital responsibilities, making the targeted improvements a joint operating task rather than a change to policy benefits. On September 30, 2026, AIA stated that the transfer of its sharia portfolio to newly licensed PT AIA Syariah Insurance would take effect only after required regulatory approval. Until that approval is obtained, AIA Financial continues to serve its sharia customers through its existing sharia business unit.
Indonesia Health and Medical Insurance Industry Leaders
-
BPJS Kesehatan
-
Prudential Indonesia
-
Allianz Life Indonesia
-
AIA Financial Indonesia
-
AXA Mandiri Financial Services
- *Disclaimer: Major Players sorted in no particular order
Key Opportunities for Market Participants
The opportunities compare policy design, medically managed coverage, and coordination for people holding public and private insurance. OJK requires a product without risk-sharing and permits a separate, customer-selected option with capped cost-sharing or an annual deductible agreed and written into the policy. The risk-sharing provisions do not apply to emergencies caused by accidents, policy-defined critical illnesses, or emergencies caused by force majeure. Insurers marketing risk-sharing products must present prospective policyholders with a premium or contribution comparison against the no-risk-sharing option at initial coverage or renewal, making price transparency part of product design.
Market Opportunities Table
| Opportunity | Why now | Buyer / lead segment | Recommended play | Main barrier | Likely beneficiaries |
|---|---|---|---|---|---|
| Differentiated medical-policy choices | The 2025 OJK rule requires a no-risk-sharing choice and permits a selected alternative | Individuals and employer groups | Pair comparable benefit options with clear out-of-pocket explanations | Balancing premium affordability and retained claim exposure | Private health insurers |
| Medically managed group coverage | OJK requires medical, digital, and medical-advisory-board capabilities and permits specified partnerships | Employers seeking organized medical benefits | Combine group policies with medical review and optional TPA support | Confidentiality agreements and database retention for at least 10 years after coverage ends | Health insurers and TPAs such as AdMedika, part of Fullerton Health |
| Coordinated supplemental coverage | The Ministry of Health expected future commercial insurer and BPJS data exchange on September 3, 2026 | People holding commercial insurance and JKN | Develop top-up policies around coordinated financing and agreed data exchange | Establishing interoperable data and financing responsibilities | Commercial insurers and BPJS Kesehatan |
| Source: Mordor Intelligence | |||||
The central opening is additional coverage that can be used coherently alongside protection a buyer already holds. The Ministry’s proposed direction makes coordination a relevant design objective, while leaving implementation dependent on workable arrangements between coverage providers. Products that define those responsibilities clearly can make supplemental protection easier to use without relying only on a larger headline benefit.
Recent Industry Developments
- Oct 2026: Jakarta Governor Regulation 26/2026 took effect on October 5, assigning Jakarta’s Health Office to administer registration guidance and JKN contribution payments to BPJS Kesehatan for residents the province enrolls in a specified category.
- Sep 2026: On September 24, Indonesia’s Ministry of Health, DJSN and BPJS Kesehatan selected 4 JKN reform-pilot sites. Pilots in Bandung, Makassar, Tulungagung and Muara Enim were planned for up to 12 months.
- Sep 2026: Indonesia’s Ministry of Health and OJK reported that 50 insurers and 70 hospitals signed cooperation agreements to strengthen health-service financing.
Research Methodology Framework and Report Scope
Market Definition and Coverage
Indonesia health and medical insurance market measures annual gross written premiums and public health-scheme contributions for medical coverage in Indonesia. It covers private and social health protection for inpatient, outpatient and outpatient drug benefits, sold to individuals or employer groups through direct and third-party channels.
Scope exclusions: Personal-accident riders, stand-alone critical-illness insurance, micro-travel insurance, and accident-only policies are excluded.
Segmentation Overview
- By Insurance Product Type
- Private Medical Insurance (PMI)
- Individual Policy Coverage
- Group Policy Coverage
- Public / Social Security Schemes
- Private Medical Insurance (PMI)
- By Distribution Channel
- Brokers / Agents
- Banks (Bancassurance)
- Direct-to-Consumer
- Other Channels (Affinity, Associations, etc.)
- By End-user Segment
- Individuals / Households
- SMEs
- Large Corporates
Data Sources, Market Sizing, and Validation
Desk Research
The market boundary and premium base can be examined through sources such as Otoritas Jasa Keuangan (OJK) insurance statistics, Dewan Jaminan Sosial Nasional (DJSN) JKN monitoring reports, World Health Organization analysis of Indonesia's JKN financing, and IFG Progress insurance reporting. These sources describe commercial health premiums, public enrollment and contribution activity, claims pressure, and changes in medical-insurance business that help distinguish the public and private components of the market.
Company annual reports, insurer product disclosures, investor materials, and reputable financial press can add evidence on group benefits, distribution routes, underwriting and claims trends. These sources are not exhaustive, and further sources inform collection, validation and clarification.
Primary Interviews and Surveys
A structured interview and survey program would seek input from Indonesian health insurers, public-scheme and insurance administrators, brokers, employer benefit leads, and healthcare network or claims specialists. Respondents would check secondary findings on premium drivers, policy use, channel roles and segment development, while clarifying how JKN contributions and private premiums are recorded. Where evidence is incomplete or inconsistent, the analyst would compare respondent explanations with published financial and regulatory data and retain only estimates that can be triangulated across independent evidence.
Distribution of primary research fieldwork respondents
| Company type | Respondent position | Region |
|---|---|---|
| Top tier: 34% | CXOs: 20% | |
| Mid tier: 42% | Functional/Unit leaders: 35% | |
| Smaller Players: 24% | Managers: 45% |
Market-Sizing & Forecasting
The analyst would estimate Indonesia's 2027 market value from annual private medical gross written premiums plus public health-scheme contributions, then forecast to 2032 using a top-down model anchored in insurer premium trends and JKN financing. Key indicators would include OJK-reported health premiums, JKN contribution income and active membership, medical claims and cost trends, employer coverage demand, and household ability to sustain private cover. These indicate price, covered exposure and public contribution growth. Forecast values would use scenario analysis informed by premium growth and membership trends, with primary respondents checking the direction and practical role of each variable rather than supplying unsupported totals. Segment shares would be built from published product, distribution and customer evidence, checked against premium totals, while selective bottom-up checks would compare sampled insurer or channel premiums with the modeled pool. Gaps in those checks would be investigated against reporting periods and definitions, then resolved through triangulation or excluded from the roll-up if evidence could not support a comparable value.
Data Validation & Update Cycle
Analysts would triangulate OJK premium data, JKN contribution and membership signals, company disclosures and field evidence, then investigate anomalies in year-on-year movement, segment shares and differences between public and private series before sign-off. A second review would check calculations, boundaries, units and source dates, with re-contact triggered by conflicting definitions, unexplained movements or missing coverage information. The model would be refreshed annually, revisited between cycles when material regulatory, pricing or funding events change the evidence, and given a fresh pre-delivery review.
Mordor Intelligence's Indonesia Health and Medical Insurance Market Estimate Compared With Other Published Estimates
Indonesia health and medical insurance market measures annual gross written premiums and public health-scheme contributions for medical coverage in Indonesia. Key indicators would include OJK-reported health premiums, JKN contribution income and active membership, medical claims and cost trends, employer coverage demand, and household ability to sustain private cover.
Key Gap Drivers are addressed through a consistent transaction boundary, market-specific demand inputs and cross-checks across the study. Analysts would triangulate OJK premium data, JKN contribution and membership signals, company disclosures and field evidence, then investigate anomalies in year-on-year movement, segment shares and differences between public and private series before sign-off.
Benchmark comparison
| Source | Market Size | Gaps in Research Methodology |
|---|---|---|
| Mordor Intelligence | USD 1.9 B (2027) | |
| Global Consultancy A | USD 2.4 B (2025) | At its 2025 base, this estimate is 26.3% above this report's 2027 value of USD 1.9 B, 2 years later. |
| Global Advisory Firm B | USD 0.91 B (2024) | At its 2024 base, this estimate is 52.1% below this report's 2027 value of USD 1.9 B, 3 years later. |
Mordor Intelligence ties the estimate to the study’s defined coverage and demand model. Analysts would triangulate OJK premium data, JKN contribution and membership signals, company disclosures and field evidence, then investigate anomalies in year-on-year movement, segment shares and differences between public and private series before sign-off.
Key Questions Answered in the Report
What is the Indonesia health and medical insurance market size and growth outlook?
The size is expected to increase from USD 1.77 billion in 2026 to USD 1.9 billion in 2027 and reach USD 2.77 billion by 2032, at a CAGR of 7.85% during 2027-2032.
What drives demand for medical coverage in Indonesia?
JKN participation, employer-cover repricing, and usable private top-ups support demand. BPJS Kesehatan reported 31 supplemental-insurer partners in 2026, with coordination requiring active JKN and supplemental policies and a facility contracted with both.
Which insurance product segment leads in Indonesia?
Public and social security schemes led with 71.21% of the market in 2026. Private medical insurance is forecast to grow fastest at a CAGR of 9.4% during 2027-2032.
Who are the major health-insurance participants in Indonesia?
Major participants include BPJS Kesehatan, Prudential Indonesia, Allianz Life Indonesia, AIA Financial Indonesia, and AXA Mandiri Financial Services.
What is the main challenge for Indonesian medical insurers?
The general-insurer health-insurance claims ratio rose from 58.2% at the end of 2024 to 67.3% at the end of 2025. Higher claims burdens can constrain benefit expansion and underwriting returns.
How does health-insurance access vary across Indonesia?
Jakarta reported 10.87 million JKN participants in June 2026, while interviews in Negeri Liang, Central Maluku, identified limited understanding of JKN procedures and benefits.