India Kitchen Appliances Market Analysis by Mordor Intelligence
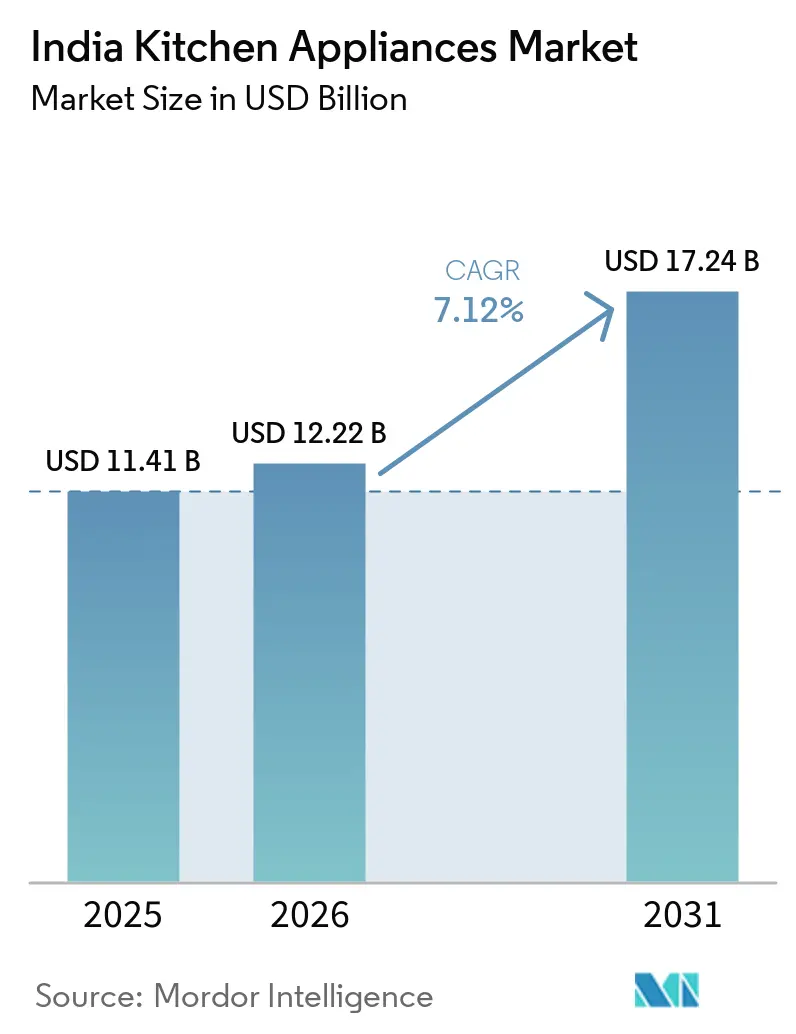
The India kitchen appliances market size is expected to increase from USD 12.22 billion in 2026 to USD 13.09 billion in 2027 and reach USD 18.63 billion by 2032, growing at a CAGR of 7.31% over 2027-2032.
Digital access and local manufacturing can broaden the ways households in India add new kitchen functions. The West Asia conflict following US-Israel strikes on Iran in February 2026 and March disruption of Strait of Hormuz shipping added cost and supply pressure. LPG supply and booking concerns in India from March 2026 also increased the appeal of electric cooking. Suppliers must offset freight and component cost pressure while preserving affordable entry points for functional upgrades. Efficient refrigerators can compete for replacement spending, while countertop appliances offer a separate route to additional cooking functions.
Key Report Takeaways
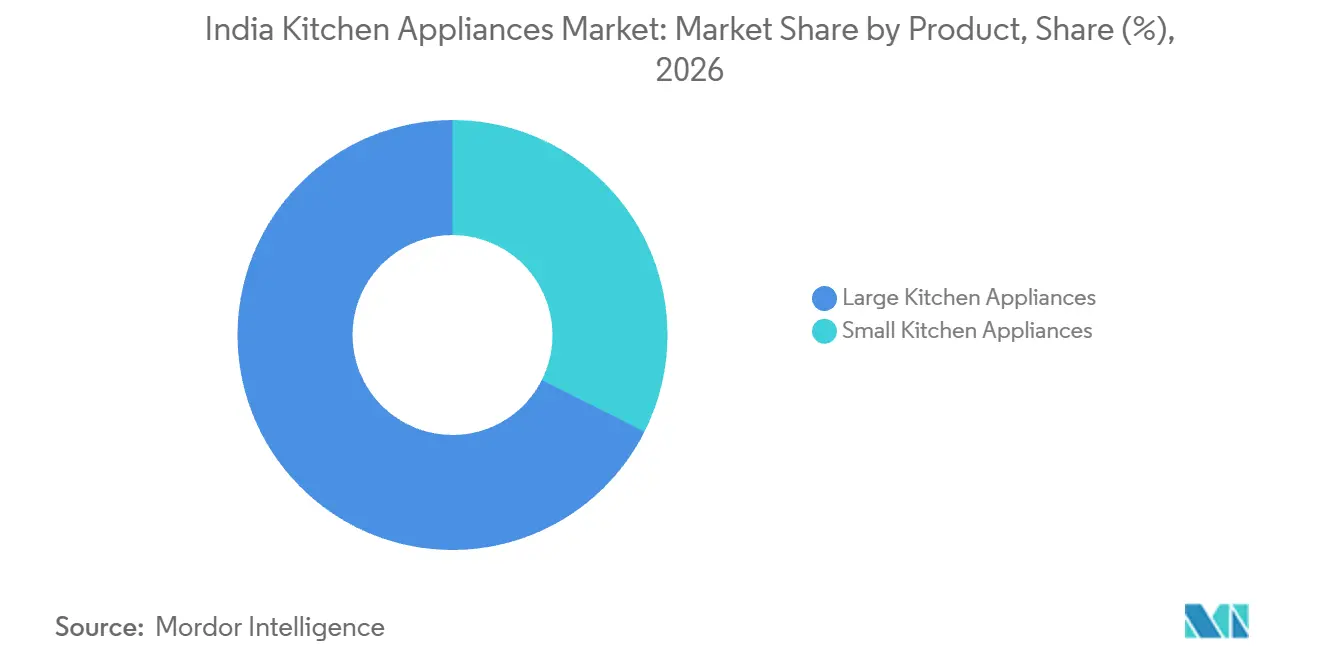
- By product, large kitchen appliances held a 67.57% India kitchen appliances market share in 2026, while small kitchen appliances are forecast to grow fastest at a 9.05% CAGR over 2027-2032.
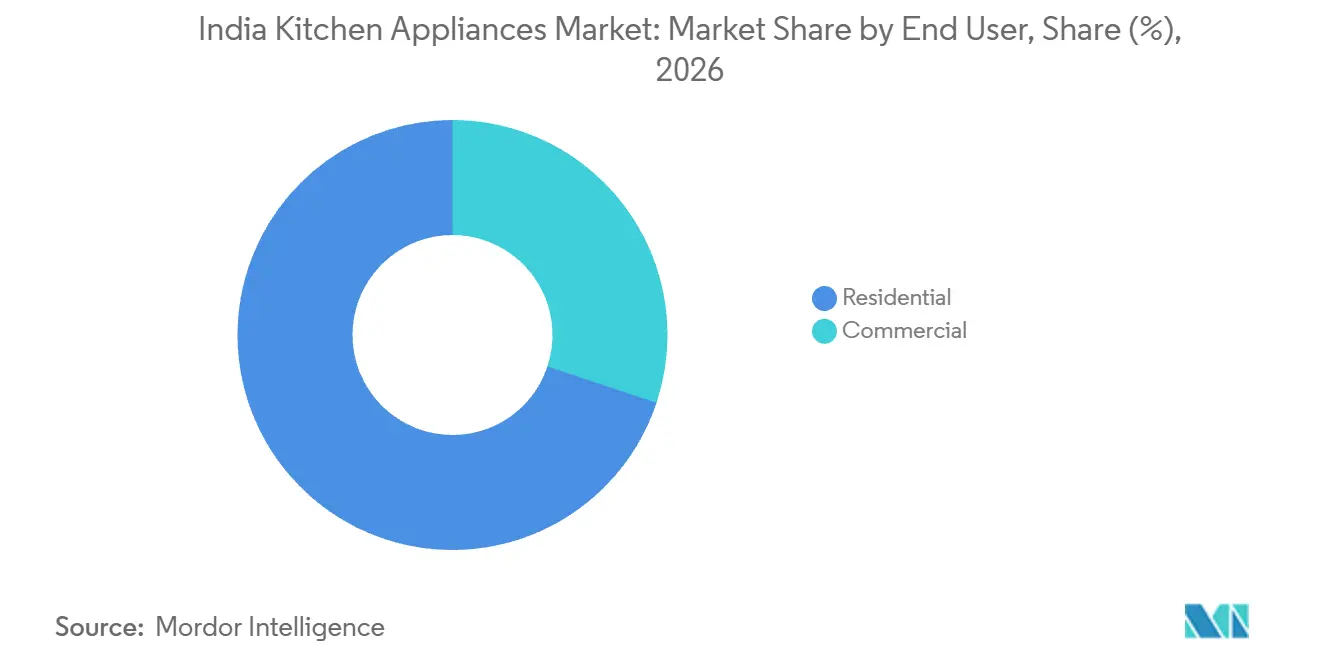
- Among end users, residential buyers accounted for a 69.91% share of the India kitchen appliances market size in 2026, and commercial demand is forecast to expand fastest at a 7.85% CAGR over 2027-2032.
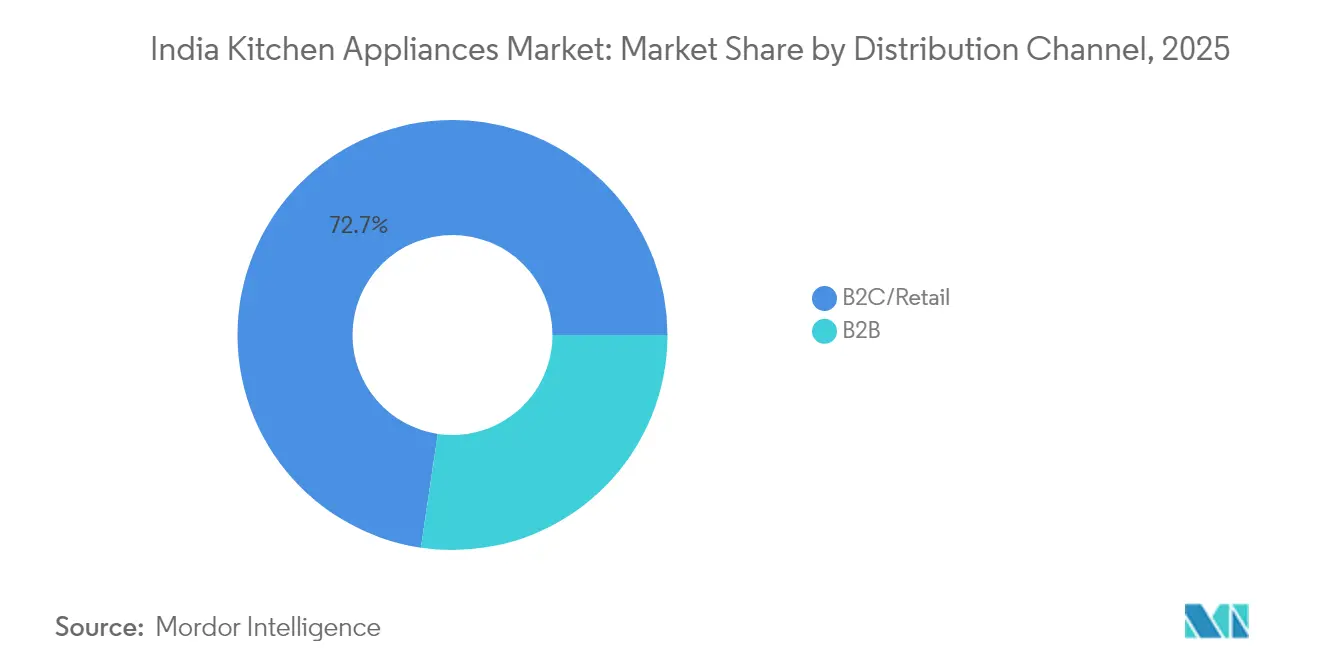
- In distribution, B2C/retail led with 72.6% of sales value in 2026, with B2B sales directly from manufacturers forecast to grow fastest at a 7.47% CAGR over 2027-2032.
- Across geographies, South India led with 33.9% of sales value in 2026, whereas East & North-East India is forecast to grow fastest at an 8.08% CAGR over 2027-2032.
Note: Market numbers in this report are based on Mordor Intelligence's proprietary estimation framework, which combines nine months of actuals with Q4 projections for base year 2026.
Market Trends and Insights
Drivers Impact Analysis of India Kitchen Appliances Market*
| Driver | (~) % Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
|---|---|---|---|
| Rising Urban Middle-Class Disposable Income | +2.8% | Nationwide | Medium term (2-4 years) |
| Growth of E-Commerce & D2C Appliance Brands | +2.6% | Nationwide | Short term (≤ 2 years) |
| Government Push For Domestic Manufacturing | +2.3% | Across Tamil Nadu | Medium term (2-4 years) |
| Energy-Efficiency Regulations Driving Replacements | +1.6% | Nationwide | Medium term (2-4 years) |
| Surge In Health-Centric Cooking Trends | +0.8% | Nationwide | Short term (≤ 2 years) |
| Appliance-As-A-Service & Rental Models Emerging | +0.4% | Nationwide | Long term (≥ 4 years) |
| Source: Mordor Intelligence | |||
Rising Urban Middle-Class Disposable Income
Higher disposable income can widen the range of kitchen tasks an urban middle-income household can afford to automate. MoSPI's provisional FY2025-26 estimate showed national per-capita private final consumption expenditure increasing 8.4% in nominal terms from FY2024-25. For appliance suppliers, the income mechanism works when additional discretionary resources cover a new kitchen function alongside the household's existing equipment. An extra appliance can then represent an expansion in household spending without requiring the buyer to replace a functioning product or accept a higher price for the same task. Complementary cooking functions let suppliers seek another sale from an existing appliance owner before that household needs a replacement.
Growth of E-Commerce & D2C Appliance Brands
Digital distribution can connect first-home appliance purchases with brands that do not depend exclusively on local shelf space. In September 2026, Wonderchef said digital channels' share of its total sales had risen from around 25% to 35% over the preceding 2 to 2.5 years.[1] The company linked that shift to young consumers furnishing their first homes and increasingly preferring online shopping. Beyond Appliances uses its D2C platform, online marketplaces and offline retail to sell smart kitchen appliances. For suppliers, this creates a route to reach appliance buyers during initial kitchen setup rather than waiting for replacement demand through established stores. The commercial opening is therefore broader access at a specific household decision point, with digital channels complementing the physical network instead of requiring its complete displacement.
Government Push For Domestic Manufacturing
Manufacturing incentives can lower the capital hurdle for producers seeking to build a local kitchen-appliance supply base. Tamil Nadu's MSME Policy 2021 makes new micro, small and medium manufacturers in its electrical and electronics thrust sector eligible for subsidy anywhere in the state, including electric mixer and wet-grinder manufacturers. Applicants need Udyam registration, and eligible electrical items must have ISI certification or come from an enterprise with ISO 9001 certification. For enterprises taking effective setup steps on or after February 16, 2021, the incentive can reduce investment exposure when a qualifying producer adds machinery. A lower initial capital burden can support additional product choice as local manufacturing becomes economically feasible. Eligible mixer and wet-grinder producers can secure investment support before additional appliance sales generate a return, provided they meet the registration and certification conditions.
Energy-Efficiency Regulations Driving Replacements
Annual energy labeling gives refrigerator suppliers a performance basis on which to compete for replacement demand beyond purchase price alone. The Ministry of Power set separate star-rating bands for frost-free and direct-cool refrigerators, valid from January 1, 2026, through December 31, 2028. The amendment was made in consultation with the Bureau of Energy Efficiency. These annual energy-consumption bands vary with total refrigerator volume, keeping capacity relevant when comparing rated models. For a buyer considering replacement, this creates a way to weigh storage capacity against ongoing electricity use while manufacturers compete on the combination. The opening favors efficiency improvements that preserve usable capacity, since a lower energy requirement can strengthen the economic case for replacing an older refrigerator.
Restraints Impact Analysis of India Kitchen Appliances Market*
| Restraint | (~) % Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
|---|---|---|---|
| Volatile Raw-Material & Component Costs | -1.5% | Nationwide | Short term (≤ 2 years) |
| Wide Regional Price-Sensitivity Limiting Premiums | -1.1% | Maharashtra, Goa, Karnataka and Kerala | Medium term (2-4 years) |
| Slow Smart-Appliance Uptake Over Data-Privacy Worries | -0.2% | Nationwide | Medium term (2-4 years) |
| Informal Repair Market Prolongs Product Lifecycles | -0.4% | Kolkata, Nagpur and Ranchi | Long term (≥ 4 years) |
| Source: Mordor Intelligence | |||
Volatile Raw-Material & Component Costs
The West Asia conflict following US-Israel strikes on Iran in February 2026 added freight and component cost pressure for appliance suppliers in India. In March 2026, Godrej Enterprises Group reported ocean freight rates rising up to 3 times and imported-component costs increasing amid currency pressures. In a September 24, 2026, communication, LG Electronics India reported year-to-date input-cost increases of 34% for copper, 17% for resin, 24% for steel and 16% for aluminum. LG also reported higher logistics and energy costs and adverse foreign-exchange movements. The pressures span metals, resin, freight, energy and currency, so easing in a single input need not restore the earlier appliance cost base. Suppliers that pass these costs through raise refrigerator replacement prices, while those absorbing them accept thinner unit margins.
Wide Regional Price-Sensitivity Limiting Premiums
Price-sensitive buyers can defer a kitchen-appliance purchase when an expected saving outweighs the benefit of immediate replacement. In August 2025, retailers and durable firms reported consumer-durable buyer queries down by at least 50-60% in markets such as Maharashtra, Goa, Karnataka and Kerala. Consumers were waiting for proposed GST cuts, and the sales lull spanned refrigerators, dishwashers and other kitchen appliances. The anticipated tax saving thus competed with the immediate usefulness of the appliance. In May 2026, LG Electronics India expanded its affordable-premium Essential Series with new 28-liter convertible convection microwave ovens and more price points across its home-appliance range. In the August 2025 episode, waiting for lower prices postponed suppliers' opportunity to earn revenue from refrigerators, dishwashers and other kitchen appliances.
*Our forecasts treat driver/restraint impacts as directional, not additive. The impact forecasts reflect baseline growth, mix effects, and variable interactions.
India Kitchen Appliances Market Segment Analysis
By Product:
Refrigeration Scale And New Cooking RoutinesLarge kitchen appliances accounted for a 67.57% share of the India kitchen appliances market size in 2026, making them the largest segment. LG Electronics India reported that refrigerators contributed 28% of its own product-category revenue in FY2026. The company began producing 674-liter double-door and 790-liter side-by-side refrigerators at its Pune plant during FY2026. For a supplier with substantial refrigerator revenue, these formats broaden the storage requirements its existing product business can address. LG described one of these sizes as one no other brand then produced in India, which gives its Pune plant a differentiated position in large-capacity refrigerators.
Small kitchen appliances are the fastest-growing segment, with a forecast CAGR of 9.05% over 2027-2032. Wonderchef reported that its air-fryer sales growth doubled in 2025. A Chennai household that bought an air fryer in late 2025 described health and convenience as purchase motives and reported lower oil use and fewer takeout orders. That use case connects the appliance decision with meal preparation and spending outside equipment, since food cooked at home can replace ordered meals. Small-appliance suppliers can therefore compete on a repeatable cooking routine, giving buyers a reason to pay for tasks previously served through takeout.



By End User:
Household Ownership And Restaurant InvestmentThe residential segment represented a 69.91% India kitchen appliances market share in 2026 and was the largest segment. In CLASP and the Bureau of Energy Efficiency's 2024 survey across 20 Indian states, 64% of surveyed households owned a refrigerator. The same survey found mixer/grinder ownership in 60% of surveyed households. These category-specific ownership patterns create different commercial tasks, from replacing equipment already in a kitchen to selling a household its first appliance of a particular type. A single upgrade offer cannot address both refrigerator replacement and a household's first mixer/grinder purchase.
Commercial end users form the fastest-growing segment, with a forecast CAGR of 7.85% over 2027-2032. Restaurant Brands Asia added 68 stores in its India operations during FY2026, net of closures. The operator also reported India utility efficiencies through solar and a new broiler in FY2026. Appliance suppliers can address 2 investment needs in a restaurant network, equipping additional kitchens and supplying performance improvements as operators seek better meal-production economics. For these restaurant investments, energy use provides an equipment selection criterion alongside purchase price.

By Distribution Channel:
Retail Coverage And Direct Buyer RelationshipsB2C/retail was the largest segment, accounting for 72.6% of kitchen-appliance sales value in 2026. TTK Prestige reported 711 Prestige Xclusive outlets across 324 towns at March 31, 2026.[2] It added outlets while consolidating and rationalizing the network where necessary during FY2025-26. Compared with 667 outlets a year earlier, the year-end total represented a net gain of 44 despite consolidation. Selective consolidation can preserve resources for outlets serving local demand even as a branded retail network expands into additional locations.
The B2B (directly from the manufacturers) channel is the fastest-growing segment, with a forecast CAGR of 7.47% over 2027-2032. IFB Industries reported commercial dishwashing revenue of INR 391.8 million (USD 4.58 million) in FY2025. In FY2025-26, its Home Appliance Business, which includes commercial appliances, identified institutions, hospitals and hospitality industries alongside dealers and distributors among its customers. Within direct manufacturer sales, agreeing operating requirements with the buyer can connect equipment selection with the work that an institutional kitchen must perform. Direct institutional sales therefore depend on matching dishwashing requirements, not on adding consumer stores.
Geography Analysis
South India Kitchen Appliances Market
South India accounted for 33.9% of the India kitchen appliances market size in 2026, making it the largest regional market. In a March 2025 interview, Wonderchef co-founder and CEO Ravi Saxena described South India as the company's highest-sales market. He reported about 4,000 of its roughly 20,000 retail outlets there and about 30% of company sales, implying higher average sales per outlet than nationally. Keeping the kitchen range available at such productive outlets can protect more sales per location than store count alone would suggest.
East & North-East India Kitchen Appliances Market
East & North-East India is the fastest-growing geography, with a forecast CAGR of 8.08% over 2027-2032. LPG availability and booking concerns provided a specific reason to seek alternatives to gas cooking in Guwahati in March 2026. Over 4 to 5 days that month, Guwahati traders reported daily induction-cooktop sales of 20 to 40 units, compared with their usual one or 2 units, amid those concerns. Induction cooktops, rice cookers and electric kettles sold out quickly in Guwahati shops as households and small establishments sought substitutes for cooking gas.
North India's supplier presence includes TTK Prestige's Roorkee manufacturing unit, part of its broader kitchen and home-appliance network. TTK Prestige places Roorkee among the manufacturing units supplying its store network and reported normal manufacturing there from 3 p.m. on July 11, 2026. West India's refrigerator base expanded in July 2026 when Whirlpool of India inaugurated a line at its Rajnangaon plant in Pune, raising annual plant capacity to 3.4 million units. Defined annual capacity gives refrigerator manufacturing a measurable industrial scale around Pune, with utilization determining how the asset contributes to supply. Roorkee supports TTK Prestige's established store-supply network, while Pune's enlarged refrigerator line creates a separate task of finding demand for additional capacity.
Regulatory Framework and Outlook
The selected-jurisdiction comparison examines India and Tamil Nadu from the perspective of a kitchen-appliance manufacturer subject to the relevant product and operating rules. National conformity requirements cover listed kitchen electrical appliances, including toasters, grills, roasters and range hoods, which must meet Indian Standards and carry the Bureau of Indian Standards (BIS) Standard Mark under license. The Electrical Appliances for Kitchen (Quality Control) Order, 2023 excludes domestically manufactured exports and provides distinct commencement terms for qualifying micro and small enterprises. Separate extended producer responsibility (EPR) duties attach to covered equipment and obligated producers, making product coverage and the firm's regulated role important to the compliance pathway.
Regulatory Table of India Kitchen Appliances Market
| Decision factor | India | Tamil Nadu |
|---|---|---|
| Primary authority | Bureau of Indian Standards for product certification; Central Pollution Control Board (CPCB) for EPR registration | Tamil Nadu Pollution Control Board (TNPCB) for state consent, monitoring and audits; CPCB for EPR registration |
| Key instruments or direction | Electrical Appliances for Kitchen (Quality Control) Order, 2023; E-Waste (Management) Rules, 2022 | State consent and hazardous-waste authorization before CPCB registration; TNPCB monitoring under CPCB guidelines |
| Commercial effect | Conformity and BIS marking for listed products; EPR duties for covered producers | Consent and authorization precede registration; monitoring and audits follow registration |
| Current policy attractiveness | Medium | Medium |
| Future direction of policy attractiveness | Hardening | Hardening |
| Source: Mordor Intelligence | ||
From the manufacturer's perspective, India's Medium rating balances a defined BIS route to market against licensing and applicable producer EPR obligations. Tamil Nadu's Medium rating reflects a defined but multilayered pathway, with state consent and hazardous-waste authorization before CPCB registration and TNPCB monitoring and audits afterward. Applicable producers face recycling targets of 70% of calculated e-waste generation in FY2025-26 and FY2026-27, rising to 80% from FY2027-28, with separate conditions for recent market entrants. The scheduled increase supports Hardening in both jurisdictions, as obligated producers must arrange recycling for a larger proportion of calculated waste generation.
Value Chain Stages
The value chain compares how manufacturers, distributors, retailers and service providers earn from bringing kitchen appliances to Indian users. TTK Prestige reported streamlining manufacturing operations and sourcing processes during FY2025-26. Manufacturing, marketing and distribution of its home and kitchen portfolio, including pressure cookers, cookware and gas stoves, accounted for 44% of FY2025-26 turnover, while other kitchen appliances represented 14%. Each downstream stage adds a different route to supplier revenue and a different point at which delivery or support can fail.
Value Chain Analysis Table of India Kitchen Appliances Market
| Primary activity | Key participants | Value capture | Bottleneck | Resilience response |
|---|---|---|---|---|
| Finished-appliance manufacturing | Appliance producers such as TTK Prestige Ltd. | Finished-appliance sales | Sourcing and assembly schedules can diverge | Link supplier delivery dates to assembly schedules |
| Regional distribution | Producers operating regional sales centers such as TTK Prestige Ltd. | Wholesale appliance sales | Regional replenishment can diverge from factory output | Match dispatch quantities to regional orders |
| Retail sale | Branded-store operators such as TTK Prestige Ltd., and appliance retailers such as Infiniti Retail Ltd. through Croma | Retail appliance sales | Product choice can exceed local display capacity | Coordinate online selection with store availability |
| After-sales service | Producers coordinating authorized service networks such as TTK Prestige Ltd. | Out-of-warranty maintenance and repair fees | Service access can be separated from the original selling outlet | Route repair requests to the authorized network |
| Source: Mordor Intelligence | ||||
TTK Prestige connects manufacturing with company-managed regional sales centers, branded retail and authorized service networks, although the outlets and service centers have different operating roles. This integration makes coordination across handoffs a potential source of advantage, while retailers can earn by selling varied appliance categories. An authorized service network can earn repair income from appliances already sold, while regional centers and retailers depend on continuing equipment sales.
Competitive Landscape
Market Concentration
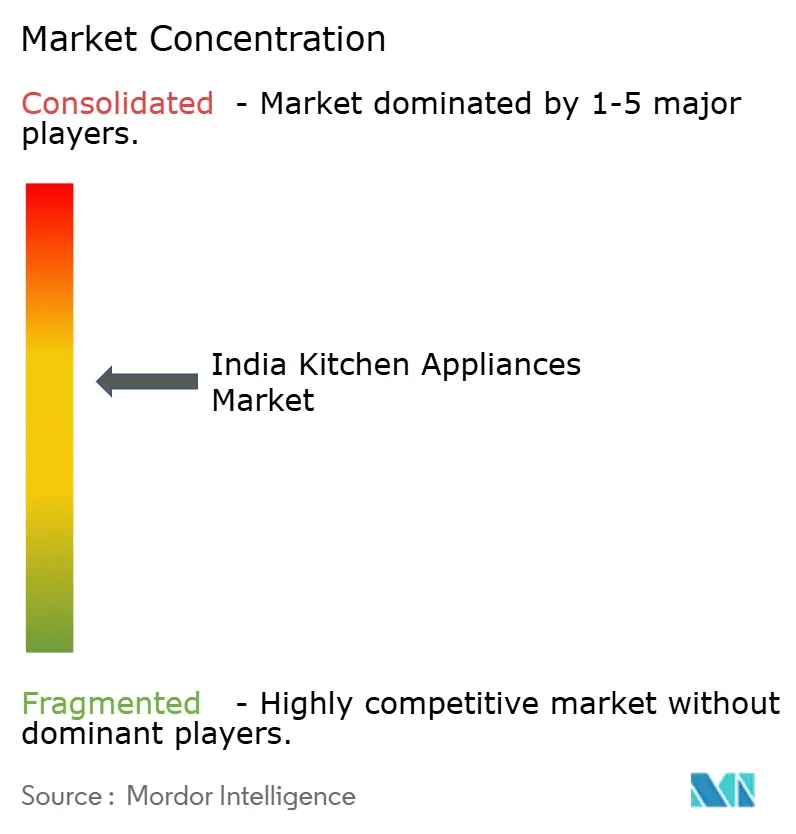
Competition is moderately fragmented, with established kitchen specialists and broader appliance brands competing across overlapping product categories. TTK Prestige Ltd., Versuni India Home Solutions Ltd., Bajaj Electricals Ltd., Havells India Ltd. and Butterfly Gandhimathi Appliances Ltd. are major participants. Bajaj Electricals sells mixer grinders, Havells India entered cooktops, hobs and chimneys during FY2024-25, and Butterfly Gandhimathi Appliances rolled out more than 40 Idea First Series SKUs by the quarter ended June 30, 2025. In Q3 FY2025-26, TTK Prestige executives reported growth in air fryers, hoods and hobs, mixer grinders and cooktops, although cooktop growth was comparatively muted. Category breadth can spread exposure to uneven cooking-format demand, but established brands still need commercial performance in each category.
In March 2026, Versuni India added an air-fryer motor production line in Chennai with initial annual capacity of 750,000 units. The company, which sells Philips and Preethi appliances in India, was also scaling up capacity at its Ahmedabad appliance plant in March 2026. The parallel projects add a component-manufacturing step while expanding appliance capacity, committing resources to different parts of the production process. Versuni described the line as an effort to deepen localization and build a stronger component ecosystem in India, making domestic component capability part of its competitive strategy in air fryers.
Isler inaugurated a 30,000-square-foot facility in Greater Noida in November 2025, equipped to produce built-in kitchen and home appliances such as hoods and hobs. The manufacturing startup was supported by Häfele India. Range hoods are among the kitchen appliances that must meet listed Indian Standards and carry the BIS Standard Mark under license, so an entrant's hood line needs certification before it can be sold domestically. A domestic built-in appliance offer for kitchen fit-out buyers therefore needs both a production base and BIS certification.
India Kitchen Appliances Industry Leaders
-
TTK Prestige Ltd.
-
Versuni India Home Solutions Ltd.
-
Bajaj Electricals Ltd.
-
Havells India Ltd.
-
Butterfly Gandhimathi Appliances Ltd.
- *Disclaimer: Major Players sorted in no particular order
India Kitchen Appliances Market Companies Covered in this Report
- TTK Prestige Ltd.
- Versuni India Home Solutions Ltd.
- Bajaj Electricals Ltd.
- Havells India Ltd.
- Butterfly Gandhimathi Appliances Ltd.
- LG Electronics India Ltd.
- Samsung India Electronics Pvt. Ltd.
- Whirlpool of India Ltd.
- Voltbek Home Appliances Pvt. Ltd.
- Godrej Appliances
- Panasonic India Pvt. Ltd.
- Usha International Ltd.
- IFB Industries Ltd.
- Crompton Greaves Consumer Electricals Ltd.
- Inalsa Home Appliances
- Morphy Richards India
- Kenstar
- Glen Appliances Pvt. Ltd.
- Maharaja Whiteline
- Hindware Home Innovation Ltd.
- Versuni India Home Solutions Ltd. (Preethi)
Key Opportunities for Market Participants
The opportunities compare first-time air-fryer adoption, younger urban digital buyers and upgrades by existing owners. In June 2026, Amazon India reported that nearly 9 in 10 air-fryer purchasers on its platform were first-time buyers.[3] An initial purchase needs an accessible way to justify adding a cooking format, while an upgrade needs a meaningful gain over equipment already owned. Separating these offers can help a supplier price for wider household adoption while giving existing owners a distinct reason to replace.
Market Opportunities Table of India Kitchen Appliances Market
| Opportunity | Why now | Buyer / lead segment | Recommended play | Main barrier | Likely beneficiaries |
|---|---|---|---|---|---|
| Affordable first air fryer | Amazon India reported a predominantly first-time platform buyer base in June 2026 | First-time residential purchasers | Offer entry models with clear cooking-task guidance | Affordability was a reported constraint in June 2026 | Air-fryer brands such as Prestige and Havells |
| Differentiated digital selling | Manufacturers reported rising demand from younger urban digital-first consumers in June 2026 | Younger urban residential buyers | Use cooking-task demonstrations to distinguish models | Crowded choice among established and internet-first air-fryer brands | Internet-first air-fryer brands such as Inalsa |
| Value-led air-fryer upgrades | Upgrade interest from many early adopters was reported in June 2026 | Existing residential air-fryer owners | Demonstrate incremental capability relative to the buyer's installed model | Added benefit must justify replacement spending | Established air-fryer brands such as Prestige and Havells |
| Source: Mordor Intelligence | |||||
Interest from existing owners creates a different revenue opportunity from acquiring households that do not yet own an air fryer. An upgrade must justify new spending against existing cooking capability, which can make a demonstrable functional change valuable alongside entry-level affordability. Maintaining distinct entry and replacement offers can therefore let air-fryer brands pursue wider ownership and repeat purchases without requiring every buyer to justify the same premium.
Recent Industry Developments in India Kitchen Appliances Market
- Oct 2026: Beyond Appliances, a smart kitchen appliance maker, raised a Series B led by Fireside Ventures, with participation from Dharana Capital and other investors. The company planned to use the funding for research and development, a new manufacturing plant and entry into 2 additional kitchen-appliance categories.
- Jul 2026: Whirlpool of India inaugurated a production line at its Pune facility, raising the Rajnangaon plant's annual refrigerator capacity to 3.4 million units.
- Mar 2026: TTK Prestige inaugurated a kitchen-appliance innovation center in Bengaluru focused on consumer-centered design, technology and product development, and validation and scaling of new segment opportunities.
India Kitchen Appliances Market Report Scope and Research Methodology
Market Definition and Coverage
India kitchen appliances market measures annual spending on appliances designed for food preparation, cooking, ventilation, refrigeration, and related kitchen tasks. It counts finished-appliance sales to residential and commercial buyers across all of India through B2C retail and direct manufacturer-to-buyer sales, valued in USD for each stated year.
Scope exclusions: Non-kitchen home appliances, kitchen furniture and cabinetry, standalone cookware and utensils that are not electrically or mechanically powered appliances, and separately sold repair services and spare parts are excluded.
Segments Covered in This Report
- By Product
- Large Kitchen Appliances
- Refrigerators & Freezers
- Dishwashers
- Range Hoods
- Cooktops
- Ovens
- Other Large Kitchen Appliances
- Small Kitchen Appliances
- Food Processors
- Juicers and Blenders
- Grills and Roasters
- Air Fryers
- Coffee Makers
- Electric Cookers
- Toasters
- Electric Kettles
- Countertop Ovens
- Other Small Kitchen Appliances
- Large Kitchen Appliances
- By End User
- Residential
- Commercial
- By Distribution Channel
- B2C/Retail
- Multi-brand Stores
- Exclusive Brand Outlets
- Online
- Other Distribution Channels
- B2B (directly from the manufacturers)
- B2C/Retail
- By Geography
- North India
- South India
- West India
- East & North-East India
Data Sources, Market Sizing, and Validation
Desk Research
Illustrative public sources such as MoSPI's HCES 2023-24 and its household microdata describe household spending and refrigerator possession, while the CLASP-BEE residential survey reports appliance ownership and use across India. Bureau of Energy Efficiency material provides context on appliance-efficiency standards and labeling.
Company annual reports, investor materials, audited filings, and reputable Indian business press can cross-check product revenue, production capacity, price changes, retail expansion, and channel mix, while helping distinguish kitchen-appliance sales from broader consumer-durable totals. The named sources are not exhaustive, and further sources inform collection, validation, and clarification.
Primary Interviews and Surveys
Primary research gathers input from appliance manufacturers, distributors, retailers, and residential and commercial buyers in India, with senior executives, category or sales leaders, and operating managers able to explain pricing, product mix, channel movement, and purchase timing. Structured interviews and buyer surveys test secondary findings at the variable level, clarify gaps in reported sales or coverage, and distinguish replacement purchases from first-time adoption. Conflicting evidence is checked against company disclosures, channel observations, and independent household or policy indicators before an assumption is retained.
Distribution of primary research fieldwork respondents
| Company type | Respondent position | Region |
|---|---|---|
| Top tier: 30% | CXOs: 20% | |
| Mid tier: 45% | Functional/Unit leaders: 35% | |
| Smaller Players: 25% | Managers: 45% |
Market-Sizing & Forecasting
The model estimates annual India value from finished-appliance spending at the final buyer transaction, counting retail or direct manufacturer sales once. A top-down estimate starts with broad appliance demand and applies evidence-based product, end-user, channel, and regional shares, while selective bottom-up checks multiply sampled average selling prices by unit volumes for major product groups and compare supplier or channel roll-ups with the national total. Key indicators include household consumption and durable ownership from MoSPI, residential use and appliance ownership from the CLASP-BEE survey, product revenue and capacity disclosures, online and physical retail coverage, and price or product-mix changes. These indicators connect household formation and replacement demand to value and segment shares. Multivariate regression can relate historical market value to income and household demand, product prices and mix, and channel or production signals, with scenario analysis for policy or input-cost changes. Experts check whether each projected variable and its product-level implication fits reported operating conditions, while missing observations are bridged from the closest comparable period and tested across a stated range.
Data Validation & Update Cycle
Analysts triangulate independent household, company, channel, policy, and trade signals, then check segment totals, year-to-year movements, implied average prices, and unusual differences between reported sales and operating indicators. A reviewer traces material variances to source coverage, timing, unit, or transaction stage, and analysts re-contact relevant respondents when a product boundary, price movement, or channel change remains unclear. The evidence is refreshed annually, reviewed between cycles after material regulatory, supply, or demand events, and subjected to a fresh source and calculation pass immediately before delivery.
Mordor Intelligence's India Kitchen Appliances Products Market Size Measured Against Other Published Estimates
Published estimates can differ in the transactions and products they count and the inputs used to model demand. India kitchen appliances market measures annual spending on appliances designed for food preparation, cooking, ventilation, refrigeration, and related kitchen tasks.
Key Gap Drivers include the study's defined coverage and market-specific modeling choices. Key indicators include household consumption and durable ownership from MoSPI, residential use and appliance ownership from the CLASP-BEE survey, product revenue and capacity disclosures, online and physical retail coverage, and price or product-mix changes.
Benchmark comparison
| Source | Market Size | Gaps in Research Methodology |
|---|---|---|
| Mordor Intelligence | USD 13.09 B (2027) | |
| Industry Prospectus A | USD 2.93 B (2026) | At its 2026 base, this estimate is 77.6% below this report's 2027 value of USD 13.09 B, 1 year later. Its listed basket omits refrigerators, freezers, dishwashers, and chimneys while including non-stick cookware. |
| Market Research Firm B | USD 0.8 B (2026) | At its 2026 base, this estimate is 93.9% below this report's 2027 value of USD 13.09 B, 1 year later. It measures connected smart kitchen appliances, a subset of finished kitchen-appliance sales. |
Mordor Intelligence's analysts triangulate independent household, company, channel, policy, and trade signals, then check segment totals, year-to-year movements, implied average prices, and unusual differences between reported sales and operating indicators.
Key Questions Answered in the Report
What is the India kitchen appliances market size and growth outlook?
The size is expected to reach USD 13.09 billion in 2027 and USD 18.63 billion by 2032, with a 7.31% CAGR over 2027-2032.
What is driving demand for kitchen appliances in India?
Online reach and first-home purchases support appliance demand. In September 2026, Wonderchef said digital channels' share of its total sales had risen from around 25% to 35% over the preceding 2 to 2.5 years.
Which product segment leads Indian kitchen-appliance sales?
Large kitchen appliances led with 67.57% of sales value in 2026, while small kitchen appliances are forecast to grow fastest at a 9.05% CAGR over 2027-2032.
Which companies are major kitchen-appliance suppliers in India?
Major suppliers include TTK Prestige Ltd., Versuni India Home Solutions Ltd., Bajaj Electricals Ltd., Havells India Ltd. and Butterfly Gandhimathi Appliances Ltd.
What is the main cost challenge for India's kitchen-appliance suppliers?
Input inflation can make replacement appliances more expensive. LG Electronics India reported year-to-date material, logistics and energy cost pressure in September 2026.
Which Indian regions lead kitchen-appliance sales and growth?
South India led with 33.9% of sales value in 2026, while East & North-East India is forecast to grow fastest at an 8.08% CAGR over 2027-2032.