
India Cloud Computing Market Size and Share
India Cloud Computing Market Analysis by Mordor Intelligence
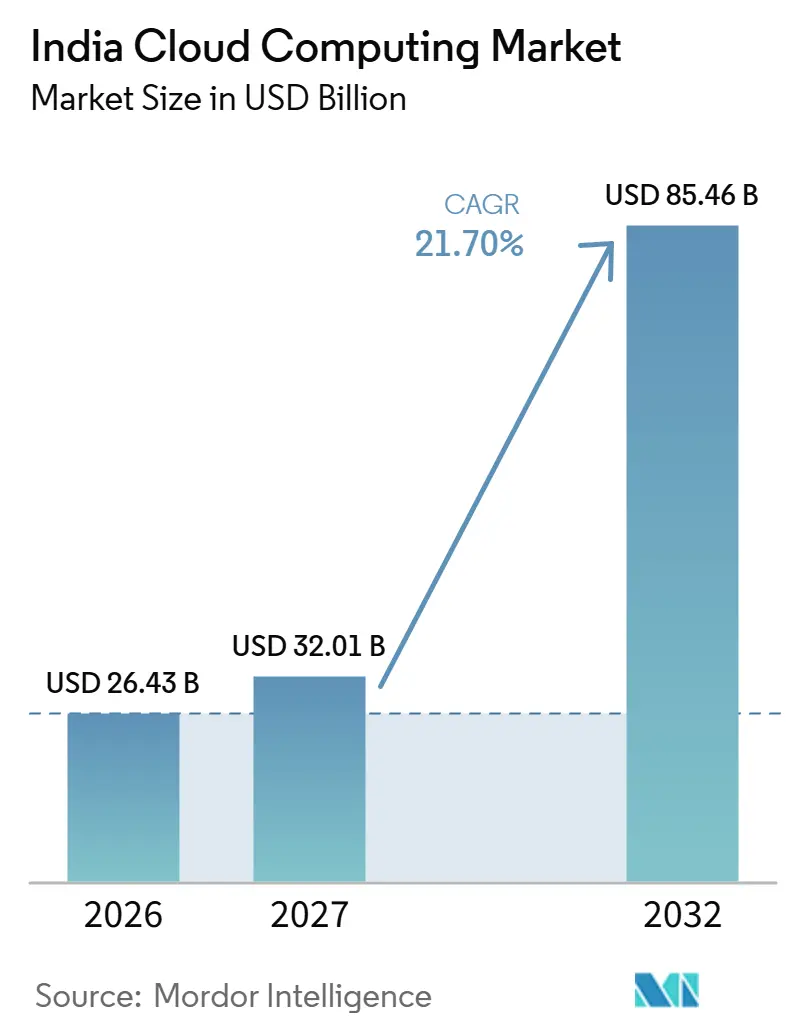
The India cloud computing market size is expected to increase from USD 26.43 billion in 2026 to USD 32.01 billion in 2027 and reach USD 85.46 billion by 2032, growing at a CAGR of 21.7% over 2027-2032.
India’s expansion is tied to enterprise ERP modernization and digital-government services that turn cloud access into an operating requirement. Local infrastructure additions expand deployment choices, while sovereignty concerns constrain the services some enterprise buyers will use. Provider responses include in-country AI capacity announcements and proposed hybrid arrangements for sensitive workloads in government data centers. These responses address placement constraints, but legacy-system dependencies and skills shortages can delay enterprise migration. For enterprise providers, completed application transitions make continuing cloud access commercially relevant beyond one-time migration work.
Key Report Takeaways
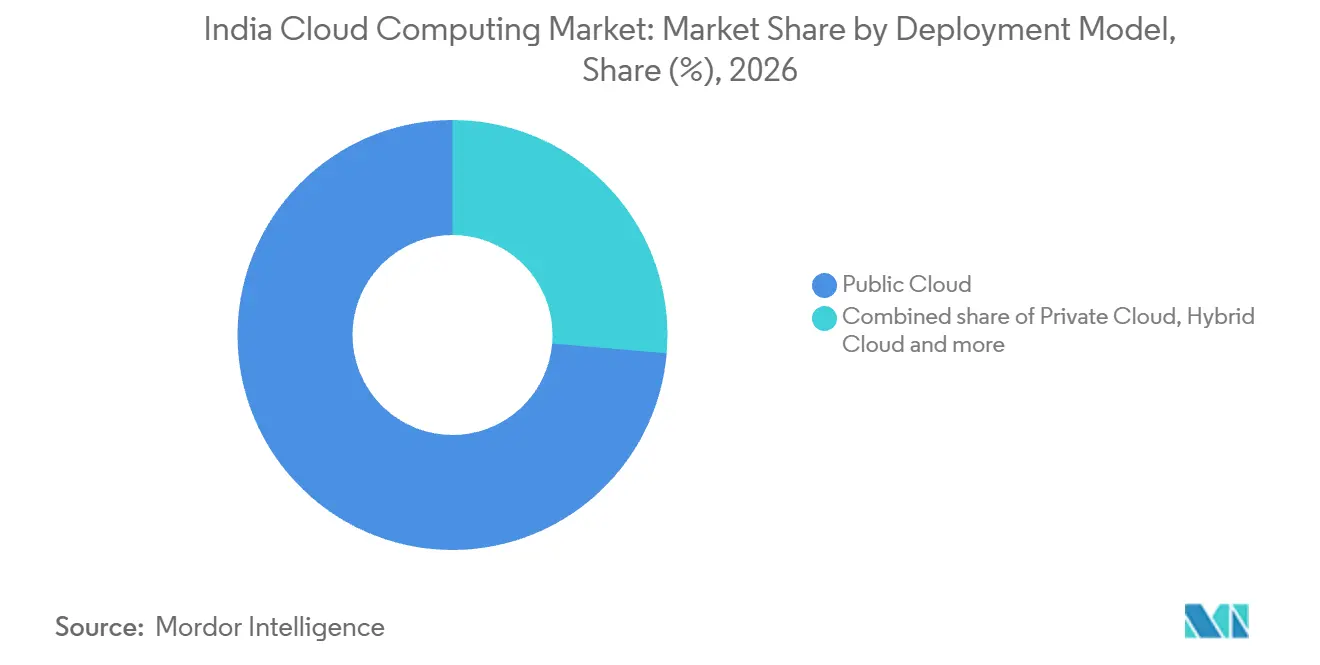
- By deployment model, public cloud held a 73.64% India cloud computing market share in 2026, while hybrid cloud is the fastest-growing segment at a 27.8% CAGR over 2027-2032.
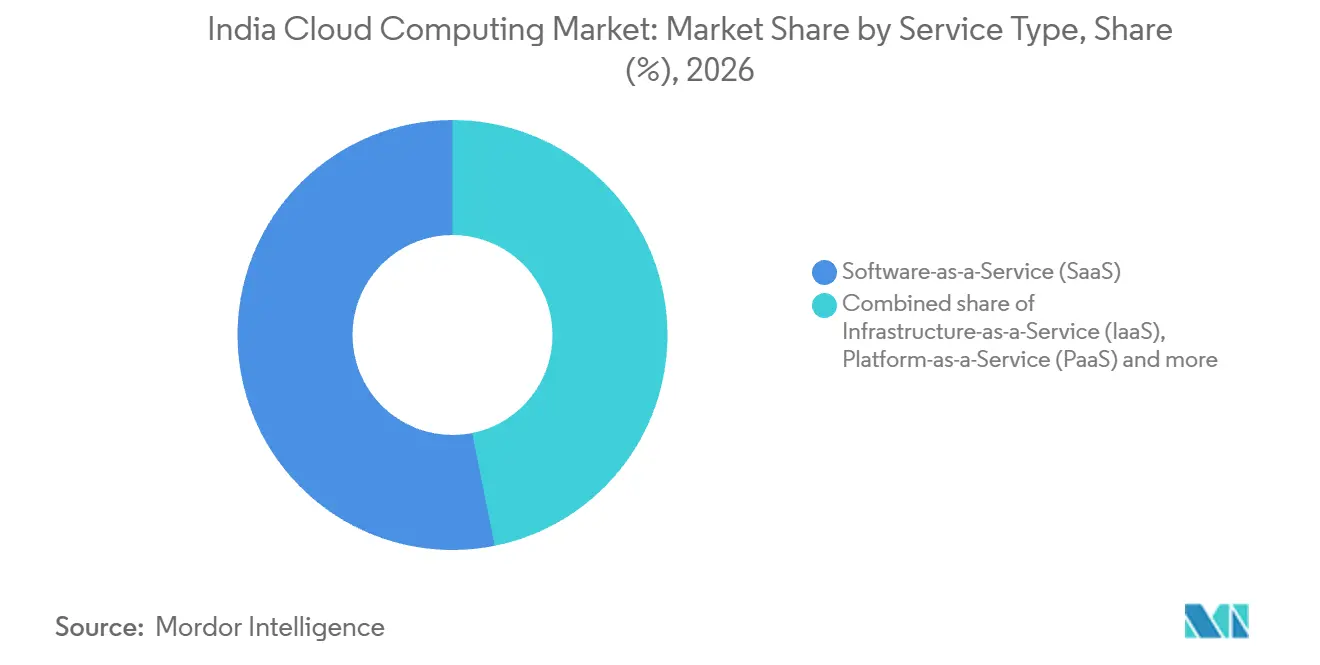
- Across service types, SaaS accounted for a 53.15% share of the India cloud computing market size in 2026, with PaaS forecast to grow fastest at a 30.9% CAGR over 2027-2032.
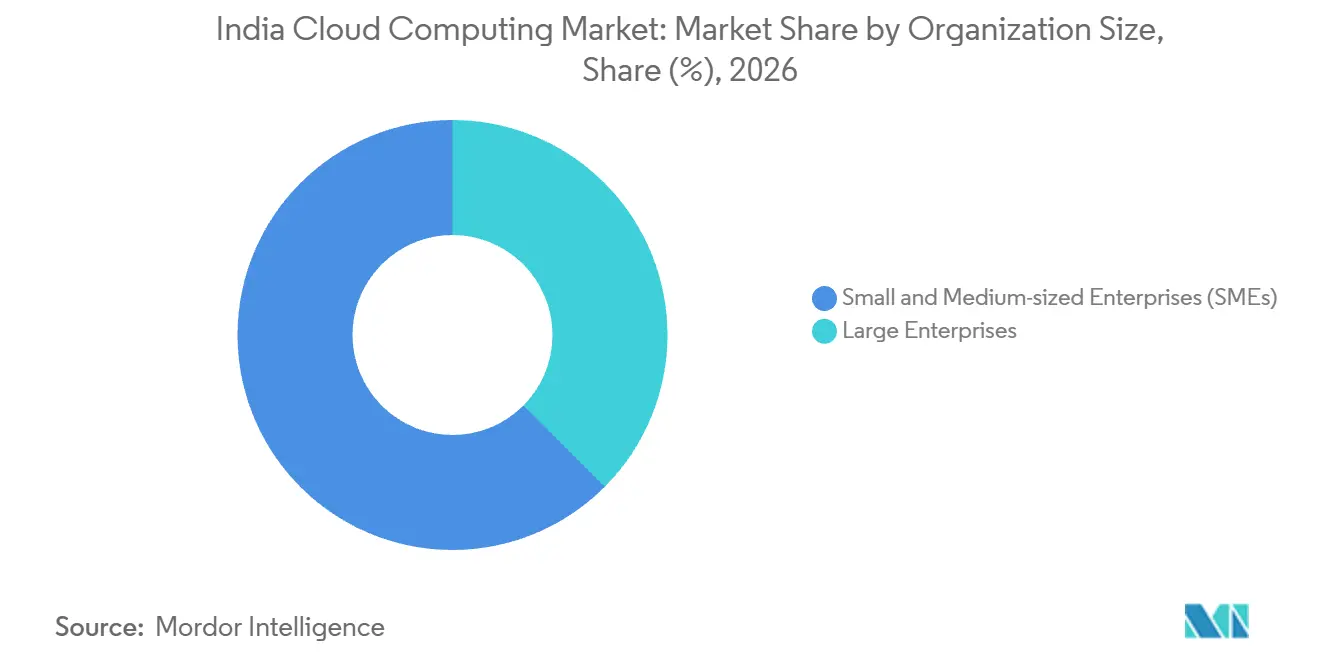
- Among organization sizes, SMEs led with a 62.53% share in 2026 and are also the fastest-growing segment, at a 23.9% CAGR over 2027-2032.
- Within industry verticals, BFSI held the largest share at 18.32% in 2026, while the healthcare and life-sciences segment is forecast to grow fastest at a 28.7% CAGR over 2027-2032.
- Workload spending was led by core compute and storage with a 40.08% share in 2026, while AI, machine learning, and generative AI form the fastest-growing segment, at a 34.8% CAGR over 2027-2032.
- Regionally, West led with a 37.9% share in 2026, and South is expected to grow fastest.
Note: Market numbers in this report are based on Mordor Intelligence's proprietary estimation framework, which combines nine months of actuals with Q4 projections for base year 2026.
Projections can easily extend beyond country and regional trends as they are defined by movement across the full international system. Mordor Intelligence's worldwide cloud computing market outlook captures this forward trajectory.
Market Trends and Insights
Drivers Impact Analysis of India Cloud Computing Market*
| Driver | (~) % Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
|---|---|---|---|
| Government cloud-first and Digital India policies | +6% | Nationwide | Long term (≥ 4 years) |
| Digital transformation boom across enterprises | +7% | Nationwide | Medium term (2-4 years) |
| Explosive build-out of hyperscale and edge datacenters | +5% | Guwahati in Assam | Long term (≥ 4 years) |
| Sovereign-cloud push by RBI for regulated sectors | +4% | Nationwide | Medium term (2-4 years) |
| Generative-AI workloads demanding GPU-rich instances | +3% | Nationwide | Short term (≤ 2 years) |
| Rise of industry-cloud platforms for compliance-heavy verticals | +2% | Hyderabad in southern India | Medium term (2-4 years) |
| Source: Mordor Intelligence | |||
Government cloud-first and Digital India policies
Government cloud policies can increase demand by extending a shared platform across departmental services. By June 2026, government departments’ adoption of India’s MeghRaj cloud platform had risen to 2,323 from 342 in 2015-16.[1] MeghRaj powered platforms including DigiLocker, MyGov, and the National Scholarship Portal. Department-level adoption gives the platform an organizational reach beyond any single flagship application. The nearly sevenfold increase in adopting departments broadens the public-service base that needs continuing operation after launch, making sustained availability the demand consequence of adoption.
Digital transformation boom across enterprises
Enterprise digital transformation creates an operational cloud customer when a core application moves into a production cloud environment. GAIL completed a transition from its legacy ECC system to SAP S/4HANA Cloud on a cloud platform and went live on June 25, 2025. The implementation and migration were completed within the scheduled one-year period. SAP supplied the ERP software, while GAIL operated the enterprise system. Standalone migration fees fall outside the cloud-service spending measured here, so the continuing cloud access that runs the live ERP system is the relevant demand after go-live.
Explosive build-out of hyperscale and edge datacenters
Physical capacity expansion gives cloud operators room to deploy services through both hyperscale facilities and regional infrastructure. In H1 2026, hyperscale pre-committed capacity accounted for 82% of India’s 101 MW of data-center absorption, which was more than 20% above the three-year average. At its February 2026 inauguration, Yotta Data Services said the National Data Center North East Region in Guwahati supported 200 racks at a 2 MW IT load. Yotta built and operated the Assam facility for the National Informatics Centre. Pre-committed hyperscale capacity shows large operators securing space ahead of use, while Guwahati adds government-commissioned capacity in the North East, providing deployment infrastructure for commercial and public-sector cloud services.
Sovereign-cloud push by RBI for regulated sectors
The RBI-backed cloud initiative connects financial-sector technology adoption with governance and data-localization requirements. During FY2025-26, IFTAS, RBI’s wholly owned subsidiary, launched a beta of the Indian Financial Sector cloud with minimum viable product services and onboarded 9 entities.[2] RBI entrusted IFTAS with building the facility to address modern technology adoption, governance, and data localization. An operating beta gives that policy direction a service-delivery mechanism, creating a route for financial-sector users whose cloud decisions depend on these requirements. The near-term opportunity lies in deepening use by financial-sector organizations as the beta develops, making the maturity of usable services more commercially decisive than the initial onboarding count.
Restraints Impact Analysis of India Cloud Computing Market*
| Restraint | (~) % Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
|---|---|---|---|
| Escalating cyber-attack surface and data-sovereignty risks | -2% | Nationwide | Short term (≤ 2 years) |
| Legacy-IT migration complexity and skills deficit | -1.8% | Nationwide | Medium term (2-4 years) |
| Grid-power unreliability driving up datacenter opex | -1% | Nationwide | Long term (≥ 4 years) |
| Restricted domestic semiconductor supply chain | -0.5% | Nationwide | Short term (≤ 2 years) |
| Source: Mordor Intelligence | |||
Escalating cyber-attack surface and data-sovereignty risks
Data sovereignty can restrict a cloud provider’s addressable demand before its technical performance enters consideration. In Everpure’s June 2026 survey of 300 Indian large-enterprise leaders, 39% said they were already limiting their use of SaaS providers reliant on non-domestic infrastructure. Aviatrix’s April 2025 survey of 407 Indian enterprise IT professionals at organizations with over 2,000 employees found that 85% reported a cloud security incident in the prior 12 months. Infrastructure location therefore affects the services these enterprise buyers will use, while security exposure adds a separate operating burden. For providers reliant on non-domestic infrastructure, functional improvements alone may leave a material obstacle to winning these enterprise workloads.
Legacy-IT migration complexity and skills deficit
Moving an application into cloud infrastructure does not by itself remove the dependencies that make modernization difficult. In CIO&Leader’s 2025 survey, 89.3% of Indian enterprise technology leaders called application re-hosting or migration a critical hurdle because of complexity and legacy dependencies.[3] The same survey found that 66% of enterprise respondents cited limited talent availability as an application-modernization challenge. It also identified skills shortages and technical debt as factors slowing the transformation of legacy systems into agile, scalable platforms. These constraints separate the availability of cloud services from an enterprise’s ability to put dependent applications into productive use. Additional infrastructure supply therefore cannot, by itself, remove the implementation work that delays the conversion of modernization demand into cloud consumption.
*Our forecasts treat driver/restraint impacts as directional, not additive. The impact forecasts reflect baseline growth, mix effects, and variable interactions.
India Cloud Computing Market Segment Analysis
By Deployment Model:
Public Cloud Scale Meets Hybrid Placement NeedsPublic cloud accounted for a 73.64% share of the India cloud computing market size in 2026. HDFC Bank’s Enterprise Payment Hub is deployed across Google Cloud Platform and Amazon Web Services for mission-critical payment processing. HDFC Bank co-developed the hub with FynDNA, combining its role as the banking operator with an application-development partner. This deployment places a specific core banking function on public-cloud infrastructure, linking demand to payment-processing continuity. Suppliers serving this application must support operation across providers, so reliability at the application boundary matters alongside the capabilities of each cloud platform.
Hybrid cloud is the fastest-growing segment, with a 27.8% CAGR over 2027-2032. In Q1 2026, 44% of surveyed developers in India reported using hybrid cloud, the most widely used cloud deployment approach among developers there. The survey linked India’s legislative environment to both the motivation for hybrid adoption and its practicality. An offer that works only when an application sits wholly in the cloud therefore misses the deployment approach these developers report using most often.

By Service Type:
Application Access Leads While Platforms Deepen Service UseSoftware as a service (SaaS) represented a 53.15% India cloud computing market share in 2026. By April 1, 2026, around 1.67 million Government of India ministry and department user accounts had migrated to the cloud-based email solution selected through NIC and operated by Zoho. Payments were based on the actual number of email accounts migrated to the Zoho platform. Under this arrangement, migrating additional ministry or department accounts would expand Zoho’s billable base, linking revenue opportunities to completed account transfers.
Platform as a service (PaaS) is the fastest-growing segment, with a 30.9% CAGR over 2027-2032. In August 2025, Bharti Airtel subsidiary Xtelify offered Airtel Cloud to telecom operators through a PaaS model and reported signed contracts with Singtel, Airtel Africa, and Globe Telecom. These counterparties are telecom operators in Singapore, Africa, and the Philippines, respectively. The Ministry of Steel hosted its web applications and services on NIC Cloud using PaaS through March 2025 and later moved some of them to TCL Cloud. For PaaS suppliers, the ministry’s move separates initial platform adoption from retention of the underlying workloads, because applications can later move to another cloud provider.
By Organization Size:
Smaller Buyers Lead As Enterprise Uses SpecializeSmall and medium-sized enterprises (SMEs) were the largest segment with a 62.53% share in 2026 and are also forecast to be the fastest-growing segment, at a 23.9% CAGR over 2027-2032. Vi Business’s 2026 study found that 84.6% of surveyed Indian MSMEs were using, implementing, or planning Microsoft 365 within its digital-workplace measure. This combination of deployment stages identifies different commercial tasks within the same application category. Suppliers serving firms implementing the software must establish useful workplace access, while planned use presents an earlier conversion task. The distinction makes activation of intended use consequential for suppliers, because a planned workplace application becomes service consumption only when implemented.
For SMEs entering through workplace software, expanding application access is a different task from supporting specialized enterprise engineering. In FY2025, Mahindra & Mahindra moved core engineering simulations to cloud-based high-performance computing. These included noise, vibration, and harshness work and computational fluid dynamics simulations. For suppliers serving this type of user, the proposition must match the computing service to the engineering task being performed. Simulation requirements can generate demand independently of employee counts, so enterprise computing offers must be sized around the technical workload.
By Industry Vertical:
Banking Procurement Meets Healthcare ModernizationBFSI was the largest segment, accounting for 18.32% of cloud-service spending in 2026. State Bank of India awarded 3 public-cloud services contracts on December 30, 2025. The purchase orders named Orient Technologies Private Limited, SISL Infotech Private Limited, and Unicloud Labs Private Limited as L1 vendors, with scheduled completion on December 29, 2030. These awards illustrate a banking procurement route in which intermediaries connect the financial institution with public-cloud services. For platform suppliers, these awards make coordination with the named procurement vendors part of serving the bank through the scheduled contract period.
The healthcare and life-sciences segment is the fastest-growing segment, with a 28.7% CAGR over 2027-2032. In its FY2024-25 annual report, Apollo Hospitals Enterprise Limited said it had completed a full cloud migration of its hospital operating platforms to Microsoft Azure. Apollo also upgraded its electronic medical record systems, adding AI-driven disease-risk scoring and automated clinical summaries through generative AI. These parallel actions illustrate a healthcare buyer modernizing both its hosting and application functions, creating a specific context for cloud-service demand. Hospital operating platforms can anchor cloud-service consumption as clinical application functions change, linking the healthcare opportunity to software operations within the provider’s care-delivery environment.
By Workload:
Core Resources Anchor AI Compute ExpansionCore compute and storage was the largest segment, with a 40.08% share in 2026. In FY2024-25, NIC provisioned and allocated more than 28,855 virtual servers to more than 1,917 users and applications for e-governance projects. Allocation to users and applications makes the relationship granular, with an infrastructure service that can be specified at the level of a particular computing requirement. For government-cloud operators, provisioning therefore has to accommodate many separately assigned users and applications, making allocation management central to supporting this infrastructure base.
AI, machine learning, and generative AI form the fastest-growing segment, with a 34.8% CAGR over 2027-2032. By August 2026, 237 projects had accessed subsidized IndiaAI computing for AI model development, training, testing, and research, covering 9.32 million GPU hours. The program lowers entry barriers for Indian researchers, start-ups, and innovators by making high-performance computing more affordable. The AI activity makes model preparation a distinct source of compute demand, giving providers a potential customer base before production applications are deployed.
Geography Analysis
West Cloud Computing Market
West accounted for a 37.9% share of the India cloud computing market size in 2026. In a February 2026 backgrounder, PIB reported that Mumbai and Navi Mumbai held over 25% of India’s live data-center capacity, with Pune separately accounting for 6% of national data-center capacity. The Mumbai and Navi Mumbai hub’s capacity is supported by a dense subsea cable network.
South Cloud Computing Market
South is expected to be the fastest-growing regional cloud computing market. Microsoft made its India South Central cloud region in Hyderabad generally available on August 6, 2026, for eligible Microsoft Cloud services and workloads. Before that general availability, Microsoft reported early-access demand from Adani Group, Bajaj Finserv, HDFC Bank, and PB Pay. The step from early access to general availability shifts the commercial task toward supporting eligible service use. Three of the four named organizations operate in financial services, banking, or payments, giving this early-access group a financial-sector emphasis.
Northern India’s government-cloud role includes NIC’s National Data Centre at its Delhi headquarters, which supports e-governance infrastructure. Near Chennai, AWS expanded its Direct Connect location at an STT data center to dedicated 100 Gbps connections in July 2025. The connection near Chennai enabled private access from customer environments to public AWS Regions other than those in China, as well as AWS GovCloud Regions and AWS Local Zones. These examples distinguish a government service-hosting node from a channel connecting customer environments to provider cloud infrastructure. The Chennai expansion therefore improves access to AWS Regions elsewhere, making its local contribution network connectivity rather than new cloud hosting capacity.
The cloud computing market is analyzed by Mordor Intelligence across multiple other geographies, with in-depth regional assessments available for South America, North America, and Europe. This is complemented by country-specific insights for Japan, China, Brazil, Canada, Spain, and France, reflecting various localized market behavior and policy environments' coverage.
Regulatory Framework and Outlook
The comparison covers selected jurisdictions through India’s national requirements and Telangana’s state-government cloud adoption framework. Attractiveness is assessed from the perspective of cloud-service suppliers serving regulated institutional and public-sector buyers. RBI requires covered payment-system providers to store payment-system data in India, while permitting foreign-leg data to also be stored abroad if required. This makes workload-specific data placement a commercial consideration when suppliers configure services for those buyers.
Regulatory Table of India Cloud Computing Market
| Decision factor | India | Telangana |
|---|---|---|
| Primary authority | Reserve Bank of India for payment-system data | ITE&C Department and exemption committee chaired by its Principal Secretary |
| Key instruments or direction | Payment-system data-storage direction; phased Digital Personal Data Protection Rules, 2025 | Cloud Adoption Policy, 2020, covering new applications and existing applications under its specified scenarios |
| Commercial effect | Domestic storage for covered payment-system data, with foreign-leg storage abroad permitted if required; privacy duties depend on entity role | Cloud deployment for eligible state applications; Top Secret and Secret applications retain existing hosting options; other exemptions require justification and committee approval |
| Current policy attractiveness | Medium | High |
| Future direction of policy attractiveness | Hardening | No change |
| Source: Mordor Intelligence | ||
India’s Medium rating reflects the configuration and governance work associated with covered payment-data arrangements and role-dependent privacy duties. Hardening reflects the May 13, 2027, commencement of restrictions on overseas transfers of personal data and related traffic data by Significant Data Fiduciaries, only for data specified by the Central Government on a committee’s recommendation. Telangana’s High rating reflects mandated cloud deployment for eligible state applications, with Top Secret and Secret applications permitted in existing or dedicated environments and other exemptions subject to justified requests and committee approval. Its No change assessment rests on the continuing departmental mandate and exemption structure, which preserves a defined route for cloud-service provision to eligible public-sector applications.
Value Chain Stages
The value chain compares facilities, cloud-service provision, and hosted applications as distinct sources of supplier earnings. Each stage turns a different operating capability into a service that the next participant can use. On February 5, 2025, CtrlS Datacenters unveiled its GreenVolt 1 captive solar farm in Nagpur, Maharashtra. That power-sourcing example illustrates how an upstream operator can develop supporting infrastructure alongside its hosting business, while downstream suppliers capture value through cloud access and software services.
Value Chain Analysis Table of India Cloud Computing Market
| Primary activity | Key participants | Value capture | Bottleneck | Resilience response |
|---|---|---|---|---|
| Data-center facilities | Data-center operators such as Nxtra and CtrlS Datacenters | Colocation and facility-service fees | Securing power for facility operations | Diversify power sourcing, including captive generation |
| Cloud-service provision | Cloud service suppliers such as AWS India | Cloud access and usage-based service fees | Coordinating cloud services with host infrastructure | Assign provider and infrastructure-host responsibilities before deployment |
| Cloud-hosted applications | CRM providers such as Salesforce and cloud ERP providers such as SAP SE | Application subscriptions, including annual or monthly cloud ERP fees | Dependence on provider-run application hosting | Define hosting and maintenance commitments around application criticality |
| Source: Mordor Intelligence | ||||
SAP customers lease cloud ERP software on annual or monthly subscriptions rather than owning it. Continued access therefore generates recurring application income within measured cloud-service spending. CtrlS also sells managed services alongside its data-center operations, and any separately priced migration, integration, or consulting work in those contracts sits outside the market totals. CtrlS’s colocation fees accrue outside the cloud-service spending measured here, whereas cloud-access fees and SAP’s application subscriptions fall inside, so facility investment and cloud-service revenue enter different commercial accounts.
Competitive Landscape
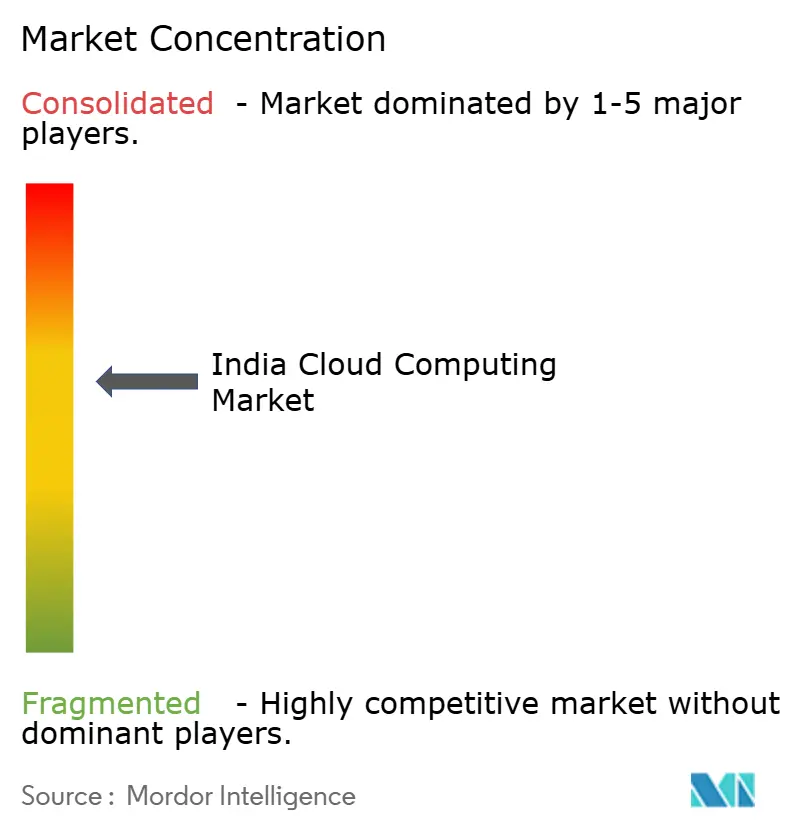
Major platforms Alibaba Cloud, Amazon Web Services, Google Cloud, Microsoft Azure, and IBM Cloud compete alongside local deployment partners. Alibaba Cloud provides Elastic Compute Service in Mumbai, while Google Cloud announced expanded Indian AI hardware capacity using AI Hypercomputer and Trillium TPUs for Gemini training and serving on November 11, 2025. On September 21, 2026, Microsoft said its India South Central region expanded its Sovereign Public Cloud foundation for eligible workloads, with governance capabilities designed to help customers address requirements applicable to their organizations. Buyers can therefore assess local compute access, specialized AI hardware, and governance capabilities as separate service requirements within the same supplier field.
Provider partnerships can connect international cloud capabilities with the operating locations of public-sector workloads. On February 17, 2026, AWS India announced it would work with Yotta Data Services to deploy AWS Outposts for NIC’s MeghRaj 2.0 initiative. The proposed hybrid architecture would let government departments run sensitive workloads in NIC data centers while accessing AWS services. That division of roles gives the deployment partner a defined place in the delivery model and offers AWS a route to serve workloads attached to government infrastructure. The competitive advantage would depend on making the provider’s services usable within that operating arrangement, placing local deployment coordination at the center of the supplier relationship.
On September 29, 2026, IBM and Yotta Data Services made the Sovereign Agentic AI Platform generally available to Indian organizations on Yotta’s Shakti Cloud. IBM supplied enterprise AI technology and watsonx Orchestrate, while Yotta supplied the sovereign cloud and platform capabilities. The platform was designed to keep data, operations, and governance controls within India. RBI’s April 10, 2023, direction requires covered regulated entities to comprehensively assess provider risk and contract only with providers subject to jurisdictions upholding enforceable agreements and data-storage, protection, and confidentiality rights. In-country governance gives regulated buyers a concrete operating arrangement to assess, while provider jurisdiction and enforceable contractual rights remain separate selection requirements.
India Cloud Computing Industry Leaders
-
Alibaba Cloud
-
Amazon Web Services
-
Google Cloud
-
Microsoft Azure
-
IBM Cloud
- *Disclaimer: Major Players sorted in no particular order
India Cloud Computing Market Companies Covered in this Report
- Amazon Web Services
- Microsoft Azure
- Google Cloud
- IBM Cloud
- Oracle Cloud
- Alibaba Cloud
- Salesforce
- SAP SE
- VMware
- Tata Consultancy Services
- Wipro
- Infosys
- HCLTech
- Bharti Airtel (Nxtra / Airtel Cloud)
- Reliance Jio Cloud
- Zoho Corporation
- CtrlS Datacenters
- NTT (Netmagic)
- Lumen Technologies India
- Rackspace Technology India
Key Opportunities for Market Participants
The opportunities compare distinct AI cloud-service applications for eligible startups, MSMEs, and academic users. IndiaAI offers cloud compute, network, storage, and platform services, with user groups subject to specific eligibility criteria and supporting-document requirements. Subsidies apply to approved projects, while users pay costs beyond the subsidy to service providers under their billing cycles. This creates a commercial opening for clearly scoped applications whose service requirements can be matched to the available support and remaining user-funded consumption.
Market Opportunities Table of India Cloud Computing Market
| Opportunity | Why now | Buyer / lead segment | Recommended play | Main barrier | Likely beneficiaries |
|---|---|---|---|---|---|
| Bounded AI model-development compute packages | Active IndiaAI access to cloud compute for approved subsidized projects | Eligible AI startups meeting program criteria | Package compute around a defined model-development and testing task | User-funded costs beyond the approved subsidy | Empaneled cloud AI providers such as E2E Networks and Yotta |
| Cloud document and language-processing applications | Translation, OCR, and audio-processing services available through IndiaAI | Eligible MSMEs meeting program criteria | Build a cloud-service offer around one defined document or language workflow | Service charges exceeding project subsidy coverage | Matching empaneled AI service providers, including Sify and NTT |
| Project-based academic AI compute and storage | Cloud compute, storage, and platform services accessible to eligible research users | Eligible researchers and academic faculty submitting required documents | Combine compute and storage around a defined research project | Residual computing and storage costs payable by the user | Empaneled providers such as CtrlS Datacenters and E2E Networks |
| Source: Mordor Intelligence | |||||
The central opening is a bounded cloud-service package with a defined application and explicit user-paid consumption. IndiaAI’s requirement that users pay excess costs to service providers makes residual consumption charges part of the offer design. That favors packages in which the scope of the task and the computing services consumed can be assessed together before additional usage creates further payment obligations.
Recent Industry Developments in India Cloud Computing Market
- Sep 2026: IBM and Yotta Data Services made the Sovereign Agentic AI Platform generally available to Indian organizations on Yotta’s Shakti Cloud, combining IBM’s enterprise AI technology with Yotta’s cloud and platform capabilities.
- Aug 2026: Microsoft made its India South Central cloud region in Hyderabad, Telangana, generally available, allowing customers to run eligible Microsoft Cloud services and workloads from the region.
- Jul 2026: Amazon Web Services held a foundation-stone ceremony for a data center at Bharat Future City in Ranga Reddy District, Telangana.
India Cloud Computing Market Report Scope and Research Methodology
Market Definition and Coverage
The India cloud computing market measures annual spending in India on on-demand computing services delivered over networks using shared or dedicated cloud resources. It counts spending by organizations for cloud services across deployment models and workload classes.
Scope exclusions: Separately sold datacenter buildings and equipment, on-premises infrastructure and software licenses, standalone migration, integration, consulting and IT outsourcing fees, and connectivity or colocation services sold without a cloud service are excluded.
Segments Covered in This Report
- By Deployment Model
- Public Cloud
- Private Cloud
- Hybrid Cloud
- By Service Type
- Infrastructure-as-a-Service (IaaS)
- Platform-as-a-Service (PaaS)
- Software-as-a-Service (SaaS)
- Function-as-a-Service (FaaS)
- By Organization Size
- Small and Medium-sized Enterprises (SMEs)
- Large Enterprises
- By Industry Vertical
- BFSI
- Manufacturing
- Retail and E-commerce
- Healthcare and Life-Sciences
- Telecom and IT
- Government and Public Sector
- Transportation and Logistics
- Others
- By Workload
- Core Compute and Storage
- Analytics and Big-Data
- AI / ML and Gen-AI
- Business Applications (ERP/CRM/HR)
- Disaster Recovery and Backup
- Collaboration and Productivity
Data Sources, Market Sizing, and Validation
Desk Research
Public sources such as the Ministry of Electronics and Information Technology's Annual Report 2024-25 and the Economic Survey 2024-25 describe NIC cloud services, MeghRaj applications and provider participation, which help frame government demand and service delivery in India. The Economic Survey 2025-26 updates the government cloud-provider landscape, while the Telecom Regulatory Authority of India's consultation on data centers distinguishes cloud services from physical facilities and connectivity.
Company annual reports, regulatory filings, investor materials and reputable Indian business press can cross-check cloud-region launches, service portfolios and customer demand against public-sector and infrastructure indicators. Where company disclosures bundle cloud with broader IT services, only identifiable cloud-service revenue can support supplier-side checks. The sources named here are not exhaustive, and further sources inform collection, validation and clarification.
Primary Interviews and Surveys
India-focused interviews and structured surveys cover cloud-service providers, data-center operators, managed-service partners and enterprise buyers, with respondents in technology, finance, procurement and workload leadership roles. Their evidence tests secondary-source classification of public, private and hybrid cloud spending, challenges segment-share and forecast drivers, and clarifies gaps where disclosures combine cloud charges with adjacent services. Conflicting responses are checked against filings, service descriptions and independent market indicators before an estimate or assumption is revised.
Distribution of primary research fieldwork respondents
| Company type | Respondent position | Region |
|---|---|---|
| Top tier: 30% | CXOs: 20% | |
| Mid tier: 45% | Functional/Unit leaders: 35% | |
| Smaller Players: 25% | Managers: 45% |
Market-Sizing & Forecasting
The model estimates annual end-user spending on cloud services in India from the top down, then checks selected service and deployment splits against supplier disclosures and sampled channel evidence. Relevant indicators include public-cloud spending forecasts, cloud-provider India revenue disclosures, NIC and MeghRaj application and service deployment, operational data-center capacity as a supply constraint, and enterprise adoption of AI, analytics and modernized business workloads. Analysts use these signals to build shares for public, private and hybrid deployment, and for IaaS, PaaS, SaaS and FaaS, organization size, industry vertical and workload, with transaction evidence assigned to the service purchased and bundled value counted once. Scenario analysis carries the forecast forward by varying cloud adoption, service mix, provider capacity, workload demand and pricing or usage assumptions, while India-based experts assess whether each variable's direction and timing fit buyer and provider conditions. Selective bottom-up checks multiply sampled service price by observed or reported usage and roll up identifiable supplier revenue, then reconcile those checks to the broader spending estimate. Bundled disclosures or missing prices and volumes are handled with documented ranges and are not treated as separate cloud sales. Where annual reports combine cloud with other IT services, analysts use only revenue that can be tied to cloud-service provision.
Data Validation & Update Cycle
Analysts triangulate official indicators, provider disclosures, published spending estimates and primary evidence, then check segment totals, growth paths and supplier roll-ups for unexplained variance or boundary mismatches. A second analyst reviews source traceability and arithmetic, and a senior reviewer examines resolved anomalies before sign-off. Respondents are re-contacted when a material discrepancy or ambiguous classification could change an input. The model is refreshed annually, revisited between cycles after material policy, capacity or provider events, and checked again in a fresh pre-delivery review.
Mordor Intelligence's India Cloud Computing Market Size Measured Against Other Published Estimates
Published estimates can differ in the transactions and products they count and the inputs used to model demand. The India cloud computing market measures annual spending in India on on-demand computing services delivered over networks using shared or dedicated cloud resources.
Key Gap Drivers include the study's defined coverage and market-specific modeling choices. Relevant indicators include public-cloud spending forecasts, cloud-provider India revenue disclosures, NIC and MeghRaj application and service deployment, operational data-center capacity as a supply constraint, and enterprise adoption of AI, analytics and modernized business workloads.
Benchmark comparison
| Source | Market Size | Gaps in Research Methodology |
|---|---|---|
| Mordor Intelligence | USD 32.01 B (2027) | |
| Global Consultancy A | USD 17.5 B (2026) | At its 2026 base, this estimate is 45.3% below this report's 2027 value of USD 32.01 B, 1 year later. It covers end-user public-cloud spending, excluding the private and hybrid service transactions included in this report. |
| Global Research Firm B | USD 10.9 B (2024) | At its 2024 base, this estimate is 65.9% below this report's 2027 value of USD 32.01 B, 3 years later. It counts IaaS, PaaS and SaaS public-cloud services, and its earlier base predates the subsequent spending growth projected on the source page. |
Mordor Intelligence's analysts triangulate official indicators, provider disclosures, published spending estimates and primary evidence, then check segment totals, growth paths and supplier roll-ups for unexplained variance or boundary mismatches.
Key Questions Answered in the Report
What is the India cloud computing market size and growth outlook?
The size is expected to reach USD 32.01 billion in 2027 and USD 85.46 billion by 2032, with a 21.7% CAGR over 2027-2032.
What is driving demand for cloud computing in India?
MeghRaj adoption reached 2,323 government departments by June 2026. Enterprise ERP modernization also supports demand.
Which deployment model leads cloud-service spending in India?
Public cloud led deployment models with 73.64% of cloud-service spending in 2026.
Which providers are prominent in India’s cloud industry?
Prominent providers include Alibaba Cloud, Amazon Web Services, Google Cloud, Microsoft Azure, and IBM Cloud.
What could slow cloud adoption in India?
Complexity and legacy dependencies were critical migration hurdles for 89.3% of Indian enterprise technology leaders surveyed by CIO&Leader in 2025. This can delay the transition from transformation plans to cloud-service consumption.
Which Indian regions lead cloud-service demand and growth?
West held 37.9% of cloud-service spending in 2026. South is expected to grow fastest.