United Kingdom Hospitality Market Analysis by Mordor Intelligence
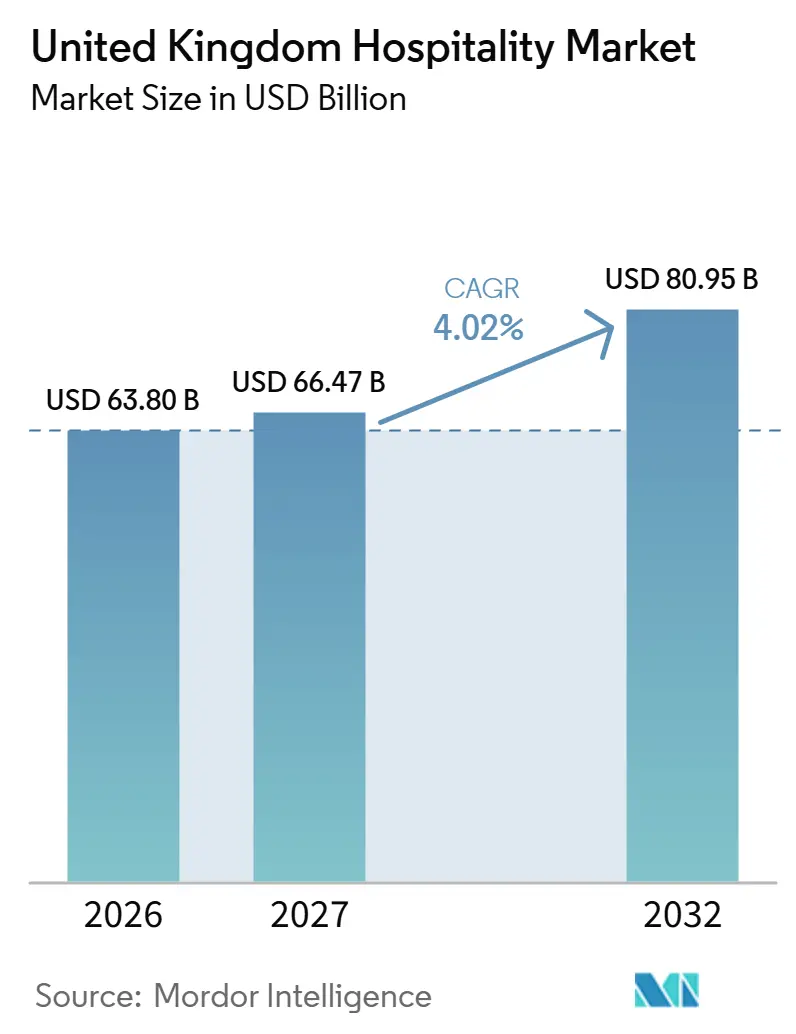
The United Kingdom hospitality market size was valued at USD 63.8 billion in 2026 and estimated to grow from USD 66.47 billion in 2027 to reach USD 80.95 billion by 2032, at a CAGR of 4.02% during the forecast period (2027-2032).
Digital discovery and inbound travel create accommodation opportunities, while rates relief supports eligible pubs in England. Labor costs and energy-price uncertainty constrain how much service operators can deliver at affordable prices. Brand operators can expand through rebranding existing hotels, providing an alternative to new construction. Control over the reservation journey can help operators convert a traveler's interest into an accommodation sale. For hotel groups, expansion through existing rooms is commercially attractive only if additional reservations can cover the labor and energy needed to serve additional guests.
Key Report Takeaways
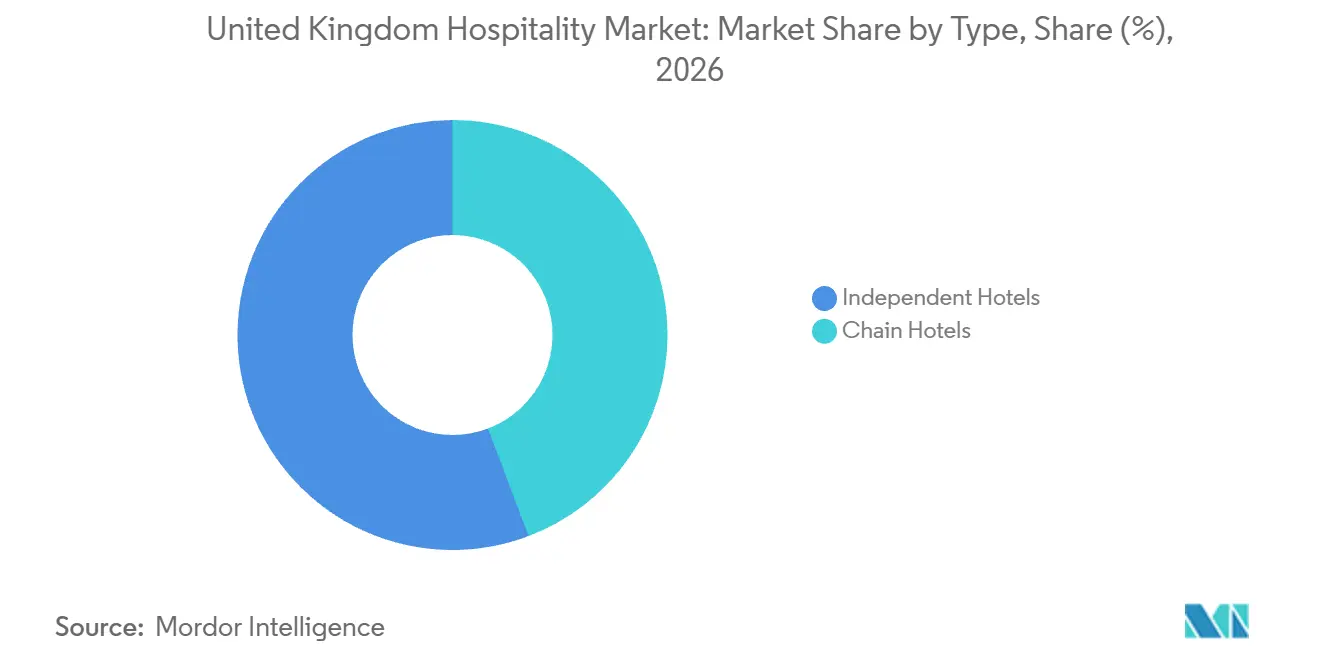
- By type, independent hotels led with a 55.76% United Kingdom hospitality market share in 2026, while chain hotels are forecast to grow fastest at a CAGR of 7.65% during 2027-2032.
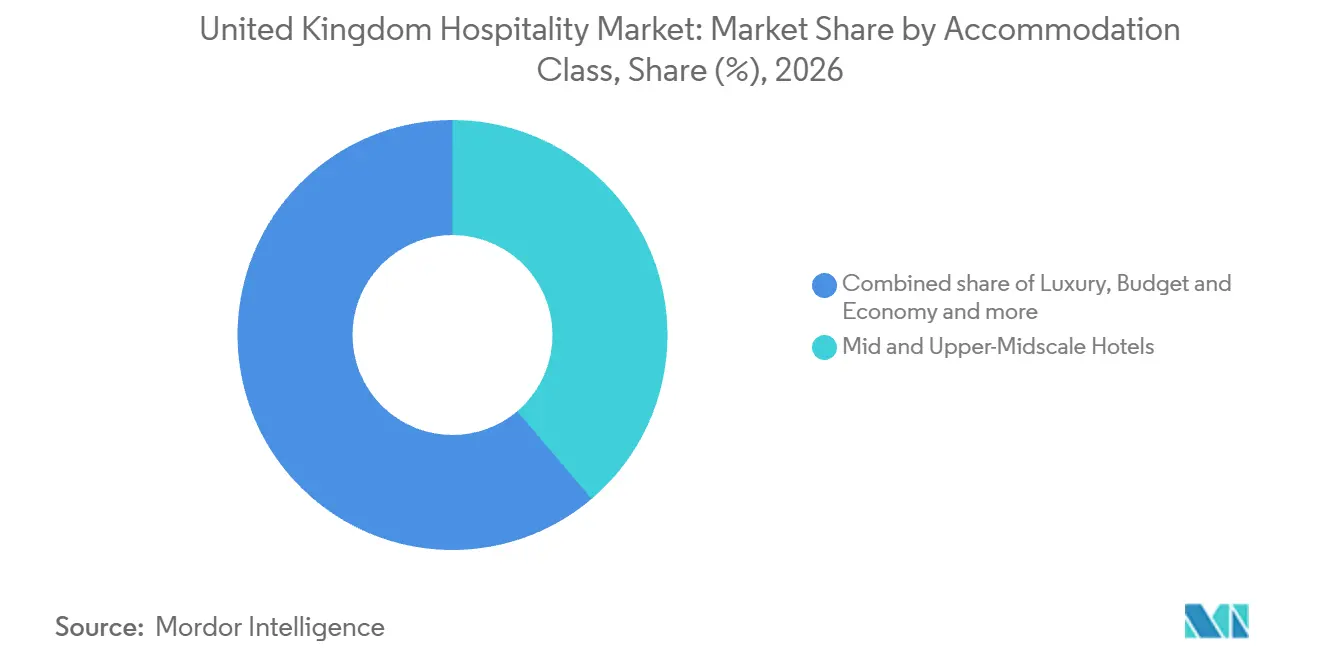
- Within accommodation classes, mid and upper-midscale hotels held a 38.8% share of the United Kingdom hospitality market size in 2026, with luxury forecast to grow fastest at a CAGR of 7.8% during 2027-2032.
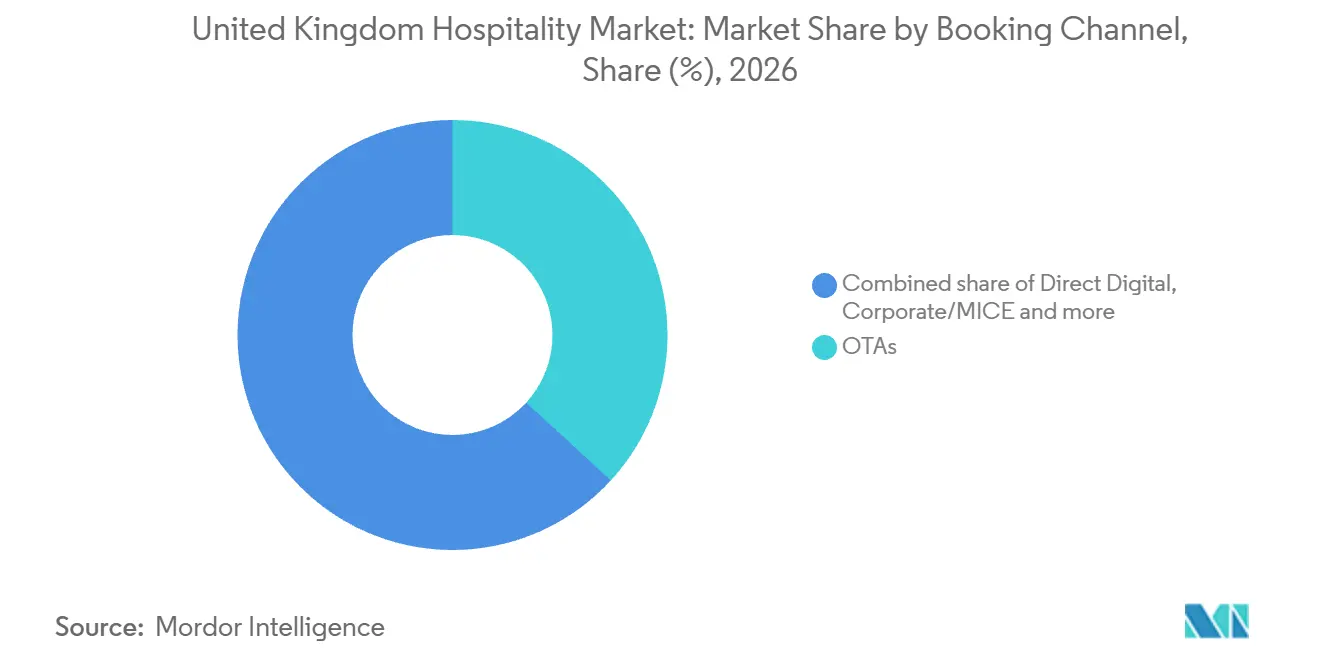
- Across booking channels, online travel agencies led with 36.82% of market value in 2026, whereas direct digital is forecast to grow fastest at a CAGR of 7.15% during 2027-2032.
- Geographically, England accounted for the largest share of market value at 71.15% in 2026, and Northern Ireland is forecast to grow fastest at a CAGR of 8.05% during 2027-2032.
Note: Market numbers in this report are based on Mordor Intelligence's proprietary estimation framework, which combines nine months of actuals with Q4 projections for base year 2026.
United Kingdom Hospitality Market Trends and Insights
Drivers Impact Analysis*
| Driver | (~) % Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
|---|---|---|---|
| Accelerating Digital Ordering & Booking | +2.1% | Nationwide | Medium term (2-4 years) |
| Government Business Rates Support & Incentive Schemes | +1.5% | England, Scotland and Wales | Short term (≤ 2 years) |
| Rising Inbound Tourism On Weak Currency | +1.4% | Nationwide | Medium term (2-4 years) |
| Hybrid-Work-Fueled Mid-Week Leisure Stays | +1% | Nationwide | Medium term (2-4 years) |
| Outsourcing Surge in Institutional Catering | +0.5% | County of Hampshire | Medium term (2-4 years) |
| Source: Mordor Intelligence | |||
Accelerating Digital Ordering & Booking
Digital discovery gives hotel operators an additional route to convert travelers who begin their search outside an established booking application. Whitbread PLC reported a 70% increase in bookings made via AI search engines during May-August 2026 across its UK and Ireland hotel operations.[1] It strengthened discoverability through AI-powered search as part of its commercial program. The implication for operators is that a usable booking journey needs an effective discovery route before conversion tools can generate a sale. Whitbread's early-stage trials with key large language models to extend its reach show how digital distribution can also require direct technology collaboration.
Government Business Rates Support & Incentive Schemes
Business-rates relief can protect hospitality capacity by reducing a recurring property expense before operators need additional sales to cover it. For 2026/27, eligible pubs and live music venues in England receive a 15% reduction on their business-rates bills through local-authority schemes. Local billing authorities exercise discretion over individual cases, while the UK government reimburses relief granted under its guidance. In July 2026, the government announced 20% business-rates relief from April 2027 for England's pubs, social clubs and live music venues, excluding the very largest live music venues, with Budget details pending. For a qualifying venue, lower fixed outgoings can preserve the financial room to continue hosting customers without an equivalent increase in prices. Local decisions and property eligibility can produce different support across a multi-venue estate, so relief reaches each site unevenly even within a shared operating model.
Rising Inbound Tourism On Weak Currency
Overseas residents made an estimated 40.8 million completed visits to the United Kingdom in 2025, subject to revision.[2] That visitor base creates an accommodation opportunity for operators able to turn international travel into paid overnight stays. The broad effective sterling exchange-rate index measured 84.62 on June 30, 2026, against its January 2005 base of 100. At a fixed sterling room rate, weaker sterling can lower the foreign-currency price of a stay. For hotels targeting overseas guests, this creates scope to improve affordability without reducing the sterling revenue received for each room booked.
Hybrid-Work-Fueled Mid-Week Leisure Stays
Where remote-work arrangements permit travel, a guest can combine working days with a leisure stay instead of limiting the trip to a weekend. For a hotel, that flexibility creates an opportunity to sell additional midweek nights to the same traveling party. The offer needs to support both uses, since a room suitable only for sleeping cannot by itself resolve the guest's need to work effectively. A midweek extension is commercially useful when its added accommodation revenue covers the service required during those days. Extending a leisure trip already chosen lets a hotel earn midweek accommodation revenue without winning an entirely separate trip.
Restraints Impact Analysis*
| Restraint | (~) % Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
|---|---|---|---|
| Acute Labor Shortages & Wage Inflation | -1.1% | Nationwide | Short term (≤ 2 years) |
| Food & Energy Cost Volatility | -0.8% | Nationwide | Short term (≤ 2 years) |
| Stringent Planning / Licensing Rules | -0.35% | The Avenues, Exmouth | Medium term (2-4 years) |
| High Reservation No-Show Rates | -0.25% | Nationwide | Short term (≤ 2 years) |
| Source: Mordor Intelligence | |||
Acute Labor Shortages & Wage Inflation
Labor costs constrain the service capacity operators can support even when recruitment conditions become less strained. UK hospitality had the highest sectoral vacancy rate in 2025 at 3.1%, down from 3.8% in 2024 and its lowest since 2013 outside the pandemic. Hospitality and retail employers reported employment reductions in response to minimum-wage increases in 2025, alongside other sector pressures. Most reductions took the form of lower recruitment and fewer hours rather than redundancies. For an operator, restricting staffed hours can limit the number of customers served without changing the physical capacity of a venue. Falling vacancies leave the wage-cost limit on staffed hours unresolved, restricting how much additional service an operator can afford.
Food & Energy Cost Volatility
Energy-price uncertainty raises the commercial hurdle for adding hospitality capacity because future sales must cover an operating expense whose level may change. In late September 2026, 91% of UK accommodation and food service businesses reported some degree of concern about energy prices.[3] For these operators, a room or meal price agreed before energy costs are known can leave less revenue available for other operating expenses. Passing that exposure into selling prices can also weaken the affordability that supports customer demand. A marginal location must cover energy-price risk alongside demand risk before additional hospitality capacity becomes commercially viable.
*Our forecasts treat driver/restraint impacts as directional, not additive. The impact forecasts reflect baseline growth, mix effects, and variable interactions.
Segment Analysis
By Type: Independent Scale Meets Chain Rebranding
Independent hotels accounted for a 55.76% share of the United Kingdom hospitality market size in 2026. They form the largest segment by type, with a commercial base that can include relatively small individual properties. A study based on May 2025 research identified 11 independent hotels averaging 28 rooms each in the Greater Cambridge Wider Area, beyond 3 miles from Cambridge center to the South Cambridgeshire boundary. At that property scale, a hotel can compete for a destination's customers without duplicating an extensive multi-property operating model. Selling into this segment may require many relationships with small properties, so the cost of winning each owner account weighs on a supplier's commercial reach.
Chain hotels are forecast to grow at a CAGR of 7.65% during 2027-2032, making them the fastest-growing segment by type. Travelodge opened 21 hotels and added more than 1,800 rooms to its UK estate in 2025 through 4 new builds and 17 rebrand acquisitions from other brands. The predominance of rebrands illustrates how a chain can increase its own branded room supply through existing properties as well as construction.

By Accommodation Class: Established Midscale Supply Meets Luxury Expansion
Mid and upper-midscale hotels represented a 38.8% United Kingdom hospitality market share in 2026. This makes them the largest accommodation-class segment. In May 2025, upper-midscale hotels alone accounted for 39% of hotel room stock in the Greater Cambridge Wider Area, its largest individual hotel class. That local stock establishes a sizable competitive set that a new upper-midscale entrant around Cambridge would need to address.
Luxury is the fastest-growing accommodation-class segment, with a forecast CAGR of 7.8% during 2027-2032. It was the only UK hotel class with growth in revenue per available room in the year-to-date period through July 2025, at 2.8%. IHG's Six Senses London, within its Luxury & Lifestyle portfolio, opened on March 1, 2026, with 109 bedrooms and suites. Serviced apartments have a corporate demand route, with the GBTA Business Travel Index Outlook forecasting an 8.1% increase in corporate travel spending in UK serviced apartments in 2026. For investors, luxury expansion involves selling differentiated new capacity, whereas serviced-apartment opportunities can be tied to the accommodation requirements of a defined corporate buyer group.
By Booking Channel: Agency Reach Supports Direct Conversion
Online travel agencies (OTAs) were the largest booking-channel segment, accounting for 36.82% of market value in 2026. SiteMinder's 2025 UK hotel booking-revenue ranking placed Booking.com and Expedia in the first 2 positions. Their position gives hotel operators a commercial reason to preserve agency access when competing for accommodation sales. For an individual property, visibility through these channels can provide access to buyers who select an intermediary before choosing a hotel. Agency reach exposes a hotel to accommodation buyers, but winning their reservation requires an offer that stands out within the shared booking environment.
Direct digital is the fastest-growing booking-channel segment, with a forecast CAGR of 7.15% during 2027-2032. Travelodge Group reported that approximately 80% of its bookings were through its own websites in 2025 across its operations, including the UK, Spain and Ireland. At that level of own-site use, the reservation experience becomes part of the operator's core guest transaction rather than a supplementary sales route. The operator can align the room offer and confirmation within a booking journey it controls, connecting digital execution directly to the accommodation sale. For hotels capable of attracting their own audience, improvements to that journey can affect a substantial booking base without requiring additional physical rooms.
Geography Analysis
England Hospitality Market
England accounted for a 71.15% share of the United Kingdom hospitality market size in 2026, making it the largest geography. Residents of Britain took 87 million overnight trips in England in 2025, down 3% from 2024. That established domestic travel base gives accommodation operators a substantial pool of overnight demand to serve, even when the annual number of trips softens. The commercial task is to retain the value of an extensive existing visitor base through accommodation sales, because a large domestic footprint can support leadership without requiring a rising trip count every year.
Northern Ireland Hospitality Market
Northern Ireland is the fastest-growing geography, with a forecast CAGR of 8.05% during 2027-2032. Estimated overnight holiday trips increased from 2.4 million in 2024 to 2.7 million in 2025, a reported 13% rise that expands the leisure travel opportunity. However, hotel-room occupancy fell from 68% in 2024 to 65% in 2025, so the broader travel expansion did not coincide with higher annual hotel utilization. Because hotel-room occupancy fell while holiday trips rose, the growth opportunity for accommodation operators lies in converting that larger trip pool into paid room nights.
Scotland's 2025 domestic overnight tourism estimates, classified as statistics in development, placed serviced accommodation first by trips, nights and spending among Great Britain residents. This use pattern gives suppliers a clear route into the established Scottish visitor economy through serviced accommodation businesses. Wales's provisional estimates showed increasing use of serviced accommodation on domestic overnight trips by Great Britain residents in 2025. Domestic holiday trips to Wales also rose that year, while trips to visit friends and relatives fell. Together, these Welsh shifts strengthen the commercial case for holiday-focused serviced lodging, because accommodation choice and trip purpose both point toward opportunities to sell the stay itself.
Regulatory Framework and Outlook
The comparison covers the United Kingdom's licensing baseline and selected jurisdictions, England and Northern Ireland, from the perspective of a pub operator adding licensed premises. Alcohol licenses are granted by local licensing committees in England and Wales, Licensing Boards in Scotland, and courts in Northern Ireland. A cross-country estate therefore needs jurisdiction-specific approval planning, with the national comparison reflecting these different administrative routes.
Regulatory Table
| Decision factor | United Kingdom | England | Northern Ireland |
|---|---|---|---|
| Primary authority | Local licensing committees, Licensing Boards and courts | Local licensing authority | Courts granting and renewing alcohol licenses |
| Key instruments or direction | Nation-specific alcohol-licensing frameworks | Licensing Act 2003 and September 2026 digital-ID guidance | Licensing (Northern Ireland) Order 1996 and approved liquor code |
| Commercial effect | Jurisdiction-specific license applications | Premises license for alcohol sales; certified verification if accepting digital ID | Existing license surrendered for a new public house; court code checks on applications and renewals |
| Current policy attractiveness | Medium | Medium | Low |
| Future direction of policy attractiveness | No change | Easing | No change |
| Source: Mordor Intelligence | |||
The UK baseline has medium attractiveness with continuity because the November 2025 England-and-Wales framework preserved local discretion, while Northern Ireland's separate review operates within its existing legislative structure. England's medium rating reflects local approval requirements, while the optional digital-ID route introduced in September 2026 supports an easing outlook when license holders use a certified, registered verification service. Northern Ireland rates low for entry because new public house applicants must surrender an existing license, while courts assess code awareness on application and compliance on renewal from January 2026. Its review of the 2022 amendments takes responses through November 9, 2026, and does not itself amend the law, supporting continuity under the present requirements.
Value Chain Stages
The comparison follows hotel brand affiliation, reservation distribution and accommodation delivery to show where suppliers capture revenue. Premier Inn UK accommodation sales increased 1% in FY26, the 52 weeks to February 26, 2026, compared with FY25. For operators using fee-based brands or booking intermediaries, such modest growth limits the additional accommodation revenue available to share across service stages.
Value Chain Analysis Table
| Primary activity | Key participants | Value capture | Bottleneck | Resilience response |
|---|---|---|---|---|
| Brand affiliation | Hotel brand licensors such as InterContinental Hotels Group (IHG) | Brand-licensing fees; management fees where applicable under IHG's group-wide model | Owner commitment to the scope and cost of brand support | Match franchise or management support to the property's operating requirements |
| Reservation distribution | Accommodation booking platforms such as Booking.com | Commission on each booking, invoiced monthly | Commission reduces room-sale proceeds retained by the operator | Use agency reach where its additional sales justify the transaction charge |
| Accommodation delivery | Hotel operators such as Whitbread PLC | Accommodation sales | Unsold room nights limit accommodation revenue | Target unsold nights with channel-specific accommodation offers |
| Source: Mordor Intelligence | ||||
IHG's room-revenue-linked franchise fees connect the brand's earnings to room sales, so support that improves conversion can also strengthen its fee base. Distribution adds a separate transaction charge, making the operator's retained revenue sensitive to the channel that generated the stay. For an owner using both services, wider distribution must generate enough additional room revenue to cover the associated fees.
Competitive Landscape
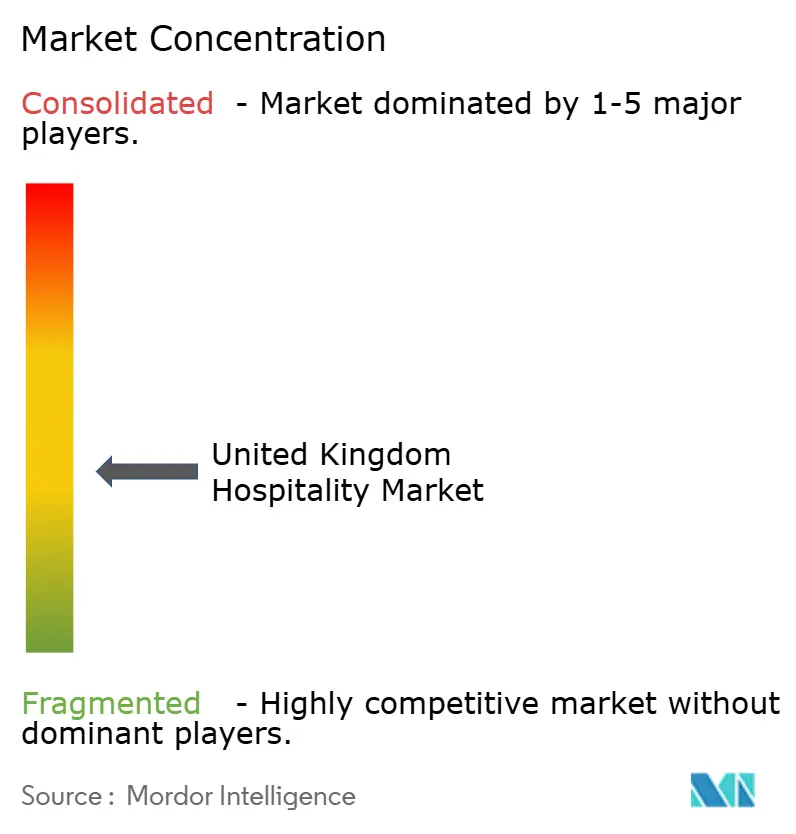
Competition is dispersed across accommodation, contract foodservice and pubs, with large groups operating different service models. Whitbread PLC operates Premier Inn, while InterContinental Hotels Group (IHG) expands hotel brands through franchise and property partnerships. Compass Group PLC participates through contract foodservice, while Greene King operates pubs and Mitchells & Butlers runs managed restaurants and pubs. Whitbread opened approximately 600 UK rooms and closed approximately 600 lower-returning rooms in 2025/26. Whitbread's room replacement emphasizes returns within its operating network, whereas IHG's partnerships extend its brands through additional properties.
In February 2026, IHG announced 4 UK property signings and openings with Fairview Hotels, adding more than 380 rooms to its UK and Ireland pipeline. Brand partnerships can extend distribution and operating identity across properties, although a signed pipeline contributes accommodation capacity only when the relevant rooms enter service. Separately, Compass's UK and Ireland business won a 7-year Heathrow contract in February 2026 to provide food and beverage services for more than 80,000 colleagues, including construction teams during the third runway expansion project. The contrast matters for challengers because hotel partnerships assemble a property network, while a large workplace contract requires the ability to sustain service for a defined institutional buyer over several years.
Mitchells & Butlers completed 181 conversions and remodels across its business during the 42 weeks ended July 18, 2026. It also acquired 8 UK freehold sites during that period. Greene King CEO Nick Mackenzie welcomed the government's July 2026 business-rates announcement as relief for pubs, saying they had long faced disproportionately higher rates. With those estate changes completed before the planned April 2027 start, the proposed relief would reduce subsequent property costs for qualifying pubs after this investment round.
United Kingdom Hospitality Industry Leaders
-
Whitbread PLC
-
InterContinental Hotels Group (IHG)
-
Compass Group PLC
-
Greene King
-
Mitchells & Butlers
- *Disclaimer: Major Players sorted in no particular order
Key Opportunities for Market Participants
The comparison weighs Scottish premium accommodation gaps against opportunities to improve hotels in established English destinations. Savills' 2026 assessment counted 79 luxury hotels outside Edinburgh in Scotland and identified an opportunity for well-positioned upper-upscale and luxury properties serving high-value demand. Cambridge, Oxford, York, Bath, Durham, Harrogate, Chester, Cheltenham and Stratford-upon-Avon recorded hotel occupancy of 75% to 83% in the 12 months to June 2026.
Market Opportunities Table
| Opportunity | Why now | Buyer / lead segment | Recommended play | Main barrier | Likely beneficiaries |
|---|---|---|---|---|---|
| Selected luxury capacity outside Edinburgh | 2026 assessment identifies limited luxury supply relative to high-value demand | High-value visitors / luxury hotels | Develop a luxury property where destination demand supports the full service offer | Location-specific development and operating economics | Luxury hotel owners and operators |
| Upper-upscale repositioning in Scotland | The same supply-demand gap supports well-positioned upper-upscale properties | Premium accommodation guests / upper-upscale hotels | Reposition an existing hotel around a clearly priced upper-upscale offer | Refurbishment cost relative to achievable room revenue | Existing upper-upscale owners and operators |
| Existing-hotel improvement in the 9 named English destinations | Dated occupancy establishes substantial room use across these locations | Overnight visitors / regional hotels | Acquire or improve an existing property with a defined local room-demand base | Acquisition and upgrade costs relative to sustainable earnings | Regional hotel owners and operators |
| Source: Mordor Intelligence | |||||
The central opening is well-positioned luxury and upper-upscale accommodation outside Edinburgh, addressing the Scottish gap between limited premium supply and high-value demand. In Scotland, the distinction between a full luxury development and upper-upscale repositioning changes the service commitment an owner must finance. For the named English destinations, an existing asset links the acquisition case to demonstrated room use, so the price paid and the revenue retained after refurbishment decide the return.
Recent Industry Developments
- Sep 2026: Hilton signed London Bridge Hotel to its Tapestry Collection under a franchise agreement with Gama Holdings. The 153-room London hotel was expected to open in early 2028 after a transformation.
- Jul 2026: The UK government announced 20% business-rates relief from April 2027 for England's pubs, social clubs and live music venues, excluding the very largest live music venues, with details due at the Budget.
- Jul 2026: Mitchells & Butlers reported 181 conversions and remodels across its business and 8 UK freehold site acquisitions during the 42 weeks ended July 18, 2026.
Research Methodology Framework and Report Scope
Market Definition and Coverage
The United Kingdom Hospitality Market measures annual revenue from lodging and food and beverage and related hospitality services in the United Kingdom. Sales are classified by lodging provider type, accommodation class, booking channel, and country.
Scope exclusions: Transportation services and theme parks and attractions are excluded.
Segmentation Overview
- By Type
- Chain Hotels
- Independent Hotels
- By Accommodation Class
- Luxury
- Mid & Upper-Midscale Hotels
- Budget & Economy
- Serviced Apartments
- By Booking Channel
- Direct Digital
- OTAs
- Corporate/MICE
- Wholesale & Traditional Agents
- By Geography
- England
- Scotland
- Wales
- Northern Ireland
Data Sources, Market Sizing, and Validation
Desk Research
Public sources such as the Office for National Statistics Travel Trends release provide inbound visits and visitor spending that help assess lodging demand, while its Business insights and impact on the UK economy bulletin, drawn from the Business Insights and Conditions Survey, tracks cost and operating pressures among accommodation and food service businesses. UKHospitality's quarterly sales tracker supplies sector turnover context, and its sector profile describes the range of accommodation, food service, pub, catering, and related hospitality businesses represented in the UK sector. These sources help distinguish revenue and demand indicators from broader economic contributions or operational counts.
Company filings, annual reports, investor presentations, and reputable UK business and trade press can add operator revenue, room supply, pipeline, trading, and channel evidence for cross-checking the market model. The named sources are illustrative rather than exhaustive, and further sources inform collection, validation, and clarification.
Primary Interviews and Surveys
Primary interviews and surveys cover UK hotel, serviced-apartment, restaurant, pub, catering, and hospitality distribution executives, including senior leaders, operating and commercial managers, and market analysts. Their input tests secondary estimates of revenue boundaries, channel treatment, operating conditions, and segment development, while targeted follow-up clarifies material gaps or conflicting evidence. Responses are compared with public statistics, filings, and other independent indicators before they inform model assumptions.
Distribution of primary research fieldwork respondents
| Company type | Respondent position | Region |
|---|---|---|
| Top tier: 35% | CXOs: 20% | |
| Mid tier: 40% | Functional/Unit leaders: 35% | |
| Smaller Players: 25% | Managers: 45% |
Market-Sizing & Forecasting
The model starts with a top-down estimate of UK lodging, food and beverage, and related hospitality provider revenue, then checks selected components through operator revenue roll-ups and sampled accommodation price times occupied room volume where reliable evidence is available. Core indicators include ONS visitor visits and spending for demand context, UKHospitality turnover trends for sector movement, operator-reported accommodation and food service revenue, room supply and occupancy for lodging capacity, and booking-channel mix for allocating lodging sales. Segment shares are built by reconciling those indicators with reported provider and product classifications, then allocating revenue across chain and independent providers, accommodation classes, booking channels, and the four UK countries. A multivariate regression can relate historical revenue movement to visitor demand, prices, occupancy and supply indicators, with scenario analysis used where policy, cost or travel conditions create materially different paths. Primary respondents can check whether the variable relationships and resulting segment forecasts fit UK operating conditions. Missing component data are estimated from the closest supported category, checked against total revenue and independent indicators, and recorded for targeted clarification, while selective bottom-up checks remain corroborative rather than the total-market model.
Data Validation & Update Cycle
Analysts triangulate provider revenue, official tourism and business indicators, association turnover evidence, and sampled operator checks, then investigate outliers, inconsistent definitions, and large variances across independent signals. A second analyst reviews source attribution, calculations, segment totals, and explanations, and unresolved material anomalies trigger source rechecks or respondent follow-up before sign-off. The model is refreshed annually, reviewed between cycles when material events alter demand, costs, or operating rules, and receives a fresh source and calculation pass immediately before delivery.
Mordor Intelligence's the United Kingdom Hospitality Market Size Versus Other Published Estimates
Published estimates can differ in the transactions and products they count and the inputs used to model demand. The United Kingdom Hospitality Market measures annual revenue from lodging and food and beverage and related hospitality services in the United Kingdom.
Key Gap Drivers include the study's defined coverage and market-specific modeling choices. Core indicators include ONS visitor visits and spending for demand context, UKHospitality turnover trends for sector movement, operator-reported accommodation and food service revenue, room supply and occupancy for lodging capacity, and booking-channel mix for allocating lodging sales.
Benchmark comparison
| Source | Market Size | Gaps in Research Methodology |
|---|---|---|
| Mordor Intelligence | USD 66.47 B (2027) | |
| Global Consultancy A | USD 69.5 B (2024) | At its 2024 base, this estimate is 4.6% above this report's 2027 value of USD 66.47 B, 3 years later. Its stated market includes restaurants, pubs, event and conference centers, short-term rentals, and entertainment, categories beyond the approved provider-revenue pool. |
| Global Consultancy B | USD 60.13 B (2025) | At its 2025 base, this estimate is 9.5% below this report's 2027 value of USD 66.47 B, 2 years later. Its reported classifications cover chain and independent hotels and accommodation classes, while the approved pool also counts food and beverage and related hospitality services. |
Mordor Intelligence's analysts triangulate provider revenue, official tourism and business indicators, association turnover evidence, and sampled operator checks, then investigate outliers, inconsistent definitions, and large variances across independent signals.
Key Questions Answered in the Report
What is the United Kingdom hospitality market size and growth outlook?
It was valued at USD 63.8 billion in 2026 and is estimated at USD 66.47 billion in 2027, reaching USD 80.95 billion by 2032 at a 4.02% CAGR during 2027-2032.
What is driving digital demand for UK hospitality services?
Digital discovery creates another booking route. Whitbread reported a 70% increase in bookings through AI search engines during May-August 2026 across its UK and Ireland hotel operations.
Which hotel type leads UK hospitality sales?
Independent hotels held the largest share at 55.76% in 2026. Chain hotels are forecast to grow fastest at a CAGR of 7.65% during 2027-2032.
Which companies are major UK hospitality competitors?
Major players include Whitbread PLC, InterContinental Hotels Group (IHG), Compass Group PLC, Greene King and Mitchells & Butlers.
What operating challenge affects UK hospitality expansion?
Energy-price uncertainty can constrain expansion economics. In late September 2026, 91% of UK accommodation and food service businesses reported some degree of concern about energy prices.
Which UK hospitality geography leads and which is growing fastest?
England held the largest share at 71.15% in 2026. Northern Ireland is forecast to grow fastest at a CAGR of 8.05% during 2027-2032.