
Mirrorless Camera Market Size and Share
Mirrorless Camera Market Analysis by Mordor Intelligence
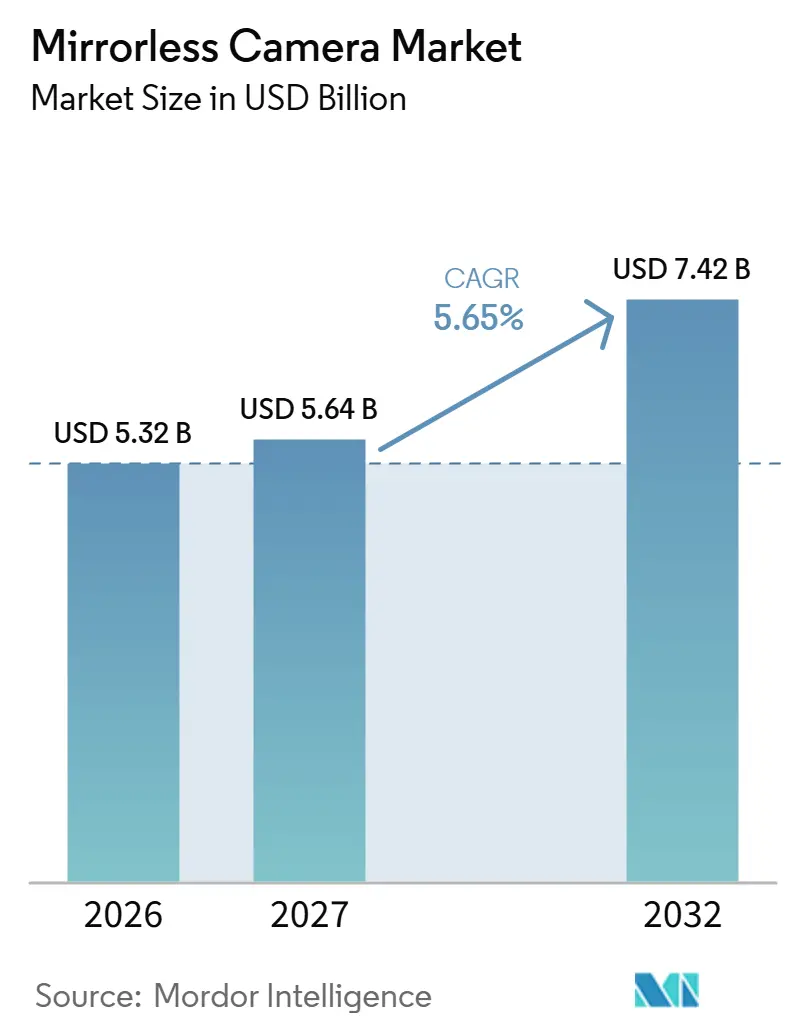
The mirrorless camera market size is projected to expand from USD 5.32 billion in 2026 and USD 5.64 billion in 2027 to USD 7.42 billion by 2032, registering a CAGR of 5.65% between 2027 and 2032.
Video-oriented use expands the camera's buyer proposition, while repeated paid assignments can justify investment in dedicated bodies. Shared institutional production in Canada adds a multiuser application, giving suppliers scope to connect the body with capture hardware and software support. Software integration can deepen that offer, but procurement-cost pressure limits the room to expand demand through lower body prices. Demand therefore concentrates in video-capable and full-frame bodies that earn repeat paid use, while smartphone substitution and component-cost pricing limit how many first-time buyers suppliers can recruit.
Key Report Takeaways
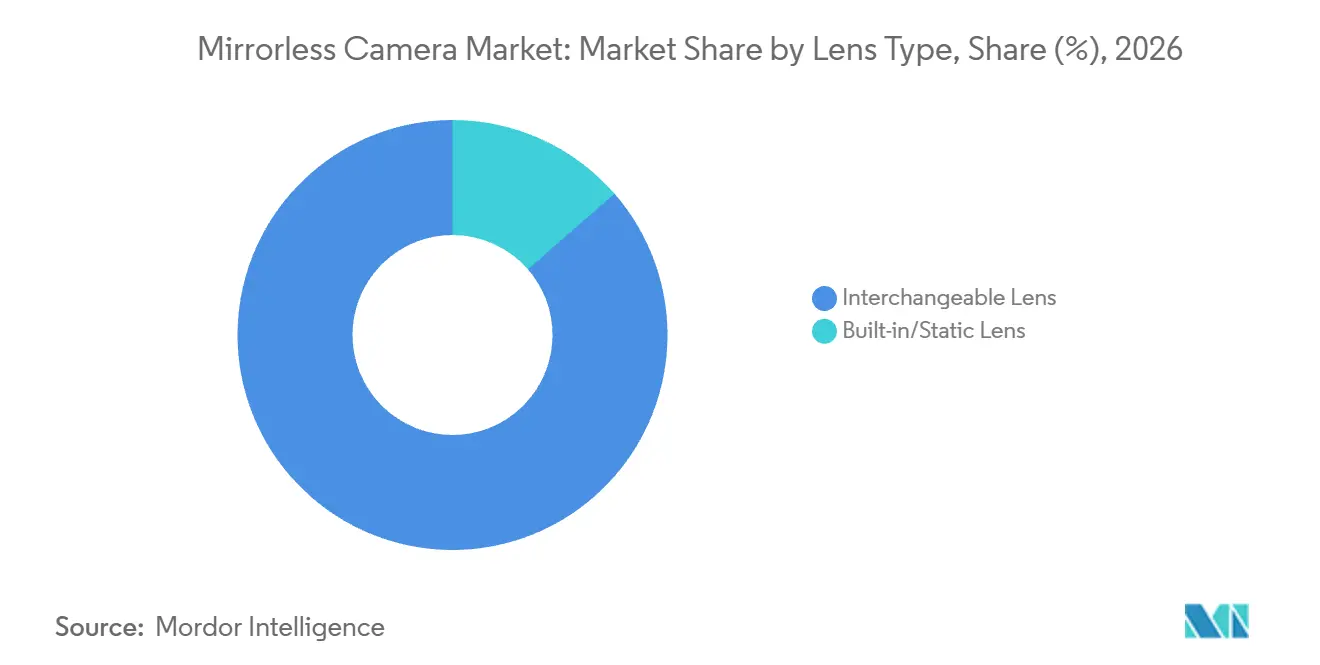
- By lens type, interchangeable-lens cameras held an 86.42% mirrorless camera market share in 2026, while built-in/static-lens cameras are forecast to grow fastest at a CAGR of 8.75% between 2027 and 2032.
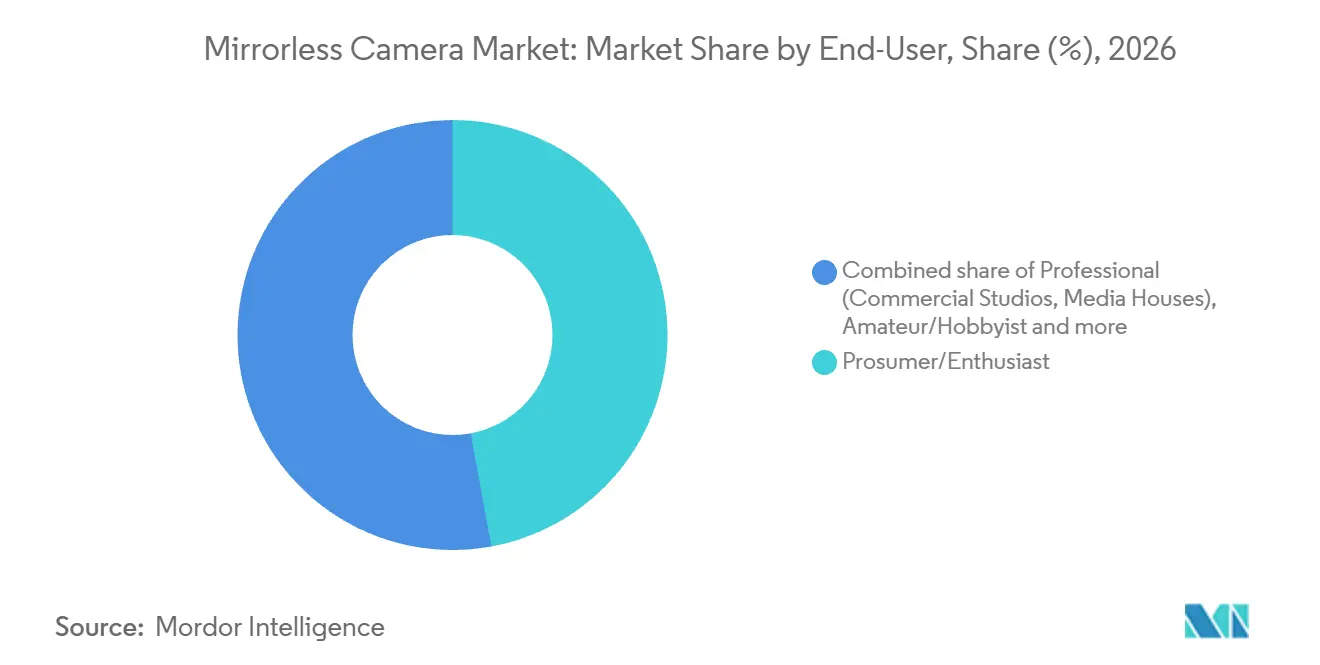
- Among end users, prosumers and enthusiasts accounted for a 47.1% share of the mirrorless camera market size in 2026, while professional users, including commercial studios and media houses, are forecast to grow fastest at a CAGR of 5.92% between 2027 and 2032.
- By video resolution, cameras recording up to 4K held 60.72% of revenue in 2026, while above 6K/8K models are forecast to grow fastest at a CAGR of 9.85% between 2027 and 2032.
- Across price points, mid-range cameras priced from USD 1,000 to USD 3,000 held 50.55% of revenue in 2026, while high-end cameras priced above USD 3,000 are forecast to grow fastest at a CAGR of 8.3% between 2027 and 2032.
- Within distribution channels, offline retail, including brand and specialty stores, accounted for 67.16% of revenue in 2026, and online retail is forecast to grow fastest at a CAGR of 8.75% between 2027 and 2032.
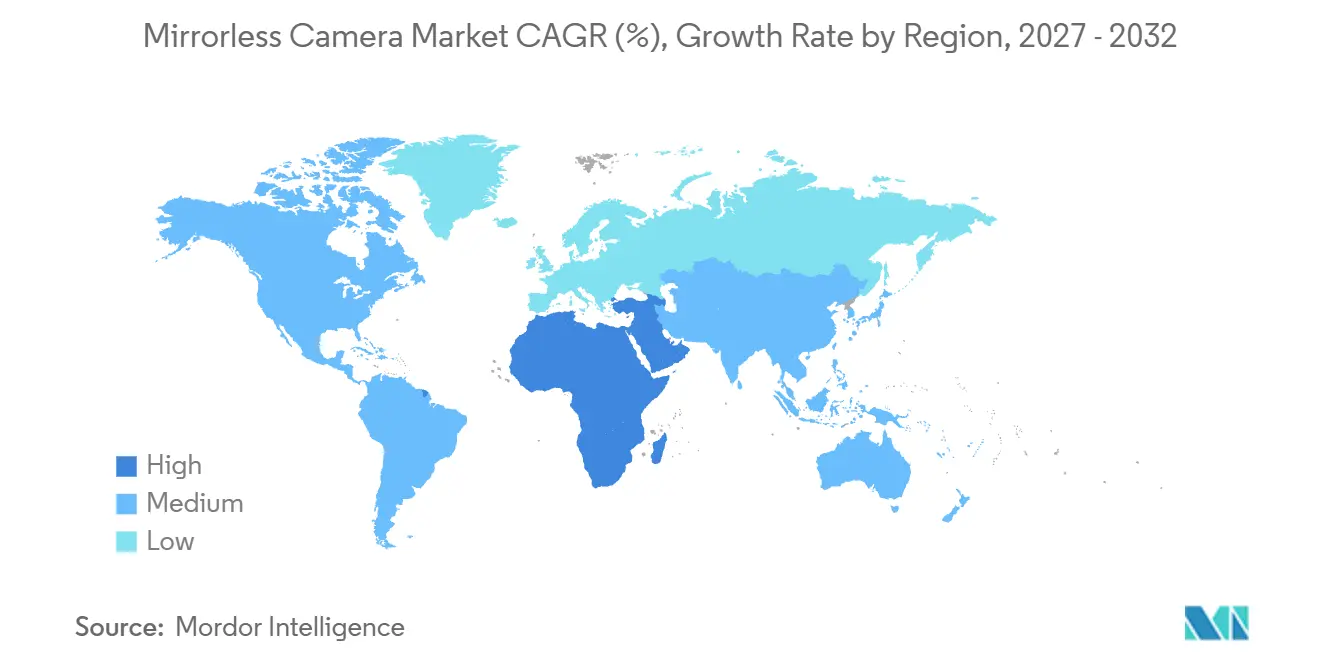
- Across regions, Asia-Pacific held 35.95% of revenue in 2026, while the Middle East and Africa region is forecast to grow fastest at a CAGR of 8.6% between 2027 and 2032.
Note: Market numbers in this report are based on Mordor Intelligence's proprietary estimation framework, which combines nine months of actuals with Q4 projections for base year 2026.
Market Trends and Insights
Drivers Impact Analysis of Mirrorless Camera Market*
| Driver | (~) % Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
|---|---|---|---|
| Booming Demand for 4K/6K Hybrid-shooting Models Among Content Creators | +3.5% | Asia-Pacific, Europe, and North America | Short term (≤ 2 years) |
| Surging Adoption of Full-Frame Bodies by Wedding and Event Professionals in Europe | +1.3% | Across European countries | Medium term (2-4 years) |
| Corporate and Education Sector Shift to Mirrorless for Live-Streaming Set-ups (North America) | +1% | Within the Canadian market | Medium term (2-4 years) |
| Government Film-Incentive Programs Fueling High-End Purchases (Middle East) | +0.5% | Across Saudi Arabia | Medium term (2-4 years) |
| Rapid Lens-Road-Map Expansion by Japanese OEMs Accelerating Upgrade Cycles | +0.4% | Japan, North America, and Europe | Medium term (2-4 years) |
| Transition of Broadcasters from ENG Camcorders to Mirrorless Systems (Asia) | +0.2% | Across Asian countries | Long term (≥ 4 years) |
| Source: Mordor Intelligence | |||
Booming Demand for 4K/6K Hybrid-shooting Models Among Content Creators
Creators seeking video-focused cameras give manufacturers a reason to compete on recording utility alongside still-image capabilities. Canon Inc. reported increased Q3 2025 sales of the EOS R50 V mirrorless camera and PowerShot V1 compact camera following favorable response from social-media and vlog video users. For 2025, Canon also reported expanded interchangeable-lens camera sales amid an increase in camera users, especially young people. A hybrid body can make a dedicated device relevant to more of a buyer's output by combining still-image and video utility. Video-led buyer recruitment therefore offers manufacturers a demand route beyond replacement purchases by established stills photographers.
Surging Adoption of Full-Frame Bodies by Wedding and Event Professionals in Europe
For wedding professionals, repeated paid coverage can improve the economics of a full-frame body over its service life. By February 2025, Nottinghamshire wedding photographer Ed Godden reported shooting more than 80 weddings with his first Sony α7 IV full-frame body, bought in summer 2022. Spreading acquisition cost across repeated assignments can make a higher-value body commercially viable without requiring every booking to recover a large equipment expense. In a January 2026 account, Godden referred to his α7 IV bodies and described a recent London wedding shot with 35mm, 20mm and 85mm lenses. His multi-body practice illustrates demand for additional bodies within an established system, so suppliers can sell another body to a working wedding photographer before a serviceable camera needs replacing.
Corporate and Education Sector Shift to Mirrorless for Live-Streaming Set-ups (North America)
A shared media room makes a mirrorless camera part of an institution's production infrastructure. On September 4, 2026, the University of Victoria in Canada made its CLE B023 studio available for booking by students, instructors, and staff, with a Sony a6400 camera, capture hardware, and livestreaming software. This setup makes the equipped room the relevant unit of demand rather than the number of individual users. Equipping additional rooms could create demand for bodies connected to capture hardware and production software. Suppliers can therefore address institutional expansion through complete room packages, with camera demand linked to new installations rather than repeat bookings.
Government Film-Incentive Programs Fueling High-End Purchases (Middle East)
Production incentives can strengthen the business case for high-end bodies by supporting the projects that use imaging equipment. The Saudi Film Commission announced a film-production cash rebate of up to 60% of expenses in Saudi Arabia on May 15, 2026.[1] The upper limit makes project qualification commercially important, because producers cannot treat the maximum as an automatic reduction in production costs. The increase from 40% strengthens the incentive to locate qualifying productions in Saudi Arabia, potentially expanding paid shooting activity. High-end mirrorless purchases become more defensible when repeated paid shoots can spread ownership costs, making utilization the decisive link between production support and equipment demand.
Restraints Impact Analysis of Mirrorless Camera Market*
| Restraint | (~) % Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
|---|---|---|---|
| Flagship-Smartphone Computational Photography Cannibalizing Entry-Level Sales | -0.6% | Asia-Pacific, Europe, and North America | Long term (≥ 4 years) |
| Supply-chain Volatility in CMOS and IBIS Components Affecting ASPs | -0.4% | Within the Japanese market | Short term (≤ 2 years) |
| Steep Learning-Curve Limiting Adoption by First-Time Hobbyists | -0.2% | North America, Europe, and Asia-Pacific | Medium term (2-4 years) |
| Import Tariff Escalations on Optics in South America | -0.2% | Across South America | Short term (≤ 2 years) |
| Source: Mordor Intelligence | |||
Flagship-Smartphone Computational Photography Cannibalizing Entry-Level Sales
A first-time camera buyer needs an additional photographic benefit when a flagship smartphone already serves the intended output. The restraint is strongest when the buyer's existing phone can complete the task for which a separate camera is being considered. In that case, an entry-level body adds a purchase and another device to carry, so its advantages must justify that additional commitment. A dedicated camera can answer with capabilities suited to a particular shooting task, but those capabilities need to matter to the first-time user. The remaining commercial hurdle is the incremental value of a second device, which can delay entry into a camera system even when body prices do not rise.
Supply-chain Volatility in CMOS and IBIS Components Affecting ASPs
For camera producers, component procurement pressure can erode the room to price a model for wider adoption. On June 24, 2025, Panasonic announced a 4% to 5% shipment-price increase for its LUMIX DC-GH7 and DC-GH7L mirrorless cameras, citing tight semiconductor and other component supply. The company said internal efforts could not absorb procurement pressure from raw-material prices, component supply, and exchange-rate changes. A higher shipment price can move the recovery burden toward distributors and retailers, leaving the eventual retail offer dependent on how that cost is absorbed. The constraint is a tighter cost base for bringing the same camera to the buyer, with less room for price-led expansion.
*Our forecasts treat driver/restraint impacts as directional, not additive. The impact forecasts reflect baseline growth, mix effects, and variable interactions.
Mirrorless Camera Market Segment Analysis
By Lens Type:
System Flexibility and Complete Camera DesignInterchangeable-lens cameras accounted for an 86.42% share of the mirrorless camera market size in 2026, making them the largest segment. The Camera & Imaging Products Association (CIPA) recorded 6.31 million mirrorless camera shipments worldwide in 2025, up 12.5% from 2024.[2] A system that lets a buyer change lenses can serve changing capture requirements while the body remains part of the same equipment platform. That flexibility supports separate decisions about an optical upgrade and a body replacement, allowing each purchase to address a particular shooting task. For a manufacturer, the commercial value lies in keeping the body relevant as the buyer changes lenses for different shooting needs.
Built-in/static-lens cameras are forecast to be the fastest-growing segment, with a CAGR of 8.75% between 2027 and 2032. A fixed optical configuration makes the initial camera choice decisive, because later lens changes cannot broaden its shooting role. Buyers can evaluate a complete camera around a defined assignment, while suppliers can develop the body and permanent optics as one proposition. That integration can simplify the equipment decision, but it also makes a poor match between the lens and the intended task harder to correct. Targeted complete-camera offers whose fixed optics suit the buyer's main application carry this segment's growth.

By End-User:
Individual Demand and Professional System AdoptionProsumers and enthusiasts represented a 47.1% mirrorless camera market share in 2026 and formed the largest segment. Canon reported sales growth for the EOS R6 Mark III in the first half of 2026. Canon released the full-frame mirrorless model in November 2025 for advanced amateur users. An advanced-amateur buyer can assess a full-frame body by its value to personal photography, without requiring paid assignments to recover the purchase price. That opens a separate route to revenue for manufacturers, since an individual's photographic ambitions can support a full-frame upgrade outside a commercial studio's equipment cycle.
Professional users, including commercial studios and media houses, are forecast to be the fastest-growing segment, with a CAGR of 5.92% between 2027 and 2032. The 2025 Professional Photographer Reader Study from the Professional Photographers of America (PPA) reported 78% mirrorless adoption and 64% DSLR use among respondents.[3] It also reported 83% studio or photography-business ownership among PPA members. A photographer operating a studio can assign a new mirrorless body a working role alongside equipment already supporting the business. The commercial opening includes supplementary-body sales to established operators, giving manufacturers a route beyond the complete replacement of a professional's existing camera system.
By Video Resolution:
Established 4K Demand and Higher-Resolution ApplicationsCameras recording up to 4K held 60.72% of the market in 2026, making them the largest segment. In BCN Ranking's January through June 2026 sample from major Japanese electronics retailers and online shops, Canon's EOS R50 ranked first among mirrorless camera series by unit sales. Series-level volume leadership and a 4K recording ceiling can coexist, so the highest resolution is not a prerequisite for leading unit sales in that Japanese sample. A higher-resolution upgrade needs an application that benefits from the added capture capability, because resolution alone does not determine the required output. Up-to-4K bodies can therefore retain a volume role alongside higher-resolution systems, with the upgrade case depending on the work the buyer intends to deliver.
Above 6K/8K cameras are forecast to be the fastest-growing segment, registering a CAGR of 9.85% between 2027 and 2032. Canon reported steady Q2 2025 sales of its full-frame mirrorless EOS R5 Mark II. The model can directly record 8K 60p RAW video. The combination places high-resolution capture within an established commercial camera offer, so suppliers can frame the upgrade around a specific production requirement. Growth can come from making 8K RAW capture useful to more recording applications, extending an established capability to additional buyers who can justify using it.
By Price Point:
Mid-Range Volume and High-End Transaction ValueMid-range cameras priced from USD 1,000 to USD 3,000 held 50.55% of the market in 2026, making them the largest segment. In April 2025, the month it went on sale on April 25, Nikon's Z5II captured 33.4% of sampled Japanese full-frame mirrorless unit sales. Its sampled tax-exclusive average price was JPY 247,000 (USD 1,712), combining body-only and lens-kit sales. That price placed it below the full-frame sample's average, giving this configuration a relative price advantage within that camera class. A mid-range supplier can thus offer full-frame capability at a lower configuration price, making affordability within full-frame the basis of its offer.
High-end cameras priced above USD 3,000 are forecast to be the fastest-growing segment, with a CAGR of 8.3% between 2027 and 2032. Canon reported increased Q1 2025 sales of full-frame cameras, especially the EOS R5 Mark II. Canon Canada's July 17, 2024 launch announcement estimated the body-only price at CAD 5,899.99 (USD 4,311.3 at that day's Bank of Canada rate), placing it above USD 3,000. At this end of the range, a transaction can contribute more revenue per camera, making the value of each configuration important to the sales proposition. Premium suppliers can expand revenue through a higher-value sales mix as well as additional units, giving a focused high-end offer commercial relevance without mass-market volumes.
By Distribution Channel:
Physical Retail Scale and Specialist Online SellingOffline retail, including brand and specialty stores, held 67.16% of the market in 2026 and was the largest segment. In 2025, Japan's large-scale home-appliance specialty retailers operated 2,657 stores. Their camera-equipment category, including lenses, accessories, and optical products, generated JPY 139.2 billion (USD 930.7 million) in sales during 2025. Store coverage and a broad equipment category give camera suppliers a channel that can present the body alongside its associated optical choices. An integrated camera-and-lens offer can address more of the shooting configuration within the physical retailer's established selling role.
Online retail is forecast to be the fastest-growing segment, registering a CAGR of 8.75% between 2027 and 2032. Camera Kitamura reported record total sales across its Rakuten marketplace shop during the year-end 2025 Rakuten Super Sale. Kitamura also sells new cameras online. Marketplace sale events such as the Rakuten Super Sale give specialist online shops that stock new cameras a promotional channel to buyers, though Kitamura's record covers the whole shop and not cameras alone.
Geography Analysis
Asia-Pacific Mirrorless Camera Market
Asia-Pacific held a 35.95% mirrorless camera market share in 2026, making it the largest geography. CIPA member companies, including their overseas production, shipped 1.9 million mirrorless cameras to China in 2025, up 15.9% from 2024. Canon India announced its official consumer e-Shop on January 20, 2025, with products supplied by authorized partners, while Henry's Cameras opened a Cagayan de Oro City branch in the Philippines on April 7, 2025. In South Korea, Nikon Imaging Korea reported that teenagers and users in their 20s and 30s formed the majority of its website registrants for mirrorless and cinema line products as of November 2025. Regional expansion can therefore depend on organizing authorized distribution as well as supplying camera bodies, with partners connecting the manufacturer's offer to customers beyond an individual retailer's store footprint.
Middle East and Africa Mirrorless Camera Market
The Middle East and Africa region is forecast to be the fastest-growing geography, with a CAGR of 8.6% between 2027 and 2032. In 2025, Hot Cold Studio, a Dubai studio operator that rents cameras and production equipment, joined Grand Stores, a professional-imaging distributor and retailer in the United Arab Emirates. Hot Cold said the tie-up gave its clients access to a broader equipment range and expanded inventory backed by the distributor. A distributor-backed rental fleet gives production crews equipment access beyond direct retail sales, which is where suppliers find the opening in this region.
In Europe, EU radio-equipment rules have required USB-C ports since December 28, 2024, for digital photo and video cameras with removable or embedded rechargeable batteries and wired charging. The EU exception applies to digital cameras designed exclusively for the audiovisual sector or for security and surveillance. In North America, Camera West opened a San Francisco photographic-equipment flagship in March 2026. In South America, Brazil's GECEX rejected Canon do Brasil's 2025 request to reduce a 20% import duty to 0% for a specified professional APS-C interchangeable-lens camera configuration. These cases distinguish a design obligation for covered EU cameras from a local retail expansion and a rejected Brazilian tariff request, making their commercial relevance depend on product eligibility and location.
Regulatory Framework and Outlook
The comparison covers selected jurisdictions from the perspective of manufacturers and importers selling radio-equipped mirrorless cameras. The United Kingdom column covers Great Britain's market-access framework. The comparison focuses on covered radio functions, because authorization routes depend on product classification. Product conformity therefore has to be addressed for the actual configuration offered in each destination.
Regulatory Table of Mirrorless Camera Market
| Decision factor | United States | United Kingdom | Brazil |
|---|---|---|---|
| Primary authority | FCC Office of Engineering and Technology | Ofcom for spectrum; local Trading Standards for other aspects | Anatel |
| Key instruments or direction | 47 CFR Part 2; proposed foreign assessment-body recognition conditions | Radio Equipment Regulations 2017, Great Britain | Resolution 715/2019; Certifica for general new requests |
| Commercial effect | Classification-specific RF authorization before marketing or import | Conformity and importer traceability; conditional packaging or document identification | Designated-body certification and Anatel homologation before commercial sale |
| Current policy attractiveness | Medium | Medium | Medium |
| Future direction of policy attractiveness | Hardening | Hardening | No change |
| Source: Mordor Intelligence | |||
The United States is rated Medium because covered RF devices need authorization before market entry. Hardening reflects the FCC proposal released May 1, 2026, concerning recognition of foreign assessment bodies in non-reciprocal free-trade-agreement economies, which could narrow testing options if implemented. Great Britain's Medium rating balances conformity and traceability duties against conditional flexibility, while its temporary EEA/Swiss importer-labeling alternative applies only before December 31, 2027, underpinning Hardening. Brazil is Medium because certification and homologation precede commercial sale, while the September 8, 2026 Certifica transition changes the general application route and preserves the access duty, supporting No change.
Value Chain Stages
The value chain compares component supply, lens and body production, retail distribution, and maintenance as separate earning stages. Canon's RF lens lineup reached 63 models in 2025 within an Imaging Group that also supplies mirrorless cameras. That breadth makes coordination of camera and lens offerings part of the economic role of an integrated producer. Specialists participate through consumer-camera sensors, authorized retail, and paid maintenance.
Value Chain Analysis Table of Mirrorless Camera Market
| Primary activity | Key participants | Value capture | Bottleneck | Resilience response |
|---|---|---|---|---|
| Image-sensor supply | Consumer-camera sensor suppliers such as Sony Semiconductor Solutions Corporation | Component sales | Matching a sensor to the intended camera design | Qualify alternatives before committing a platform |
| Lens production | Lens manufacturers such as Canon Inc., Nikon Corp., and Sigma Corp. | Lens sales | Managing variation across a broad lens portfolio | Organize production around validated lens families |
| Camera-body integration | Camera producers such as Canon Inc. and Nikon Corp. | Camera-body and kit sales | Coordinating body and mount design changes | Reuse validated body and mount designs |
| Authorized retail distribution | Authorized retailers such as Adorama and B&H Photo | Retail product sales | Handoff from purchase to warranty registration | Guide buyers through registration for applicable benefits |
| Maintenance | Paid camera-maintenance providers such as Precision Camera & Video | Maintenance service fees | Diagnosing body and lens service needs | Triage the body and lens together before service |
| Source: Mordor Intelligence | ||||
The structural distinction is between winning a body sale and retaining work after that body enters service. Precision Camera & Video's mirrorless or DSLR maintenance package includes one lens. That bundling gives an independent provider a commercial relationship with the working camera system, allowing service revenue to continue without requiring a new body sale.
Competitive Landscape
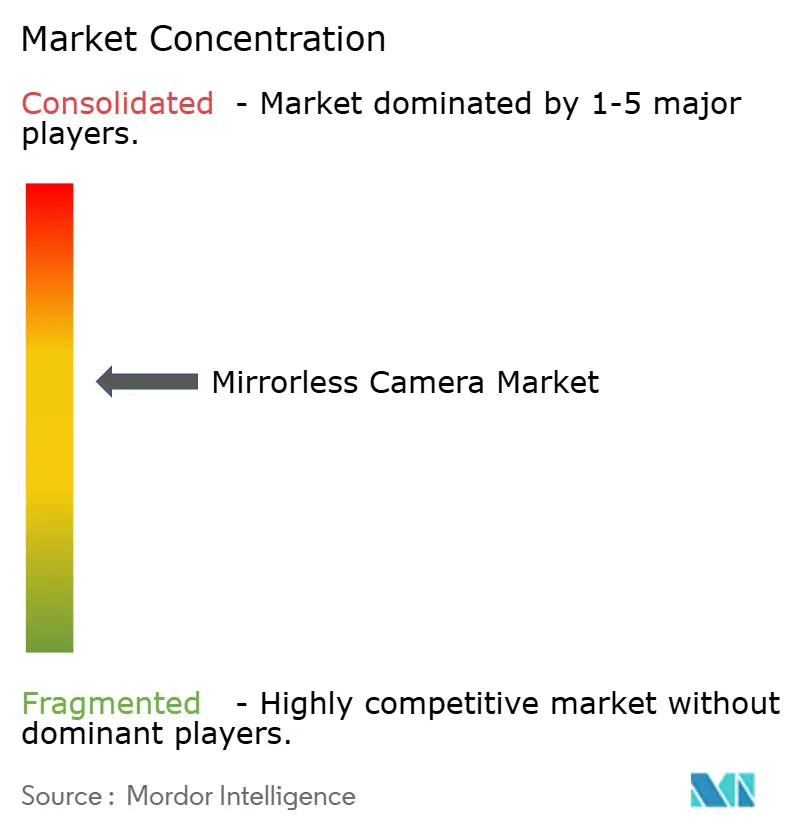
Competition centers on Canon Inc., Sony Corp., Nikon Corp., FUJIFILM Corp., and Panasonic Corp. as an established leading group. Canon's own survey placed its interchangeable-lens digital cameras, including SLR and mirrorless models, at No. 1 globally for the 23rd consecutive year in 2025. In BCN's 2025 point-of-sale data from participating Japanese retailers and online sellers, Sony ranked first in the mirrorless-camera category, accounting for 29.9% of the recorded unit sales. The structure is moderately concentrated around those established suppliers, while differing camera systems leave room for competition within particular uses and geographies.
Nikon released the full-frame ZR cinema camera in 2025, combining Nikon technologies with those of subsidiary RED Digital Cinema, Inc. for cinema, high-end productions, and creators. FUJIFILM announced the global X-E5 launch in June 2025, pairing a compact mirrorless body with a 40.2-megapixel sensor and X-Processor 5. These approaches differentiate camera offers through the production capability or physical format built into the body. Nikon competes for cinema-production requirements, while FUJIFILM's X-E5 addresses compact-body use, so matching sensor resolution alone would leave those different shooting priorities unresolved.
Panasonic reported that its share of Europe's full-frame camera market reached 10% in 2025, up from 3% in 2020. On February 25, 2025, Panasonic Entertainment & Communication Co., Ltd., the Panasonic group's camera business, announced a partnership with photography software provider Capture One, whose version 16.5.7 added tethering support for the LUMIX S1RII. The camera maker also declared the S1RII body, model DC-S1MYR 2, conformant with EU Directive 2014/53/EU. For covered radio equipment, manufacturers must declare conformity after assessment demonstrates compliance, making the declaration a market-access baseline. A challenger targeting Capture One studios therefore needs compliant radio-equipped bodies and tethered capture support that competes with the S1RII's software integration.
Mirrorless Camera Industry Leaders
-
Canon Inc.
-
Sony Corp.
-
Nikon Corp.
-
FUJIFILM Corp.
-
Panasonic Corp.
- *Disclaimer: Major Players sorted in no particular order
Mirrorless Camera Market Companies Covered in this Report
- Canon Inc.
- Sony Corp.
- Nikon Corp.
- FUJIFILM Corp.
- Panasonic Corp.
- OM Digital Solutions Corp.
- Leica Camera AG
- Ricoh Imaging Co. Ltd. (Pentax)
- Sigma Corp.
- Victor Hasselblad AB
- Blackmagic Design Pty Ltd.
- SZ DJI Technology Co. Ltd.
- GoPro Inc.
- Phase One A/S
- Sharp Corp. (8K Mirrorless)
- Z CAM Ltd.
- Eastman Kodak Co.
- Samsung Electronics Co. Ltd.
- Xiaomi Corp. (Concept APS-C)
- RED Digital Cinema Inc.
Key Opportunities for Market Participants
The comparison focuses on application-specific mirrorless packages for Indian photography and video buyers. CIPA's 2025 review described camera selection by intended use and desired features, and characterized mirrorless models as suitable for photography and video. Panasonic Life Solutions India launched the full-frame mirrorless LUMIX S1II and S1IIE in India in 2025 for uses including weddings, commercials, fashion, and documentaries. Those applications create different selling propositions even when the enabling camera platform is shared.
Market Opportunities Table of Mirrorless Camera Market
| Opportunity | Why now | Buyer / lead segment | Recommended play | Main barrier | Likely beneficiaries |
|---|---|---|---|---|---|
| Combined wedding stills and video coverage | The 2025 Indian launch targets wedding photography and video work | Wedding photographers and videographers | Build a combined-coverage body-and-lens package | Proving the same setup suits both required outputs | Panasonic Life Solutions India and authorized dealers |
| Higher-resolution commercial capture packages | The S1II offers 5.8K and 5.1K recording up to 60 fps | Commercial and documentary production crews | Demonstrate recording formats against a defined production brief | Establishing a production need for the added recording capability | Panasonic Life Solutions India and authorized dealers |
| Purpose-specific creator upgrades | The S1IIE is positioned for content creators seeking an upgrade | Creators evaluating a dedicated mirrorless upgrade | Demonstrate improvement in the creator's intended output | Showing an improvement sufficient to justify replacing a working setup | Panasonic Life Solutions India and authorized dealers |
| Source: Mordor Intelligence | |||||
One concrete opening is a wedding package that earns its value across both stills and video deliverables. Dealers can demonstrate both outputs before selecting lenses, so the proposed equipment is tested against the complete assignment. That connects the body sale to the wedding service being delivered, giving authorized Indian dealers a concrete way to compete through the package's fitness for paid work.
Recent Industry Developments in Mirrorless Camera Market
- Sep 2026: Nikon Corp. announced the release of the Z5IIC full-frame mirrorless camera featuring the Nikon Z mount.
- Jun 2026: Canon Inc. launched the EOS R6 V, a full-frame mirrorless camera for video creators.
- May 2026: Sony Electronics introduced the Alpha 7R VI full-frame mirrorless interchangeable-lens camera.
Mirrorless Camera Market Report Scope and Research Methodology
Market Definition and Coverage
Mirrorless camera market measures annual worldwide revenue from mirrorless camera sales, classified by lens configuration, buyer type, video resolution, price point, retail channel, and region. Sales are valued in USD at the final sale to the buyer.
Scope exclusions: DSLR cameras, fixed-lens compact digital cameras, standalone camera lenses and accessories, and after-sales services sold separately from a camera are excluded.
Segments Covered in This Report
- By Lens Type
- Built-in/Static Lens
- Interchangeable Lens
- By End-User
- Professional (Commercial Studios, Media Houses)
- Prosumer/Enthusiast
- Amateur/Hobbyist
- By Video Resolution
- Up to 4K
- 4K - 6K
- Above 6K/8K
- By Price Point
- Entry-Level (Less than USD 1000)
- Mid-Range (USD 1000 - USD 3000)
- High-End (Above USD 3000)
- By Distribution Channel
- Offline Retail (Brand and Specialty Stores)
- Online Retail
- By Geography
- North America
- United States
- Canada
- Mexico
- Europe
- Germany
- United Kingdom
- France
- Nordics
- Rest of Europe
- South America
- Brazil
- Rest of South America
- Asia-Pacific
- China
- Japan
- India
- South-East Asia
- Rest of Asia-Pacific
- Middle East and Africa
- Middle East
- Gulf Cooperation Council Countries
- Turkey
- Rest of Middle East
- Africa
- South Africa
- Rest of Africa
- Middle East
- North America
Data Sources, Market Sizing, and Validation
Desk Research
Public sources such as CIPA's 2025 digital camera shipment tables and its 2026 shipment outlook provide worldwide unit and destination checks, while Canon's 2025 Imaging Group presentation and Nikon Report 2025 describe camera categories, product cycles, and company financial context. Such public materials help distinguish shipments and manufacturer performance from retail revenue, and the product definitions and reporting periods are checked before using them as indicators.
Public company filings and investor materials add company-level revenue and product-cycle context, while company announcements and retail observations can be checked against those series. These sources are not exhaustive, and further sources inform collection, validation, and clarification.
Primary Interviews and Surveys
Interviews and structured surveys would include camera manufacturers, distributors, specialist retailers, and professional, enthusiast, and amateur buyers across APAC, EMEA, and the Americas, with questions tailored to sales, pricing, and purchasing behavior. The evidence would be used to test secondary-source interpretations, check assumptions about product and channel coverage, and clarify missing or conflicting inputs, while gaps would be triangulated with independent company, shipment, and retail indicators before entering the model.
Distribution of primary research fieldwork respondents
| Company type | Respondent position | Region |
|---|---|---|
| Top tier: 35% | CXOs: 20% | APAC: 45% |
| Mid tier: 45% | Functional/Unit leaders: 35% | EMEA: 30% |
| Smaller Players: 20% | Managers: 45% | Americas: 25% |
Market-Sizing & Forecasting
The model estimates global annual final-sale revenue in USD with a top-down view of mirrorless camera demand, then divides that total across lens configuration, buyer type, video resolution, price tier, channel, and region using evidence on each group's sales mix. Key inputs include CIPA shipment volumes by camera type and destination, manufacturer camera revenue and product-cycle disclosures, observed camera and kit prices, channel mix from retailers and company reports, and buyer-use indicators such as professional video and creator demand. Shipment data anchor units, while price and product mix translate them into revenue.
Historical values and segment shares provide the starting series for a multivariate regression forecast, with scenario analysis used where component costs, exchange rates, or product launches could materially change the path. Selective bottom-up checks compare sampled camera and kit volumes multiplied by observed selling prices with the top-down estimates, using supplier roll-ups and retailer checks where public data allow, with gaps in those samples estimated from the nearest comparable product, channel, or region and checked against shipment and revenue trends. Segment shares are derived from the available category-specific volume, revenue, price, and channel evidence, and primary-research respondents would check the main variable-level forecasts and explain material divergences before model updates.
Data Validation & Update Cycle
Analysts triangulate manufacturer disclosures, CIPA shipments, public pricing, retail signals, and interview or survey evidence, then check totals, segment shares, year-over-year changes, and forecast inputs for anomalies against independent market signals. A second review traces each material input to its source and tests differences in product coverage, geography, unit, and year. Analysts resolve outliers before sign-off and re-contact respondents when an answer conflicts with a later disclosure, has an unclear period or definition, or materially changes a key input. The model is refreshed annually, revised between cycles when a material event changes demand or supply conditions, and given a fresh source and calculation review immediately before delivery.
Mordor Intelligence's Global Mirrorless Camera Market Size Measured Against Other Published Estimates
Published estimates can differ in the transactions and products they count and the inputs used to model demand. Mirrorless camera market measures annual worldwide revenue from mirrorless camera sales, classified by lens configuration, buyer type, video resolution, price point, retail channel, and region.
Key Gap Drivers include the study's defined coverage and market-specific modeling choices. Key inputs include CIPA shipment volumes by camera type and destination, manufacturer camera revenue and product-cycle disclosures, observed camera and kit prices, channel mix from retailers and company reports, and buyer-use indicators such as professional video and creator demand.
Benchmark comparison
| Source | Market Size | Gaps in Research Methodology |
|---|---|---|
| Mordor Intelligence | USD 5.64 B (2027) | |
| Global Consultancy A | USD 5 B (2025) | At its 2025 base, this estimate is 11.3% below this report's 2027 value of USD 5.64 B, 2 years later. The estimate uses a 2025 base year, two years before this report's 2027 measurement year. |
| Global Consultancy B | USD 4.14 B (2026) | At its 2026 base, this estimate is 26.6% below this report's 2027 value of USD 5.64 B, 1 year later. The published 2026 estimate precedes this report's 2027 measurement year. |
Mordor Intelligence's analysts triangulate manufacturer disclosures, CIPA shipments, public pricing, retail signals, and interview or survey evidence, then check totals, segment shares, year-over-year changes, and forecast inputs for anomalies against independent market signals.
Key Questions Answered in the Report
What is the mirrorless camera market size and growth outlook?
Revenue is projected to grow from USD 5.64 billion in 2027 to USD 7.42 billion by 2032, at a CAGR of 5.65% between 2027 and 2032.
What supports growth in mirrorless camera demand?
Video creation and shared institutional production setups support demand. In September 2026, the University of Victoria in Canada made a studio available with a Sony a6400 camera and livestreaming software.
Which lens configuration leads mirrorless camera revenue?
Interchangeable-lens models led with 86.42% of revenue in 2026.
Which companies lead the mirrorless camera industry?
Canon Inc., Sony Corp., Nikon Corp., FUJIFILM Corp., and Panasonic Corp. form the leading group.
What constrains mirrorless camera affordability?
Component-cost pressure can make price-led adoption harder. Panasonic announced a 4% to 5% shipment-price increase for DC-GH7 and DC-GH7L models on June 24, 2025.
Which region leads mirrorless camera revenue, and which grows fastest?
Asia-Pacific led with 35.95% of revenue in 2026. The Middle East and Africa region is forecast to grow fastest at a CAGR of 8.6% between 2027 and 2032.