
GEO Satellite Market Size and Share
Market Overview
| Study Period | 2019 - 2031 |
|---|---|
| Market Size (2026) | USD 4.98 Billion |
| Market Size (2031) | USD 10.33 Billion |
| Growth Rate (2026 - 2031) | 15.71 % |
| Fastest Growing Market | Asia-Pacific |
| Largest Market | North America |
| Market Concentration | Medium |
Major Players *Disclaimer: Major Players sorted in no particular order Image © Mordor Intelligence. Reuse requires attribution under CC BY 4.0. | |
GEO Satellite Market Analysis by Mordor Intelligence
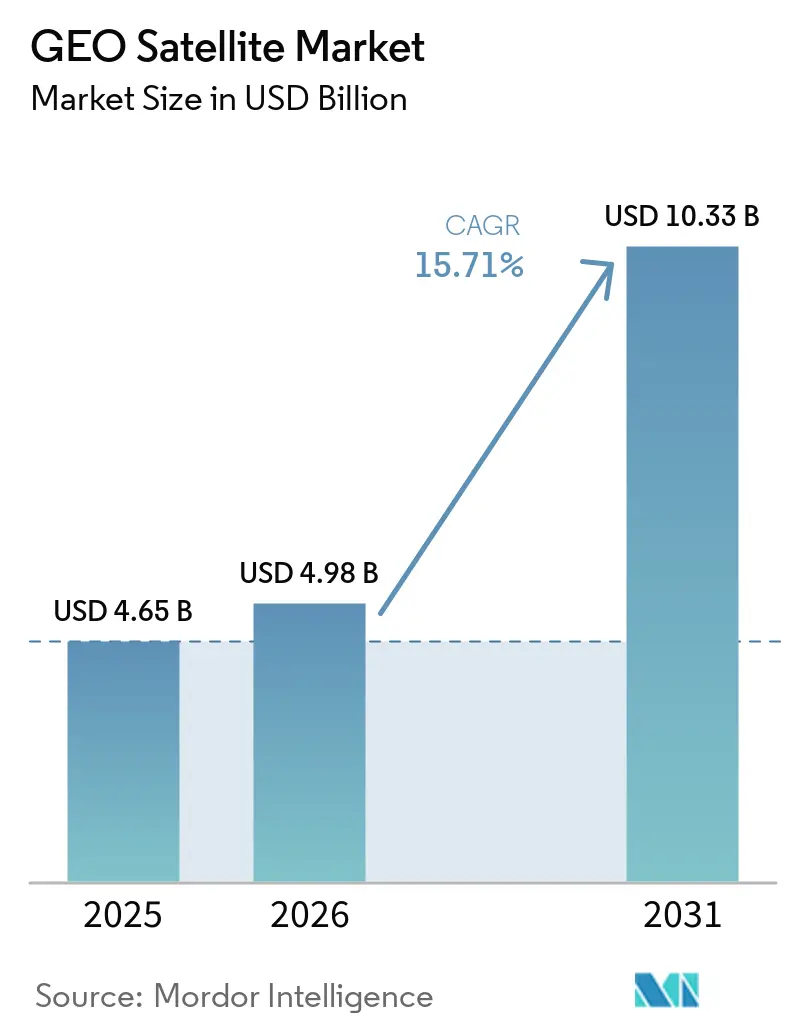
The GEO satellite market size was valued at USD 4.65 billion in 2025, and is projected to grow from USD 4.98 billion in 2026 to USD 10.33 billion by 2031, registering a CAGR of 15.71% between 2026 and 2031. The market remains centered on uses that benefit from continuous coverage over a fixed area. Enterprise backhaul, sovereign communications, broadcast distribution, and environmental monitoring remain important areas of demand. Software-defined payloads allow operators to adjust beam coverage and bandwidth after launch. This flexibility reduces the risk of a long-lived satellite becoming poorly matched to demand. Competition from non-GEO networks is increasing pressure on standard broadband capacity, while large fleet operators retain advantages in insurance, financing, and service assurance.
Key Report Takeaways
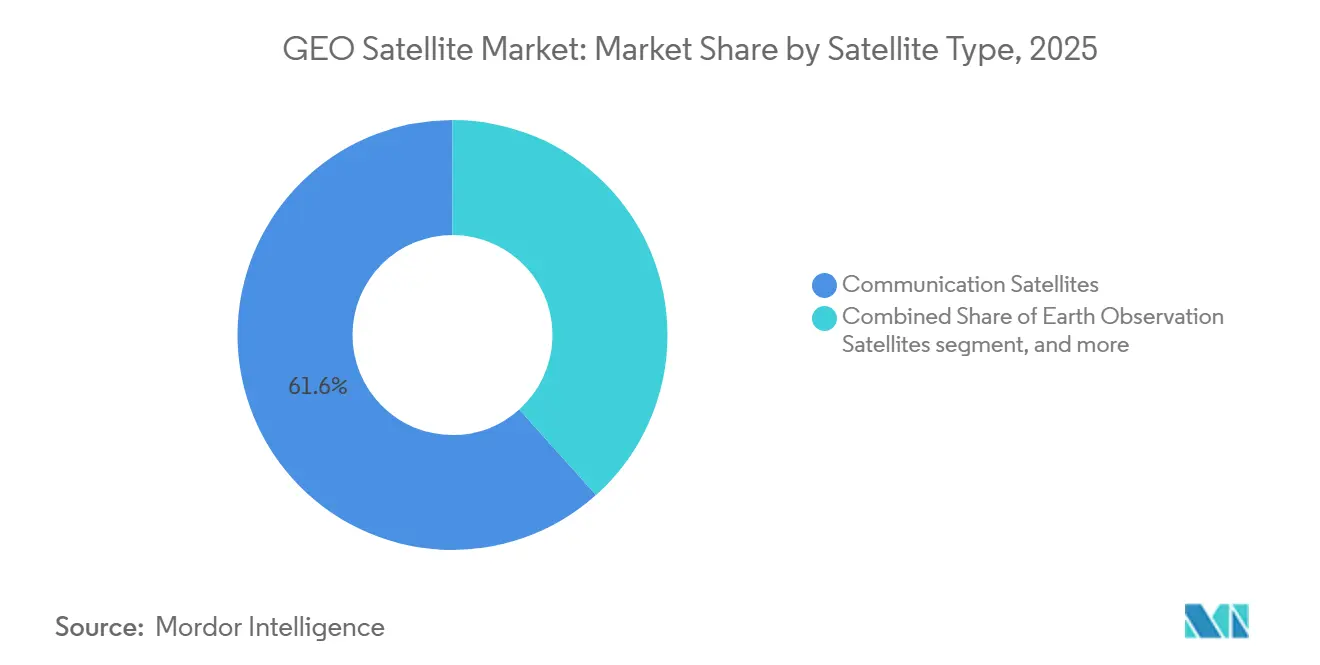
- By satellite type, communication satellites held 61.63% of the GEO satellite market share in 2025, while earth observation satellites are forecast to grow at a 17.71% CAGR through 2031.
- By satellite mass, large satellites accounted for 52.75% of the GEO satellite market size in 2025, while medium satellites are forecast to expand at a 19.83% CAGR through 2031.
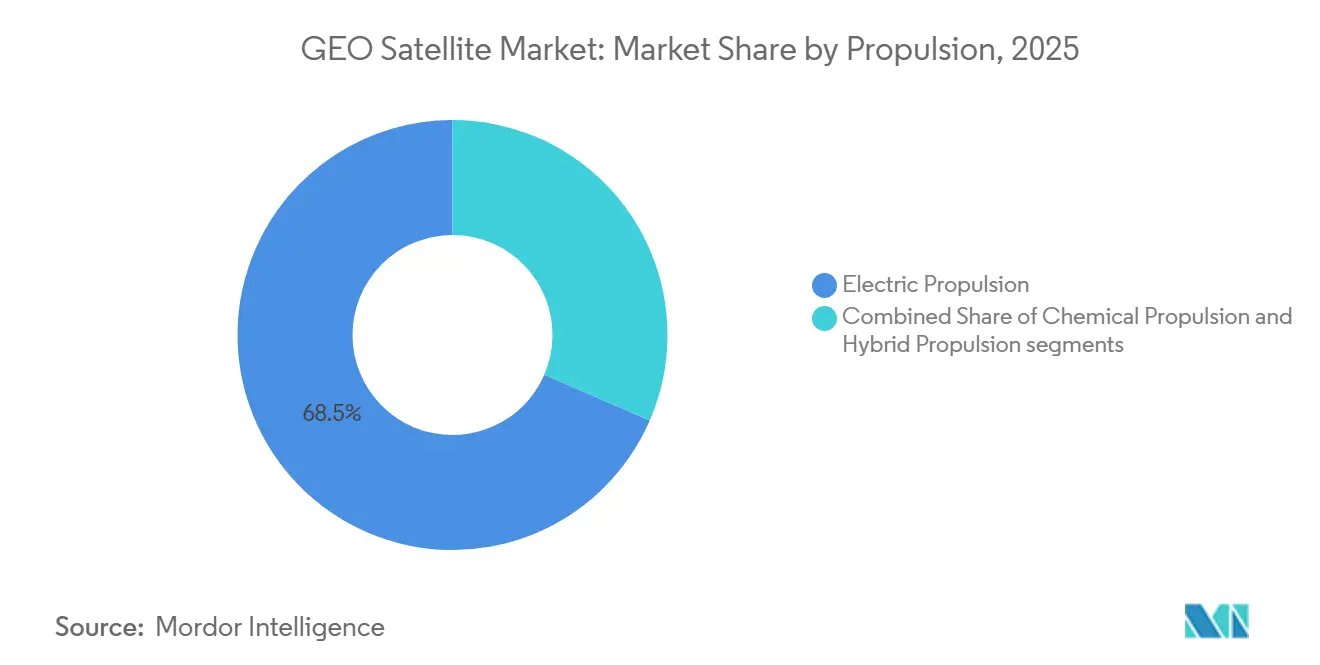
- By propulsion, electric propulsion captured 68.49% of the GEO satellite market share in 2025 and is projected to grow at an 18.73% CAGR through 2031.
- By end user, commercial users accounted for 58.63% of the GEO satellite market size in 2025 and are projected to grow at a 20.52% CAGR through 2031.
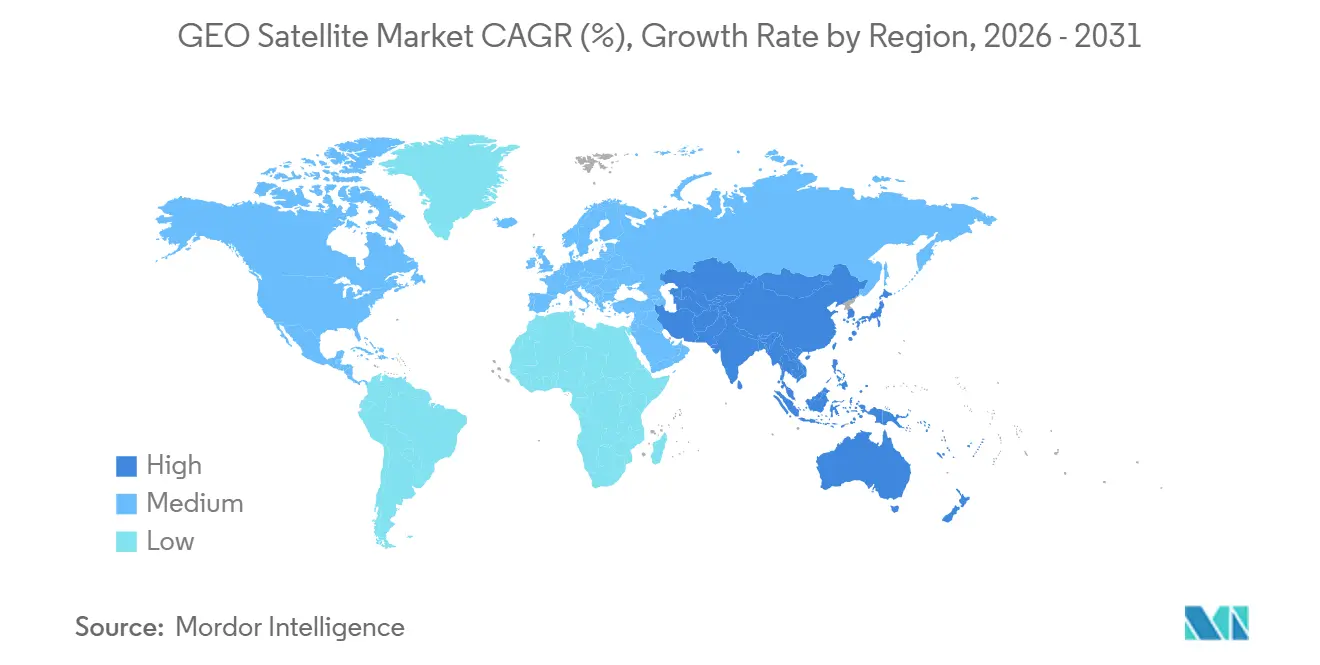
- By geography, North America held 46.77% of the GEO satellite market in 2025, while Asia-Pacific is forecast to grow at a 21.63% CAGR through 2031.
Note: Market size and forecast figures in this report are generated using Mordor Intelligence’s proprietary estimation framework, updated with the latest available data and insights as of January 2026.
Global GEO Satellite Market Trends and Insights
Drivers Impact Analysis*
| DRIVER | (~) % IMPACT ON CAGR FORECAST | GEOGRAPHIC RELEVANCE | IMPACT TIMELINE |
|---|---|---|---|
| Demand for high-capacity broadband, broadcasting, and backhaul | 3.50% | Global | Short term (≤ 2 years) |
| Government and defense demand for resilient wide-area connectivity | 2.80% | North America and Europe | Medium term (2-4 years) |
| High-throughput and software-defined payload adoption | 2.30% | Global | Medium term (2-4 years) |
| Multi-orbit network integration and GEO network resilience | 1.80% | North America and Asia-Pacific Core Markets | Medium term (2-4 years) |
| GEO on-orbit servicing and life-extension demand | 1.40% | North America and Europe | Long term (≥ 4 years) |
| Continuous coverage for weather, disaster, and environmental intelligence | 1.20% | Europe, Asia-Pacific, and Middle East and Africa | Long term (≥ 4 years) |
| Source: Mordor Intelligence | |||
Demand for High-Capacity Broadband, Broadcasting, and Backhaul
Demand for broadband, broadcasting, and backhaul services supports the GEO satellite market because these services require wide, stable coverage. Cellular backhaul, maritime links, and in-flight connectivity use a fixed footprint across large service areas. The Broadband Commission stated that global data demand will rise by at least 60% by 2035. Multi-year capacity contracts are already addressing this anticipated need.[1] Broadcast distribution also remains well-suited to GEO because a single transponder can reach millions of receivers simultaneously. In June 2026, NXGSAT and Universidad de Málaga validated a 3GPP-compliant 5G NTN modem through a live GEO payload, showing that existing assets can support terrestrial 5G backhaul. Rural areas across Sub-Saharan Africa, South Asia, and Latin America continue to rely on satellite capacity where terrestrial networks are uneconomic.
Government and Defense Demand for Resilient Wide-Area Connectivity
Government demand supports the GEO satellite market, where secure and persistent coverage is required across a large territory. Defense users value a fixed footprint when national communications need predictable coverage. The US Space Force PTS-G program supports small and agile GEO satellites for protected tactical communications. Viasat received a PTS-G Swarm 1 prime contract within a program carrying a USD 4.00 billion ceiling in June 2026.[2] The European Union (EU) activated GOVSATCOM in January 2026, providing member states with sovereign and encrypted satellite communications. Long-duration public contracts give manufacturers and operators greater visibility than commercial spot capacity. This demand is less exposed to changes in commercial capacity pricing.
High-Throughput and Software-Defined Payload Adoption
Software-defined systems are important to the GEO satellite market because satellites can remain in service for many years. Operators can change beam coverage, power allocation, and signal-processing functions after launch. This capability reduces the risk that demand moves away from an original coverage plan. Mitsubishi Electric received JAXA funding in July 2026 to develop a full digital payload with a direct-radiating array and digital beam-forming technology.[3] The FCC updated spectrum-sharing rules in May 2026, increasing the need for flexible platforms capable of managing co-channel interference.[4] Es'hailSat selected Thales Alenia Space's Space Inspire platform for Es'hail-3 and Türksat-Biruni. The selection shows how a single GEO position can meet broadband demand across Europe, Africa, and the Middle East.
GEO On-Orbit Servicing and Life-Extension Demand
On-orbit servicing supports the GEO satellite market by extending the useful life of operating assets. Satellites often approach retirement due to fuel constraints rather than payload failure. Servicing can defer replacement spending and preserve capacity on valuable orbital positions. SES signed an agreement with Infinite Orbits in November 2025 for Europe’s first commercial GEO life-extension mission. The planned Endurance docking vehicle is intended to extend the lifetime of at least 1 SES satellite by 5 years. SES has 5 servicing missions scheduled from 2026 through 2029. ESA also supports the RISE program with D-Orbit, planned for 2029, and broadens institutional backing for GEO servicing.
Restraints Impact Analysis*
| RESTRAINT | (~) % IMPACT ON CAGR FORECAST | GEOGRAPHIC RELEVANCE | IMPACT TIMELINE |
|---|---|---|---|
| Non-GEO constellation competition on latency and iteration speed | -2.80% | Global | Short term (≤ 2 years) |
| High launch, insurance, and geo insertion costs | -2.20% | Global | Medium term (2-4 years) |
| Spectrum, orbital slot, and licensing complexity | -1.50% | North America and Europe | Medium term (2-4 years) |
| Orbital debris, collision risk, and end-of-life compliance | -1.00% | Global | Long term (≥ 4 years) |
| Source: Mordor Intelligence | |||
Non-GEO Constellation Competition on Latency and Iteration Speed
Non-GEO networks constrain the GEO satellite market by offering lower latency for select connectivity use cases. Their shorter replacement cycles also allow faster upgrades to satellite hardware. Software-defined GEO payloads can adapt coverage and bandwidth, but they cannot change the physical limits of a satellite bus. The FCC’s 2026 spectrum-sharing action may change interference protection arrangements between non-GEO and GEO systems. Operators are therefore focusing on defense, maritime, and in-flight services where reliability and coverage matter more than latency. This shift places greater value on guaranteed service quality and specialized network design.
High Launch, Insurance, and GEO Insertion Costs
High launch, insurance, and insertion costs constrain the GEO satellite market by increasing the capital required per program. Heavy launch requirements and geostationary transfer orbit operations add cost before a satellite reaches service. Electric propulsion reduces launch mass but can extend orbit raising from 2 weeks to 4 to 6 months. This delays the start of revenue generation for a newly launched asset. High asset values also make insurance costs an important factor in project economics. Large fleet operators can spread these risks across more satellites and use larger launch contracts, while newer entrants face a higher capital barrier.
Spectrum, orbital slots, licensing, and end-of-life requirements also affect project timing and compliance costs. ITU-R Study Group 4 is developing removal standards and a space sustainability handbook under Resolution 74 from the Radiocommunication Assembly RA-23. These requirements make propulsion reserves and disposal planning important throughout a satellite's life. They also reinforce the relevance of service designs that can preserve or relocate GEO assets. The GEO satellite market, therefore, depends on both technical planning and demand for capacity.
*Our forecasts treat driver/restraint impacts as directional, not additive. The impact forecasts reflect baseline growth, mix effects, and variable interactions.
Segment Analysis
By Satellite Type: Communication Infrastructure Anchors Market, Earth Observation Redefines Growth
Communication satellites accounted for 61.63% of the GEO satellite market in 2025. Their position reflects established transponder leases, direct-to-home broadcasting, and cellular backhaul agreements. These contracts continue to support demand even as non-GEO networks expand. Communication payloads also provide the commercial base for many GEO fleet operators. Fixed service areas remain useful where a broad and persistent footprint is needed. This installed service model helps communication satellites remain the revenue anchor of the GEO satellite market.
Earth observation satellites are forecast to grow at a CAGR of 17.71% through 2031. Their growth is linked to the needs of defense surveillance, precision agriculture, and climate monitoring. GEO sensors can continuously monitor the same area, unlike systems that only provide periodic revisits. ESA’s Sentinel-4 instrument is hosted on MTG-S1, which was commissioned in 2026 for hourly atmospheric composition observations over Europe and northern Africa. Weather missions also benefit from long public procurement cycles. EUMETSAT’s MTG program provides Europe with operational weather observation into the 2040s.
Weather satellites are supported by national meteorological agencies that plan infrastructure over long periods. Their missions are less sensitive to short-term commercial capacity prices. Surveillance and intelligence satellites benefit from requirements for persistent monitoring. These requirements can justify specialized platforms and protected communications. The others category includes navigation augmentation and experimental payloads. Multi-mission architecture makes this smaller category increasingly relevant within the GEO satellite market.

By Satellite Mass: Large Platforms Lead Revenue, Medium Formats Drive Next-Cycle Growth
Large satellites accounted for 52.75% of the GEO satellite market share in 2025. Larger buses can carry more transponders and support greater lease revenue. They can also spread fixed launch and insurance expenses across a larger payload. This economic structure keeps large platforms important for high-throughput commercial services. Large systems remain particularly relevant for established operators with broad capacity needs. Their scale supports the GEO satellite market's central revenue model.
Medium-sized GEO satellites are projected to grow at a CAGR of 19.83% through 2031. Operators are accepting lower transponder capacity in return for faster procurement and greater flexibility. ReOrbit and SLI signed a EUR 150 million (USD 168.09 million) agreement, equivalent to USD 166 million, in March 2026 for 2 next-generation GEO communication satellites. The agreement used leasing terms to improve access to advanced GEO technology. Medium platforms can therefore bring new operators into the addressable customer base. The US Space Force also supports smaller maneuverable GEO systems through PTS-G.
Small GEO systems support government missions where rapid deployment and maneuverability are important. OHB SE agreed to supply 6 electric propulsion systems for SWISSto12's HummingSat platform. This activity shows that a small-GEO supply chain is forming. Small buses remain limited by available radio-frequency power and antenna aperture at GEO altitude. These limits reduce throughput compared with large satellites. ESA support for deployable reflector work on NEASTAR-1 helps reduce certification risk for first-generation small-GEO operators.
By Propulsion: Electric Systems Set the Baseline Across All Platform Classes
Electric propulsion accounted for 68.49% of the GEO satellite market in 2025 and is also forecast to grow at an 18.73% CAGR through 2031. This combination shows that electric systems have moved beyond early adoption. By 2027, electric propulsion will be the standard approach for GEO stationkeeping on new commercial satellites. Hall-effect and gridded-ion thrusters provide significant mass savings, increasing payload capacity. Those savings improve the revenue economics of a GEO satellite market program.
Electric systems can free 400 to 700 kg of structural mass for payload use. The benefit is especially important when transponder capacity determines service revenue. Impulse Space plans the first GEO in-space demonstration of its Electra propulsion system on GEO Express 1. Enpulsion launched its Nexus FEEP system in May 2025 for spacecraft up to 500 kg. These developments point to a broader supply base for electric propulsion. They also support more manufacturers offering all-electric GEO architectures.
Chemical propulsion remains relevant where orbit-raising speed is critical. Military satellites may not accept an electric orbit-raising period of 4 to 6 months. Hybrid designs provide an alternative for time-sensitive government programs. Astroscale has identified hydrazine refueling as a potential means to improve the economics of existing GEO fleets. Operators must also reserve propellant for disposal into graveyard orbits. This requirement continues to drive the need for propulsion capability across the GEO satellite market.
By End User: Commercial Sector Leads in Scale, Government Anchors Revenue Floor
Commercial users accounted for 58.63% of the GEO satellite market share in 2025 and are also forecast to grow at a 20.52% CAGR through 2031. Commercial demand includes broadband, broadcasting, backhaul, and managed communications services. These users are expanding services in locations where terrestrial networks have limited reach. Their projects often combine satellite capacity with managed network offerings. This model keeps commercial customers central to the GEO satellite market.
Space42 and Viasat signed a binding agreement in September 2026 to co-found Equatys. Each party committed up to USD 400 million in initial equity for direct-to-device and mobile satellite services. The venture is intended to extend coverage into places that terrestrial networks cannot serve. It also shows continued commercial interest in long-duration satellite connectivity. Government agencies are increasingly using commercial services for national security architectures. This creates additional revenue opportunities for commercially focused operators.
Government and civil users provide a stable revenue floor through long-duration contracts. GOVSATCOM gives EU member states access to secure satellite communications as of January 2026. These mandates are less dependent on commercial pricing cycles. Military users require hardened, anti-jam, and anti-spoofing systems. Manufacturers with defense-certified designs can command differentiated pricing. The mix of commercial and public demand supports a wider customer base for the GEO satellite market.
Geography Analysis
North America accounted for 46.77% of the GEO satellite market in 2025. The region benefits from deep capital markets, major satellite integrators, and a mature commercial space base. US licensing changes in July 2026 were intended to accelerate commercial satellite deployment. US Space Force procurement provides sustained visibility into demand through PTS-G, commercial services, and servicing contracts. The USD 4.00 billion PTS-G ceiling supports protected communications programs. Mexico's connectivity gap and Canadian GEO frequency activity add to regional demand.
Asia-Pacific is forecast to expand at a 21.63% CAGR through 2031. Rural, remote, and island populations create continuing demand for coverage beyond terrestrial networks. India, Japan, and China are expanding their national GEO capabilities. Mitsubishi Electric's JAXA-supported digital payload program strengthens Japan's role in next-generation GEO technology. China continues to develop its Zhongxing communication satellite fleet. India is progressing with GSAT replacement plans and commercial satellite broadband activity. South and Southeast Asian connectivity gaps sustain demand across service tiers.
Europe is the third-largest regional position in the GEO satellite market. ESA programs, GOVSATCOM, and IRIS² support European communications sovereignty. Thales Alenia Space, Airbus Defence and Space, and OHB SE form an established manufacturing base. The EU Space Act was presented in June 2025 to harmonize space activity rules across the union. Demand in the Middle East and Africa is linked to sovereign connectivity mandates and regional broadband footprints. Es'hailSat selected a software-defined platform for a satellite serving Europe, Africa, and the Middle East. South American demand is supported by Brazil's broadband expansion and service needs across rural areas.
Competitive Landscape
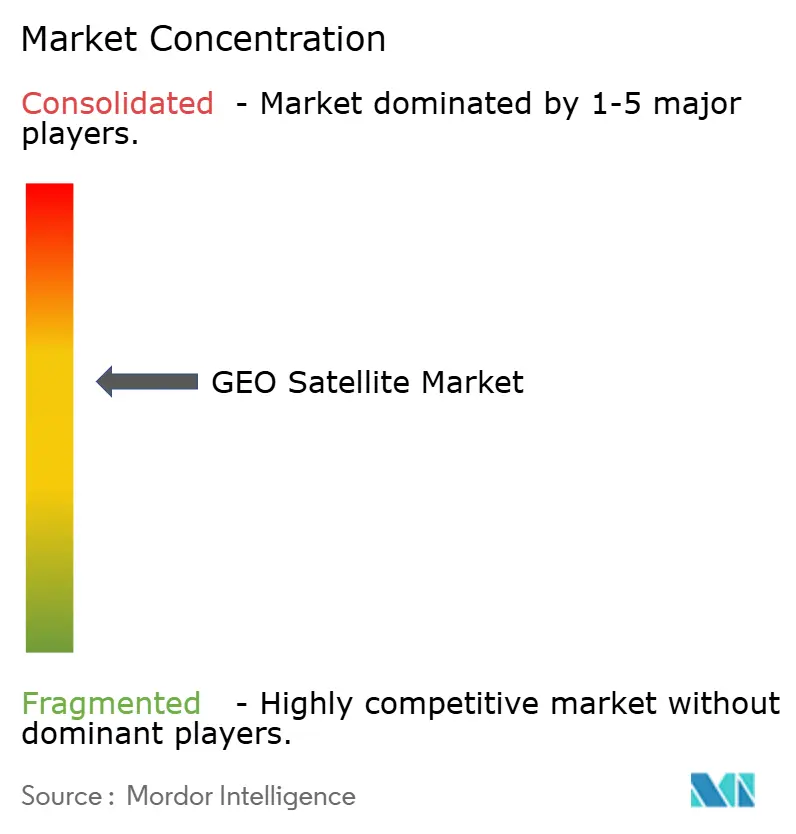
The GEO satellite market is moderately consolidated among prime integrators. Large defense and aerospace companies remain important in the production of large-class GEO buses. Specialized providers such as OHB SE, SWISSto12, and ReOrbit compete in the medium- and small-GEO platforms. These companies focus on shorter development cycles and lower unit costs. The competitive basis is moving beyond platform design alone. Manufacturers that combine bus production, software-defined payloads, and servicing can offer a broader system solution.
Northrop Grumman’s SpaceLogistics business is active in GEO servicing through its Mission Extension Pod work. SES agreed with Infinite Orbits in November 2025 on a commercial life-extension mission. ESA support for RISE and ClearSpace-Phoenix shows institutional interest in a broader servicing ecosystem. Astroscale’s LEXI vehicle and Infinite Orbits’ Endurance vehicle increase competitive pressure in the servicing market. Servicing capability can change the economics of fleet renewal. It can also help operators retain productive satellites for longer.
Viasat selected Rocket Lab in August 2026 to build a GEO satellite bus for the PTS-G Swarm 1 program. Mitsubishi Electric is developing a digital GEO payload with in-orbit software update capability. SWISSto12 partnered with HPS and LSS in May 2026 to deploy a large reflector on NEASTAR-1. Competitive openings remain in small GEO platforms below 1,000 kg. Hosted environmental and methane monitoring also remain relevant. Demand for servicing capacity exceeds the current availability of servicer fleets.
GEO Satellite Industry Leaders
-
Airbus SE
-
The Boeing Company
-
Thales Alenia Space
-
Lockheed Martin Corporation
-
Maxar Technologies Inc.
- *Disclaimer: Major Players sorted in no particular order
Recent Industry Developments
- September 2026: Space42 and Viasat signed a binding agreement to co-found Equatys, a direct-to-device and MSS connectivity platform, with each party committing up to USD 400 million in initial equity. Viasat is expected to be appointed the prime technology contractor, targeting coverage extension in geographies that terrestrial networks cannot serve.
- July 2026: SES Space & Defense won a 5-year Blanket Purchase Agreement with the US Space Force Space Systems Command to deliver managed TRANSEC-protected Ku-band satellite services globally.
- July 2026: Mitsubishi Electric was awarded a JAXA Space Strategy Fund subsidy to develop a fully digital GEO satellite payload featuring a direct-radiating array antenna and digital beam-forming technology, enabling in-orbit software updates.
- May 2026: SWISSto12 signed a partnership with German consortium HPS/LSS to supply a large deployable reflector for the NEASTAR-1 GEO mission, co-funded by ESA and DLR, targeting the world’s first direct-to-device media broadcasting from GEO.
Global GEO Satellite Market Report Scope
The GEO satellite market includes the design, engineering, production, assembly, integration, and testing of satellites and their major subsystems for deployment in GEO orbit. It covers the manufacture of satellite platforms/buses, payloads, propulsion systems, power systems, thermal and structural components, avionics, communication systems, and other spacecraft subsystems.
The GEO satellite market is segmented by satellite type, satellite mass, propulsion, end user, and geography. By satellite type, the market is segmented into communication satellites, Earth observation satellites, weather satellites, surveillance and intelligence satellites, and others. By satellite mass, the market is segmented into small, medium, and large. By propulsion, the market is segmented into electric propulsion, chemical propulsion, and hybrid propulsion. By end user, the market is segmented into commercial, government and civil, and military. The report also covers the market sizes and forecasts for the GEO satellite market in major countries across different regions. For each segment, the market size is provided in terms of value (USD).
| Communication Satellites |
| Earth Observation Satellites |
| Weather Satellites |
| Surveillance and Intelligence Satellites |
| Others |
| Small |
| Medium |
| Large |
| Electric Propulsion |
| Chemical Propulsion |
| Hybrid Propulsion |
| Commercial |
| Government and Civil |
| Military |
| North America | United States | |
| Canada | ||
| Mexico | ||
| Europe | United Kingdom | |
| France | ||
| Germany | ||
| Russia | ||
| Rest of Europe | ||
| Asia-Pacific | China | |
| Japan | ||
| India | ||
| Australia | ||
| Rest of Asia-Pacific | ||
| South America | Brazil | |
| Rest of South America | ||
| Middle East and Africa | Middle East | Saudi Arabia |
| United Arab Emirates | ||
| Rest of Middle East | ||
| Africa | South Africa | |
| Rest of Africa | ||
| By Satellite Type | Communication Satellites | ||
| Earth Observation Satellites | |||
| Weather Satellites | |||
| Surveillance and Intelligence Satellites | |||
| Others | |||
| By Satellite Mass | Small | ||
| Medium | |||
| Large | |||
| By Propulsion | Electric Propulsion | ||
| Chemical Propulsion | |||
| Hybrid Propulsion | |||
| By End User | Commercial | ||
| Government and Civil | |||
| Military | |||
| By Geography | North America | United States | |
| Canada | |||
| Mexico | |||
| Europe | United Kingdom | ||
| France | |||
| Germany | |||
| Russia | |||
| Rest of Europe | |||
| Asia-Pacific | China | ||
| Japan | |||
| India | |||
| Australia | |||
| Rest of Asia-Pacific | |||
| South America | Brazil | ||
| Rest of South America | |||
| Middle East and Africa | Middle East | Saudi Arabia | |
| United Arab Emirates | |||
| Rest of Middle East | |||
| Africa | South Africa | ||
| Rest of Africa | |||
Market Definition
- Application - Various applications or purposes of the satellites are classified into communication, earth observation, space observation, navigation, and others. The purposes listed are those self-reported by the satellite’s operator.
- End User - The primary users or end users of the satellite is described as civil (academic, amateur), commercial, government (meteorological, scientific, etc.), military. Satellites can be multi-use, for both commercial and military applications.
- Launch Vehicle MTOW - The launch vehicle MTOW (maximum take-off weight) means the maximum weight of the launch vehicle during take-off, including the weight of payload, equipment and fuel.
- Orbit Class - The satellite orbits are divided into three broad classes namely GEO, LEO, and MEO. Satellites in elliptical orbits have apogees and perigees that differ significantly from each other and categorized satellite orbits with eccentricity 0.14 and higher as elliptical.
- Propulsion tech - Under this segment, different types of satellite propulsion systems have been classified as electric, liquid-fuel and gas-based propulsion systems.
- Satellite Mass - Under this segment, different types of satellite propulsion systems have been classified as electric, liquid-fuel and gas-based propulsion systems.
- Satellite Subsystem - All the components and subsystems which includes propellants, buses, solar panels, other hardware of satellites are included under this segment.
| Keyword | Definition |
|---|---|
| Attitude Control | The orientation of the satellite relative to the Earth and the sun. |
| INTELSAT | The International Telecommunications Satellite Organization operates a network of satellites for international transmission. |
| Geostationary Earth Orbit (GEO) | Geostationary satellites in Earth orbit 35,786 km (22,282 mi) above the equator in the same direction and at the same speed as the earth rotates on its axis, making them appear fixed in the sky. |
| Low Earth Orbit (LEO) | Low Earth Orbit satellites orbit from 160-2000km above the earth, take approximately 1.5 hours for a full orbit and only cover a portion of the earth’s surface. |
| Medium Earth Orbit (MEO) | MEO satellites are located above LEO and below GEO satellites and typically travel in an elliptical orbit over the North and South Pole or in an equatorial orbit. |
| Very Small Aperture Terminal (VSAT) | Very Small Aperture Terminal is an antenna that is typically less than 3 meters in diameter |
| CubeSat | CubeSat is a class of miniature satellites based on a form factor consisting of 10 cm cubes. CubeSats weigh no more than 2 kg per unit and typically use commercially available components for their construction and electronics. |
| Small Satellite Launch Vehicles (SSLVs) | Small Satellite Launch Vehicle (SSLV) is a three-stage Launch Vehicle configured with three Solid Propulsion Stages and a liquid propulsion-based Velocity Trimming Module (VTM) as a terminal stage |
| Space Mining | Asteroid mining is the hypothesis of extracting material from asteroids and other asteroids, including near-Earth objects. |
| Nano Satellites | Nanosatellites are loosely defined as any satellite weighing less than 10 kilograms. |
| Automatic Identification System (AIS) | Automatic identification system (AIS) is an automatic tracking system used to identify and locate ships by exchanging electronic data with other nearby ships, AIS base stations, and satellites. Satellite AIS (S-AIS) is the term used to describe when a satellite is used to detect AIS signatures. |
| Reusable launch vehicles (RLVs) | Reusable launch vehicle (RLV) means a launch vehicle that is designed to return to Earth substantially intact and therefore may be launched more than one time or that contains vehicle stages that may be recovered by a launch operator for future use in the operation of a substantially similar launch vehicle. |
| Apogee | The point in an elliptical satellite orbit which is farthest from the surface of the earth. Geosynchronous satellites which maintain circular orbits around the earth are first launched into highly elliptical orbits with apogees of 22,237 miles. |
Research Methodology
Mordor Intelligence follows a four-step methodology in all our reports.
- Step-1: Identify Key Variables: In order to build a robust forecasting methodology, the variables and factors identified in Step-1 are tested against available historical market numbers. Through an iterative process, the variables required for market forecast are set and the model is built on the basis of these variables.
- Step-2: Build a Market Model: Market-size estimations for the historical and forecast years have been provided in revenue and volume terms. For sales conversion to volume, the average selling price (ASP) is kept constant throughout the forecast period for each country, and inflation is not a part of the pricing.
- Step-3: Validate and Finalize: In this important step, all market numbers, variables and analyst calls are validated through an extensive network of primary research experts from the market studied. The respondents are selected across levels and functions to generate a holistic picture of the market studied.
- Step-4: Research Outputs: Syndicated Reports, Custom Consulting Assignments, Databases & Subscription Platforms.


