Market Overview
| Study Period | 2021 - 2032 |
|---|---|
| Forecast Data Period | 2027 - 2032 |
| Base Year Market Size (2026) | USD 68.32 Billion |
| Market Size (2027) | USD 73.23 Billion |
| Market Size (2032) | USD 112.40 Billion |
| Growth Rate (2027 - 2032) | 8.95 % |
| Market Concentration | Medium |
Major Players *Disclaimer: Major Players sorted in no particular order Image © Mordor Intelligence. Reuse requires attribution under CC BY 4.0. | |
GCC Waste Management Market Analysis by Mordor Intelligence
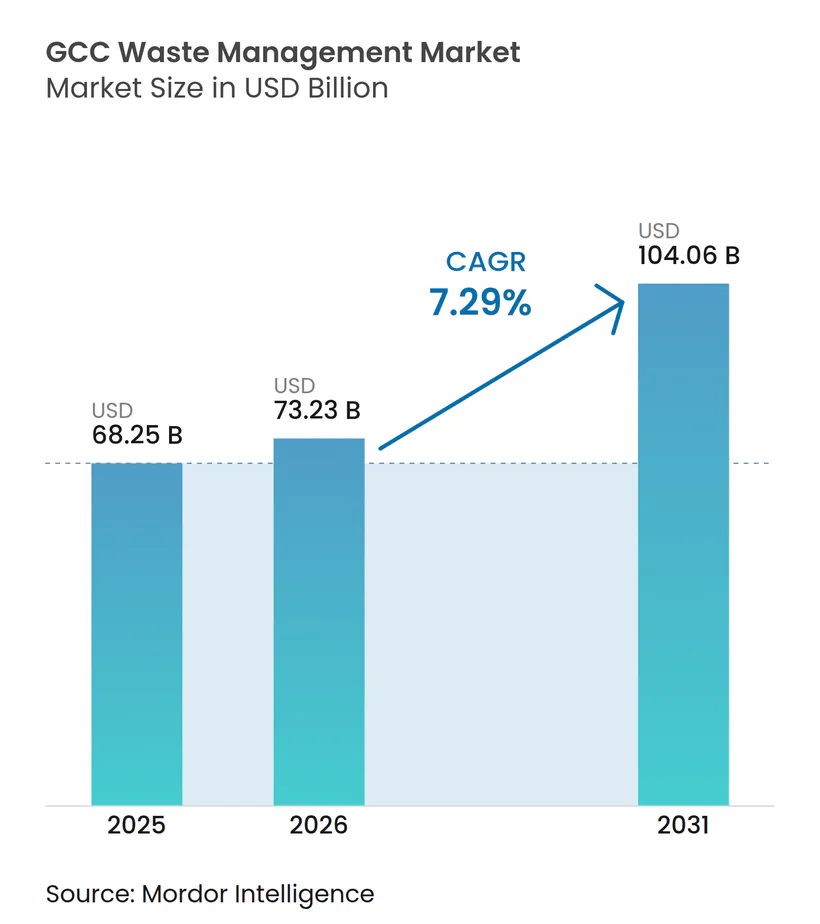
The GCC Waste Management Market size is expected to grow from USD 68.32 billion in 2026 to USD 73.23 billion in 2027 and is forecast to reach USD 112.40 billion by 2032 at 8.95% CAGR over 2027-2032.
Government diversion targets and public investment programs are moving waste services beyond landfill disposal toward collection, sorting, recovery, and energy generation. Waste volumes are increasing as cities expand and as construction, petrochemicals, healthcare, tourism, and hospitality create more varied waste streams. Saudi Arabia provides the largest volume opportunity, while the UAE combines formal policy targets with a more developed base of treatment assets. These conditions favor operators that can combine collection coverage, licensed treatment capacity, digital tracking, and long-term public contracts.
Key Report Takeaways
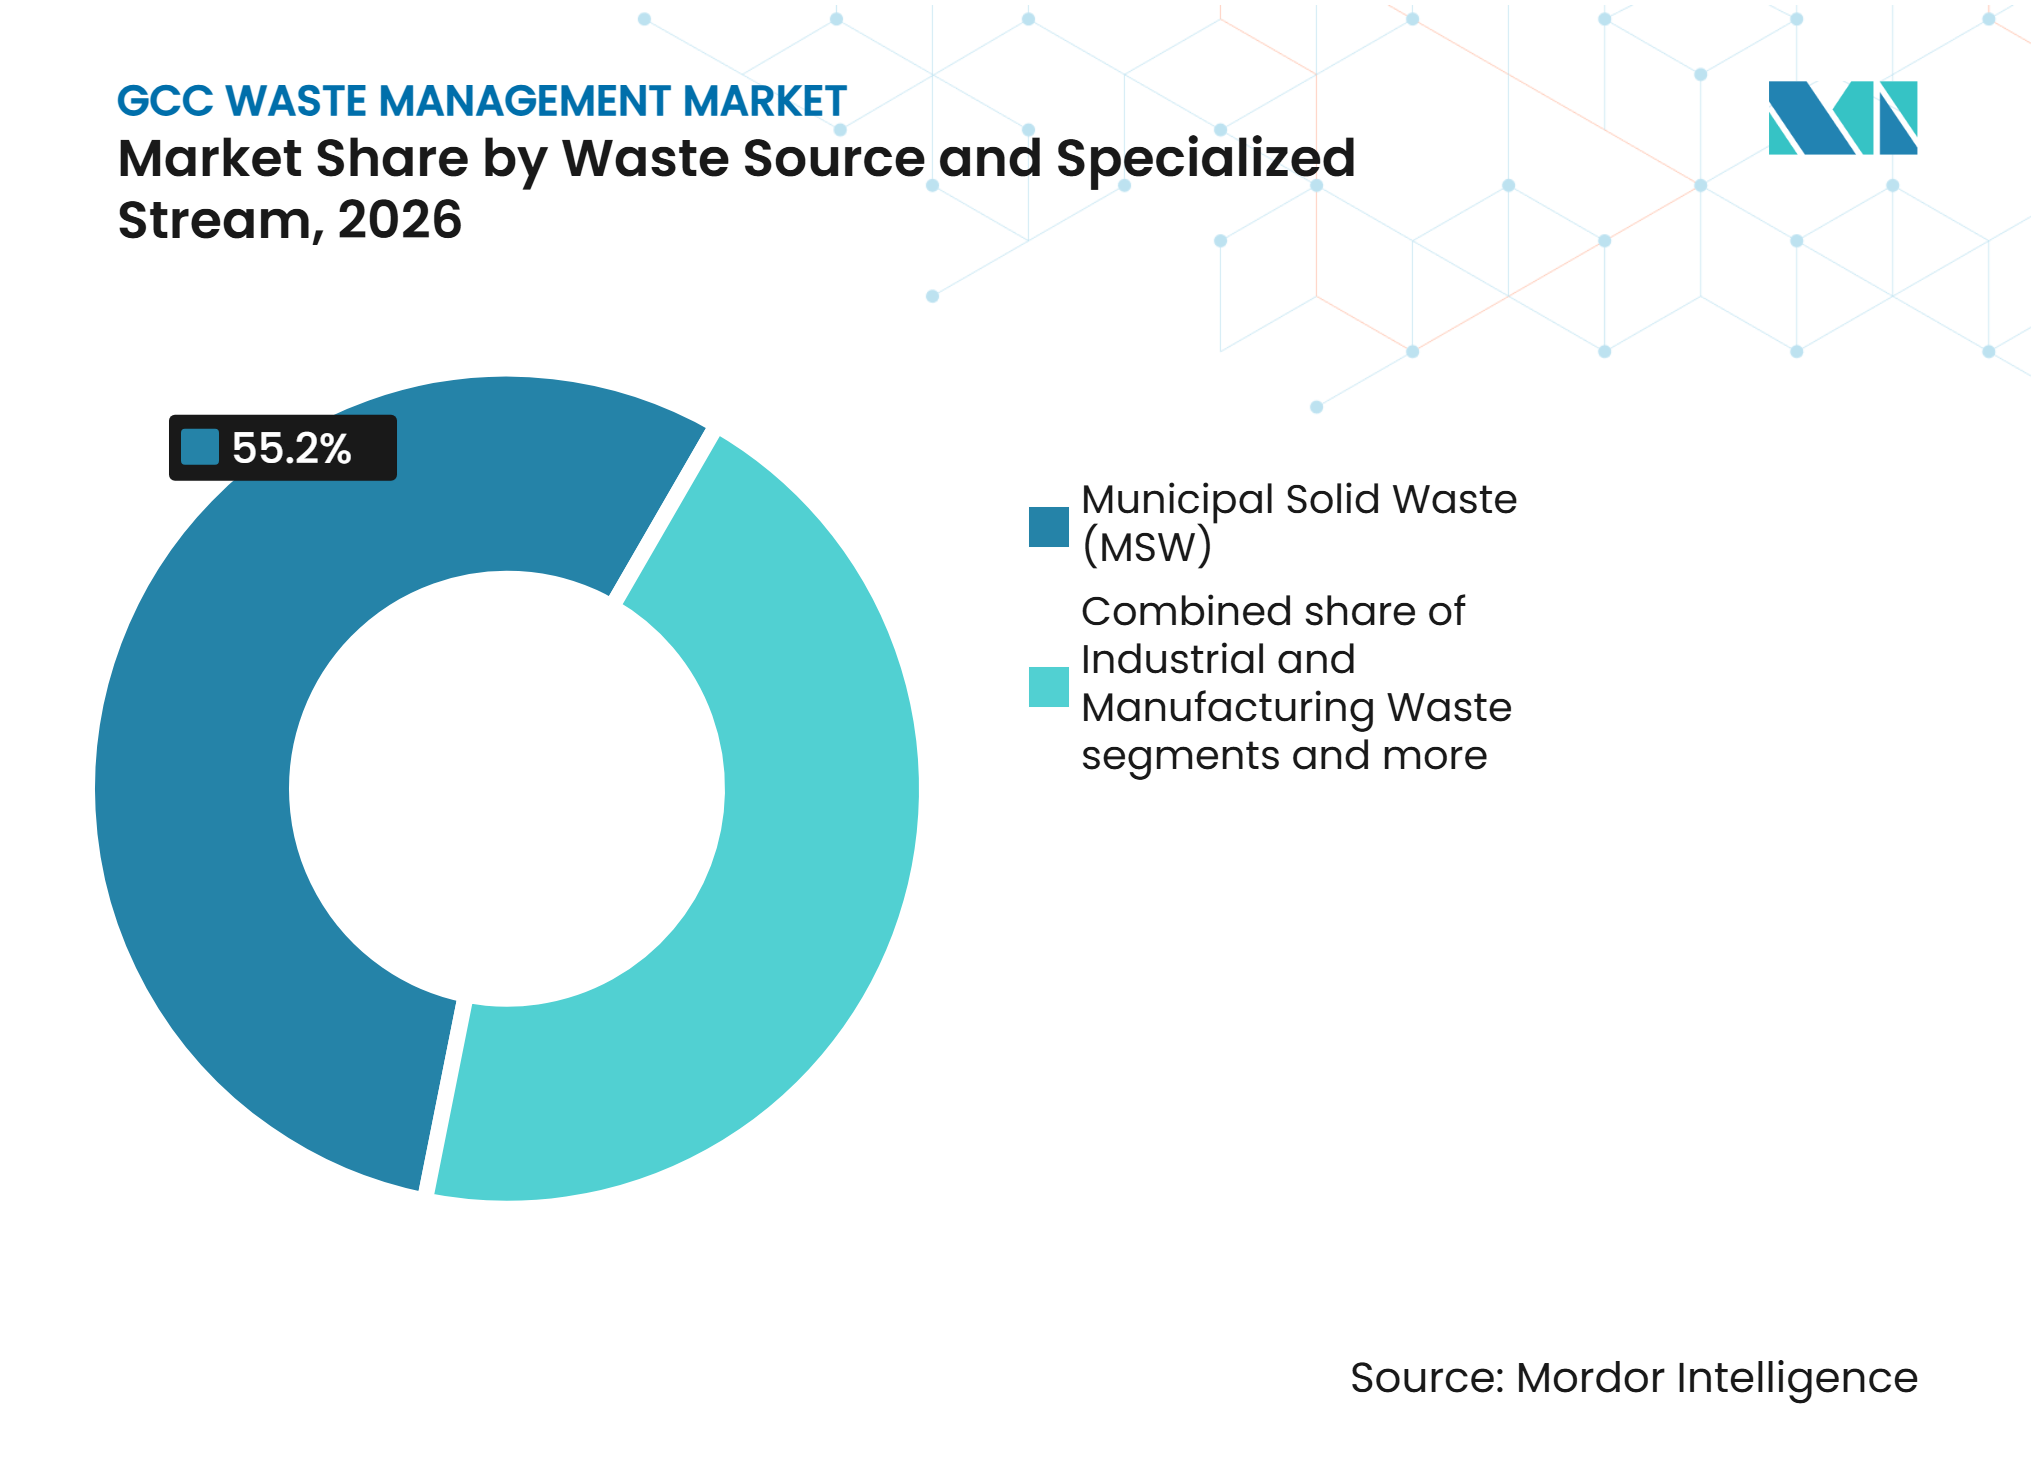
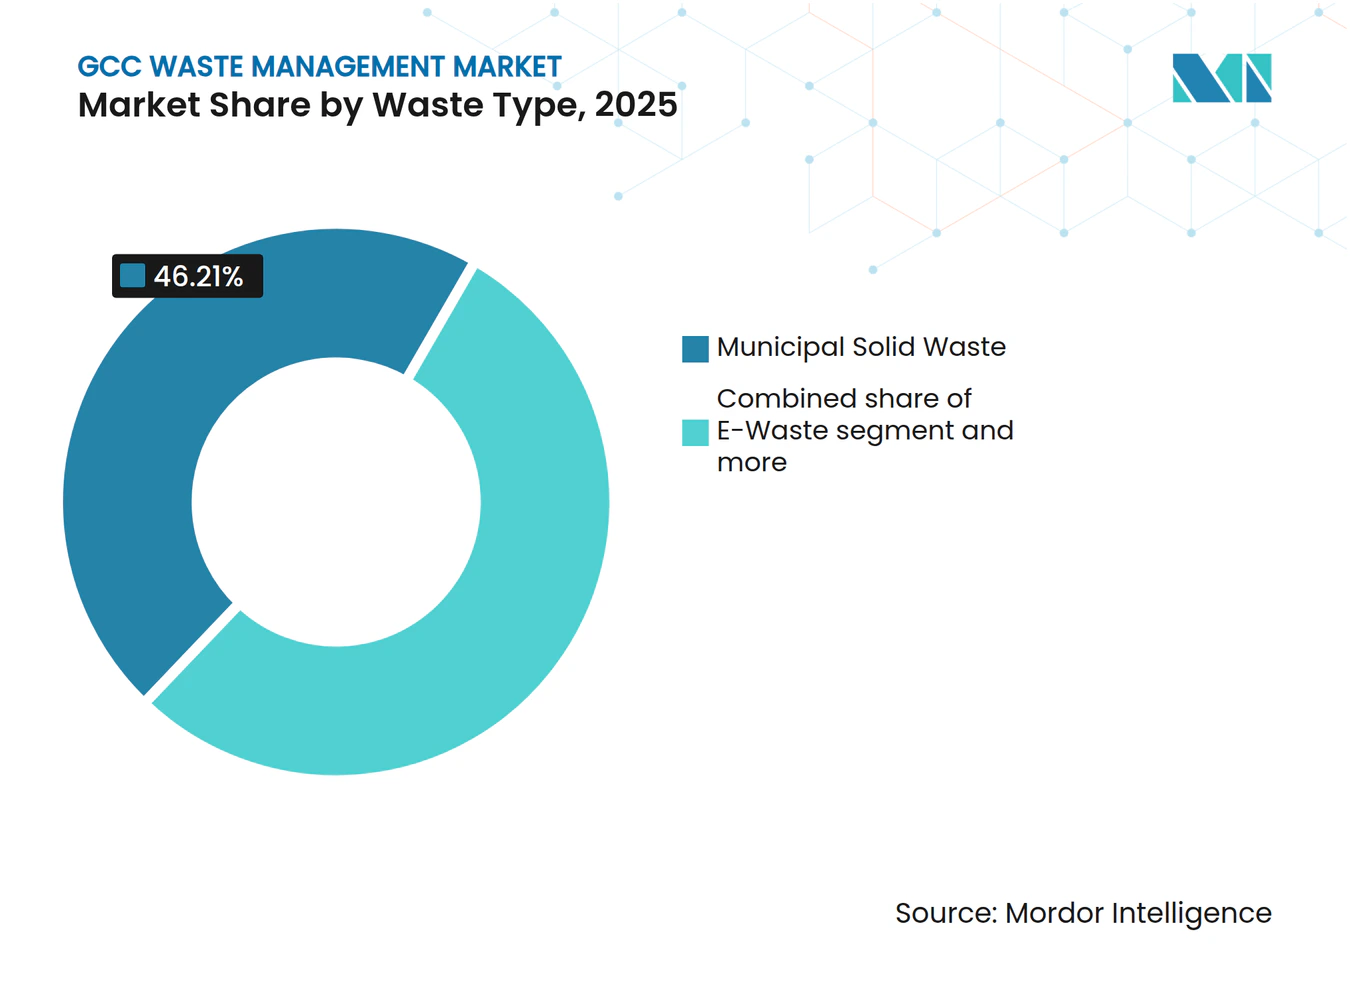
- By waste source and specialized stream, municipal solid waste held 55.2% of the GCC waste management market share in 2026, while industrial and manufacturing waste is projected to grow at a 9.3% CAGR through 2032.
- By service type, disposal/treatment accounted for 52.8% of the GCC waste management market size in 2026, while collection, transportation, sorting, and segregation are expected to expand at a 9.2% CAGR through 2032.
- By waste type, food and organic waste held 48.3% revenue share in 2026, while e-waste is forecast to grow at a 9.5% CAGR through 2032.
- By geography, Saudi Arabia accounted for 42.5% of the GCC waste management market share in 2026, while the United Arab Emirates is forecast to expand at a 9.1% CAGR through 2032.
Note: Market numbers in this report are based on Mordor Intelligence's proprietary estimation framework, which combines nine months of actuals with Q4 projections for base year 2026.
Market Trends and Insights
Drivers Impact Analysis of GCC Waste Management Market*
| Driver | (~) % Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
|---|---|---|---|
| Rising Municipal Waste Generation Across Rapidly Urbanizing GCC Cities | +2.3% | GCC-wide, led by Saudi Arabia and the UAE | Short term (≤ 2 years) |
| Saudi Vision 2030 and National Waste Diversion Targets | +2.0% | Saudi Arabia | Medium term (2-4 years) |
| Expansion of Waste-to-Energy Infrastructure Across Saudi Arabia and the UAE | +1.6% | UAE core markets and Saudi Arabia | Medium term (2-4 years) |
| Growing Construction and Demolition Waste from GCC Mega-Projects | +1.2% | Saudi Arabia and the UAE | Short term (≤ 2 years) |
| Increasing Industrial and Hazardous Waste Treatment Demand Across GCC Industrial Hubs | +0.8% | Saudi Arabia, UAE, and Oman | Medium term (2-4 years) |
| Rising Investments in Integrated Waste Management PPP Projects | +0.5% | GCC-wide, led by the UAE and Saudi Arabia | Long term (≥ 4 years) |
| Source: Mordor Intelligence | |||
Rising Municipal Waste Generation Across Rapidly Urbanizing GCC Cities
The GCC waste management market is supported by a larger and more varied municipal waste stream across rapidly expanding cities. GCC-Stat reported in 2025 that total waste collected in member states reached 262.7 million tons by the end of 2023, with municipal and commercial activities forming a major part of collection demand. Commercial and institutional waste is becoming more important in offices, hotels, public facilities, retail sites, and entertainment venues. These streams are concentrated in major urban areas, yet they require more tailored collection routes and sorting practices than household waste. This gives established collection operators an opportunity to offer services that match the needs of Riyadh, Jeddah, Dubai, and Abu Dhabi. The continued shift toward complex city waste supports demand for service networks that can separate, transport, and direct material to approved recovery or treatment sites.
Saudi Vision 2030 and National Waste Diversion Targets
Saudi Arabia is strengthening the policy basis for long-term investment in the GCC waste management market. The Ministry of Environment, Water and Agriculture has set out a plan that could add more than SAR 120 billion (USD 32 billion) to national GDP and create more than 100,000 jobs through waste-sector development.[1] In November 2025, MWAN began the execution phase of its Comprehensive Strategic Master Plan, which introduced regional cluster solutions, a national waste database, and a 90% landfill-diversion target by 2040.[2] The Yudaim electronic manifest system provides a formal method to track waste transport, while the UADIM program supports circular-economy implementation. MWAN targets include 81% recycling for municipal waste, 60% for construction and demolition waste, and 85% for hazardous industrial waste. Such measures create a clearer pipeline of collection, sorting, composting, recycling, and energy-recovery work for licensed providers.
Expansion of Waste-to-Energy Infrastructure Across Saudi Arabia and the UAE
Waste-to-energy projects are bringing a higher-value treatment option into the GCC waste management market. Dubai’s Warsan Waste-to-Energy Centre operates under a 35-year public-private partnership that required AED 4 billion (USD 1.1 billion) and can process up to 2 million tons of municipal solid waste each year.[3] In January 2025, Emirates Waste to Energy announced that the second phase of the Sharjah plant would increase annual processing capacity from 300,000 tons to 600,000 tons and power output from 30 MW to 60 MW. Saudi Arabia is also pursuing waste-to-energy capacity through SIRC-backed development. Large projects depend on public support and credible offtake arrangements because low landfill prices can otherwise weaken project economics.
Growing Construction and Demolition Waste from GCC Mega-Projects
Construction and demolition activity is expanding the need for dedicated recovery services across the GCC waste management market. Riyadh Municipality reported in July 2025 that demolition waste was being incorporated into asphalt mixtures for road construction, supporting Saudi Arabia’s objective to recycle 60% of construction and demolition waste by 2035. The Dammam recycling facility processed more than 16,000 tons of demolition waste each month and converted more than 70% of incoming material into construction inputs, according to a December 2025 Saudi Press Agency report. SIRC subsidiary Akam received a Guinness World Record for the world’s largest construction and demolition recycling plant by capacity in January 2025. The PIF-led NovusCrete consortium is developing concrete applications that incorporate recycled construction waste and polymer-based materials. Saudi Arabia’s diversion roadmap calls for 9% landfill diversion in 2025, 36% in 2028, and 86% in 2035, creating a gradual need for processing capacity in major cities.
Restraints Impact Analysis of GCC Waste Management Market*
| Restraint | (~) % Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
|---|---|---|---|
| Heavy Dependence on Landfills Across GCC Waste Disposal Systems | -2.2% | GCC-wide, especially Saudi Arabia, Kuwait, and Bahrain | Medium term (2-4 years) |
| High Capital Requirements for Advanced Waste Treatment Infrastructure | -1.8% | GCC-wide, especially Oman, Bahrain, and Kuwait | Long term (≥ 4 years) |
| Limited Source Segregation and Contamination of Recyclable Waste | -1.4% | GCC-wide, especially residential and hospitality generators | Short term (≤ 2 years) |
| High Operating Costs of Waste-to-Energy and Recycling Facilities | -1.0% | Saudi Arabia and smaller GCC states | Medium term (2-4 years) |
| Source: Mordor Intelligence | |||
Heavy Dependence on Landfills Across GCC Waste Disposal Systems
Landfills remain a major outlet for solid waste in the GCC, which limits the rate at which recovery services can expand. The World Future Energy Summit reported in 2025 that more than 85% of regional solid waste was sent to landfill, and recycling remained close to 10%. Qatar, Kuwait, and Bahrain face tighter land availability, making continued landfill use harder to sustain. Saudi Arabia reported an 18% landfill-diversion rate against its 90% target for 2040. Closing the gap requires new facilities, but also dependable collection and sorting systems that can feed those facilities with usable material. Until these systems scale, landfill capacity remains a constraint on the pace of change in the GCC waste management market.
High Capital Requirements for Advanced Waste Treatment Infrastructure
Advanced treatment infrastructure requires substantial investment before it can produce steady operating revenue. Abu Dhabi’s Al Bihouth waste-to-energy facility requires USD 600 million of investment and is planned to process 900,000 tons of waste per year while generating 80 MW to 90 MW. Dubai’s Warsan facility required AED 4 billion (USD 1.1 billion) under its 35-year partnership structure. Tadweer Group’s Abu Dhabi and Al Ain material recovery facilities each have 400,000 tons of annual capacity, requiring multi-year build programs and clear routes to market. Smaller markets may struggle to establish the volume base, public funding, or credit support needed for similar facilities. These conditions can slow the replacement of landfill disposal even when national policy favors recovery.
*Our forecasts treat driver/restraint impacts as directional, not additive. The impact forecasts reflect baseline growth, mix effects, and variable interactions.
GCC Waste Management Market Segment Analysis
By Waste Source and Specialized Stream:
Municipal Streams Lead as Industrial Volumes AccelerateMunicipal solid waste held 55.2% of the GCC waste management market in 2026, supported by household, retail, hospitality, and office waste. Residential waste remains a large part of municipal collection needs, while commercial activity widens the range of material that must be handled. Hotels, restaurants, catering operations, shopping areas, and public facilities create recurring demand for collection and sorting services. The GCC waste management market size for municipal streams is supported by dense urban activity in Dubai, Abu Dhabi, Riyadh, Jeddah, and Doha. Healthcare waste requires more controlled processing than general municipal waste and has moved toward formal treatment capacity. Agricultural waste, end-of-life vehicles, and radioactive sources also need distinct handling systems and regulatory controls. This mix favors operators that can manage several waste categories through one licensed network.
Industrial and manufacturing waste is projected to grow at a 9.3% CAGR through 2032. Demand is tied to chemical production, refining, manufacturing, mining, and related industrial development. Waste from these activities has more demanding transport, treatment, and documentation requirements than general municipal material. Veolia’s Tahwil facility in Jubail provides high-temperature treatment for industrial hazardous waste and recovers heat for nearby industrial users. Saudi industrial centers and Abu Dhabi industrial zones are important locations for this specialist demand. Tighter licensing rules increase the value of approved facilities that can provide secure handling and auditable treatment. The GCC waste management industry is therefore likely to require more specialist capacity as industrial waste volumes expand.



By Service Type:
Disposal Leads by Revenue, While Collection Technology Gains GroundDisposal/treatment accounted for 52.8% of the GCC waste management market size in 2026. The segment includes landfill disposal, recycling, resource recovery, composting, incineration, waste-to-energy, and related treatment activities. Landfill remains a large part of the volume base, but diversion targets are changing the revenue mix toward recovery and energy generation. Operators can earn higher-value revenue when they recover materials or turn waste into fuel and energy rather than only collect and dispose of it. Tadweer Group diverted more than 3.5 million tons from landfill in 2025, reached a 37.7% diversion rate, and increased collected volumes by 4.9%. This performance shows the importance of combining collection operations with recovery assets. Disposal and treatment will remain central as governments make landfill use less acceptable and require other routes.
Collection, transportation, sorting, and segregation are forecast to grow at a 9.2% CAGR through 2032. The segment is shifting from basic truck-led activity to digitally managed service networks. Sensor-equipped containers, route planning, automated monitoring, and live performance data can improve collection efficiency and contract performance. Tadweer Group operationalized its AI-powered Tajmee’e collection and transport subsidiary in 2025. Sorting and segregation also determine whether downstream recycling and treatment plants receive usable material. The services grouped under others, including consulting, audit, and training, have a role as extended producer responsibility and digital tracking requirements become more common. Service providers that can document their performance will be better positioned for public and commercial contracts.
By Waste Type:
Organic Waste Anchors Volume, While E-Waste Leads GrowthFood and organic waste held 48.3% of the GCC waste management market in 2026. Hotels, restaurants, catering facilities, institutional kitchens, and household consumption create a substantial organic waste stream. The UAE completed the nationwide data collection phase of its first National Food Loss and Waste Baseline Study in September 2025, covering households and businesses across all seven emirates. The collected data is being consolidated and validated to establish national food loss and waste indices, with initial findings expected in 2026. The study is intended to support food-waste reduction goals for 2030. Its results can help guide future collection and diversion requirements for hotels and food-service operators. Plastic, chemical, biomedical, rubber, textile, metal, and end-of-life vehicle waste have separate logistics and treatment needs. These specialized streams create a broader base of service requirements across the GCC waste management market.
E-waste is forecast to grow at a 9.5% CAGR through 2032. Saudi Arabia’s CST and MWAN set a target to recycle more than 107,000 tons of electronic products by 2030 and to achieve a 90% e-product recycling rate by 2040. The UAE Ministry of Climate Change and Environment signed a July 2025 pilot agreement with Tadweer Group covering electrical and electronic equipment, batteries, and packaging. These policies place more responsibility on producers and create formal pathways for collection and processing. Battery waste and biomedical waste are smaller by volume, but each requires high-control treatment and can support specialist providers. E-waste recovery is therefore becoming a defined area for operators that can manage materials, compliance, and safe processing.

Geography Analysis
Saudi Arabia
Saudi Arabia held 42.5% of the regional waste management sector in 2026. The country generates more than 110 million tons of waste annually, giving it the largest waste base in the region. MWAN began executing its Comprehensive Strategic Master Plan in November 2025, creating regional clusters and using the Yudaim electronic manifest system for transport compliance. The government also links waste-sector development to SAR 120 billion (USD 32 billion) of planned GDP contribution and more than 100,000 jobs. SIRC supports infrastructure across refuse-derived fuel, tire recycling, construction waste, and medical waste treatment. Saudi Arabia’s 3 GW waste-to-energy objective for 2030 creates a major project pipeline. The scale of this pipeline will depend on continued public support because landfill costs remain low. The GCC waste management market has its largest long-term volume opportunity in Saudi Arabia, particularly in large urban and industrial areas.
United Arab Emirates
The United Arab Emirates is forecast to grow at a 9.1% CAGR through 2032. Its National Agenda for Integrated Waste Management targets treatment of 80% of municipal solid waste and 99% of hazardous waste by 2031. Tadweer Group reported that it diverted more than 3.5 million tons from landfill in 2025 and treated 99.1% of Abu Dhabi’s hazardous waste. New facilities in Al Ain and Abu Dhabi will each offer 400,000 tons of annual material recovery capacity and use AI-enabled sorting. Dubai plans to close all landfills by 2027, which supports demand for treatment and recovery capacity. This regulatory influence and asset base place the United Arab Emirates ahead of other GCC states in formal waste management development.
Smaller Gulf States Pursue Distinct Circular Pathways
Qatar is expanding its Domestic Solid Waste Management Centre in Mesaieed from 2,300 tons to 5,300 tons per day through a private-sector investment opportunity. Qatar News Agency reported in October 2025 that more than 20 million tons of construction waste at Rawdat Rashid had been recycled into certified building materials after the site was taken over in 2020. Oman is preparing its first utility-scale waste-to-energy tender through be’ah’s integrated waste management framework. Kuwait and Bahrain are moving through earlier stages of privatization and formal environmental controls. Kuwait’s Environmental Protection Law No. 42 of 2014 and Bahrain’s Public Cleanliness Law No. 10 of 2019 set licensing and disposal standards for operators. Agricultural waste collection offers an additional opportunity in Oman and Saudi Arabia, where agriculture and livestock have greater economic importance. These markets have smaller waste volumes than those in Saudi Arabia and the UAE, but their policy pathways can still support targeted collection, recycling, and treatment investments.
Regulatory Landscape
Regulation across the GCC is increasingly anchored in national waste laws and emirate-level implementing resolutions that tighten licensing, tracking, and diversion compliance. In the UAE, Federal Law No. (12) of 2018 on Integrated Waste Management provides the overarching framework, while Dubai added a more detailed local layer through Law No. (18) of 2024 on waste management and Administrative Resolution No. (34) of 2026 that operationalizes requirements for regulated waste handling under Dubai Municipality supervision, including controls that extend across private entities and free zones.
Saudi Arabia has formalized governance and technical compliance under its Waste Management Law framework, with the National Center for Waste Management (MWAN/NCWM) and the National Centre for Environmental Compliance (NCEC) central to oversight. In August 2025, Ministerial Decision 25146805 (published in Umm Al-Qura) approved 14 technical standards and guidelines, strengthening standardization for service providers and facility operators. In Abu Dhabi, the Environment Agency Abu Dhabi (EAD) policy framework emphasizes licensed Waste Service Providers and end-to-end auditability, including electronic manifesting and traceable waste movement from collection through transfer and treatment.
Value Chain Analysis
The GCC waste management value chain begins with waste generation (residential, commercial, industrial, medical, and construction and demolition) and proceeds through collection and transport, transfer stations, sorting and segregation, treatment and disposal, and downstream offtake markets for recovered materials and energy. Municipalities and national waste bodies typically set contracting structures and performance requirements, while integrated operators (such as Beeah, Tadweer, and Averda) coordinate multi-stream logistics and invest in sorting and processing assets.
Technology providers and EPC partners enable high-capex steps such as material recovery facilities and waste-to-energy. At the same time, cement plants and industrial corridors provide critical offtake for refuse-derived fuel, linking recovery economics to industrial demand. Key bottlenecks center on feedstock quality and traceability, where limited source segregation constrains yields for advanced recycling and WtE and raises processing costs. Differing local rules also increase compliance complexity for cross-emirate and cross-border movements. The chain is being extended by new recovery nodes and circular-economy projects, including upgrades and new-build MRF capacity (for example, Tadweer-led 400,000-ton-per-year processing capacity projects in Al Ain) and waste conversion pathways under development in the UAE (such as Beeah and partners advancing a Phase 2 expansion of Sharjah WtE to 60 MW). Specialized recycling capacity additions, including Oman-based initiatives that convert historical mining waste into secondary metals, further show how non-municipal streams are feeding new material recovery routes alongside traditional MSW systems.
Competitive Landscape
Market Concentration
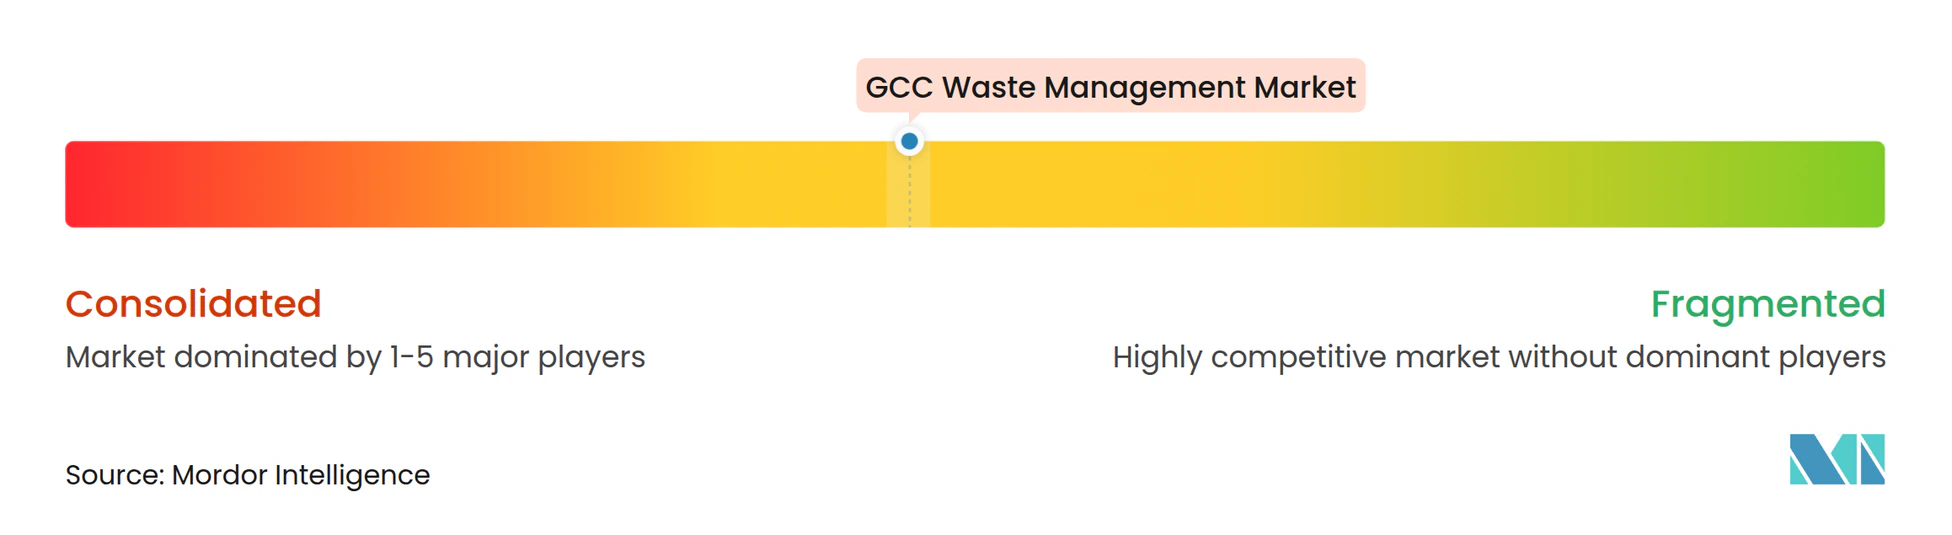
The GCC waste management market exhibits a medium level of market concentration. BEEAH and Tadweer Group hold integrated positions in UAE collection, treatment, recovery, and waste-to-energy activities. Their operating models combine long-term service agreements with technology such as AI-enabled collection systems, material recovery facilities, and energy-recovery assets. Saudi Arabia has a different structure, with SIRC building national recycling and treatment capacity through direct investment and partnerships. International and domestic operators, including Averda, Veolia, SUEZ, and local providers, compete for collection and hazardous waste work under MWAN’s licensing framework. This division creates a role for established operators, government-linked investors, and niche specialists.
Technology is becoming more important in how companies compete in the GCC waste management market. Tadweer’s Tajmee’e operation uses AI-enabled collection and transport tools, while BEEAH has deployed smart bins, autonomous sweepers, sensor-equipped containers, and performance dashboards. These systems can help operators improve route efficiency, document service performance, and meet public contract requirements. In January 2025, Emirates Waste to Energy announced the second phase of the Sharjah plant, which will double processing capacity to 600,000 tons per year and output to 60 MW. In 2025, Tadweer acquired Masdar’s stake in the Sharjah waste-to-energy plant and entered a joint venture with BEEAH. These actions point to greater concentration around integrated asset owners in the UAE.
The GCC waste management market has room for operators in secondary Saudi and Omani cities, industrial hazardous waste treatment, advanced plastic recycling, food-grade resin recovery, organic-to-biogas projects, refuse-derived fuel, and battery recycling. In 2026, BEEAH and KEZAD Group formed a joint venture to provide waste services across Abu Dhabi economic cities and free zones. BEEAH also formed a joint venture with LOHUM and the UAE Ministry of Energy and Infrastructure to develop the UAE’s first EV battery recycling facility. International entrants can benefit from partnering with government-linked entities that provide local project access and regulatory familiarity. Market entry conditions favor companies with capital, technical treatment expertise, and demonstrated compliance capability.
GCC Waste Management Industry Leaders
-
Averda International Limited
-
BEEAH Group
-
Tadweer Group
-
Veolia Middle East
-
EnviroServe
- *Disclaimer: Major Players sorted in no particular order
GCC Waste Management Market Companies Covered in this Report
- Averda International Limited
- BEEAH Group
- Tadweer Group
- Veolia Middle East
- EnviroServe
- SEPCO Environment
- Saudi Investment Recycling Company (SIRC)
- Wasco
- Dulsco Waste Management Services
- Green Mountains
- Blue LLC
- Envac Middle East
- Power Waste Management & Transport LLC
- Al Haya Enviro
- United Waste Management Company
- Kuwait Waste Collection & Recycling Company
- Oman Environmental Services Holding Company
- Bin-Ovations
- Sharaf DG Recycling
Market Opportunities and Future Outlook
Digitization and compliance-led transparency are creating a concrete procurement and solution space across the GCC, with Saudi Arabia leading the push. In April 2026, MWAN launched the Expression of Interest stage for a National Digital Waste Management Platform under an 11-year DBFOMT PPP, structured around core applications and functional modules that cover e-manifesting, regulatory reporting, and smart-contract-style workflows. By June 2026, the project had attracted expressions of interest from 123 companies, indicating active interest from vendors and operators focused on data platforms, tracking, and compliance automation that can be integrated into collection, transfer, and treatment contracts.
Large-scale treatment capacity expansion and localized infrastructure upgrades are also creating whitespace in midstream sorting and thermal treatment integration, including capacity for specialized hazardous and medical streams. Dubai Municipality announced the Phase 2 expansion for the Warsan Waste-to-Energy Centre in February 2026, while Sharjah’s waste-to-energy facility reported processing 1 million tonnes of waste since 2022 and is advancing Phase 2 to increase capacity (including 60 MW and 600,000 tonnes per year). On medical waste, the Saudi Ministry of Health awarding a SAR 41 million medical waste management project in May 2026 points to continued tender activity tied to compliance-sensitive streams, supporting demand for licensed treatment capacity, traceable logistics, and audit-ready service models.
Recent Industry Developments in GCC Waste Management Market
- October 2026: Tadweer Group commenced on-site works at a new Material Recovery Facility in Abu Dhabi with a processing capacity of 400,000 tons per year. The facility, equipped with AI-enabled sorting and advanced optical technologies, is scheduled for commercial operation in Q2 2028 and will process 200,000 tons of MSW and 200,000 tons of commercial and industrial waste annually.
- April 2026: The Sharjah Waste-to-Energy Facility has processed one million tons of waste since its inauguration. The plant operates at 93% uptime, generates 30 MW of electricity, and displaces 450,000 tons of CO₂ annually.
- January 2026: BEEAH and Khalifa Economic Zones Abu Dhabi formed a joint venture to deliver integrated waste management services across KEZAD’s economic cities and free zones in Abu Dhabi.
GCC Waste Management Market Report Scope and Research Methodology
Market Definition and Coverage
This market covers the revenues generated from managing waste across GCC countries, starting from collection and transport and going through sorting, treatment, recycling, and final disposal, as these services are paid for by municipalities, businesses, and institutions.
Scope exclusions: Informal, unpaid self-disposal and the value of recovered materials sold as standalone commodities are excluded where they cannot be tied back to waste management service revenues.
Segments Covered in This Report
- Market Segmentation, Forecast, and Trends by Waste Source and Specialized Stream
- Municipal Solid Waste (MSW)
- Residential Waste (Households and Residential Communities)
- Commercial Waste (Retail, Offices, Hospitality, etc.)
- Institutional and Other Municipal Waste (Educational Institutions, Government Facilities, Public Spaces, etc.)
- Industrial and Manufacturing Waste
- Industrial Hazardous Waste
- Industrial Non-Hazardous Process Waste
- Healthcare and Pharmaceutical Waste (Hospitals, Clinics, Research Laboratories, Pharmaceutical Manufacturing, etc.)
- Hazardous Healthcare and Pharmaceutical Waste
- Non-Hazardous Healthcare and Pharmaceutical Process Waste
- Construction and Demolition (C&D) Waste
- Hazardous C&D Waste
- Non-Hazardous C&D Waste
- Agricultural and Livestock Waste
- Crop and Agricultural Residues
- Other Agricultural Waste (Livestock and Animal Waste, etc.)
- Other Specialized Waste Streams (EOL Vehicles, Radioactive Sources, etc.)
- Municipal Solid Waste (MSW)
- Market Segmentation, Forecast, and Trends by Service Type
- Collection, Transportation, Sorting & Segregation
- Disposal / Treatment
- Landfill
- Recycling & Resource Recovery
- Incineration & Waste-to-Energy
- Others (Chemical Treatment, Composting, etc.)
- Others (Consulting, Audit & Training, etc.)
- Market Segmentation, Forecast, and Trends by Waste Type
- Plastic Waste
- Chemical Waste and Hazardous Residues (Solvents, Oils, Contaminated Materials, Sludges, etc.)
- Electronic Waste (E-Waste)
- Biomedical and Infectious Waste
- Battery Waste
- Rubber and Tire Waste
- Food and Organic Waste
- Textile and Leather Waste
- Metal Waste (Ferrous and Non-Ferrous)
- End-of-Life Vehicles (Excluding Separately Classified Tires and Batteries)
- Other Waste Types (Wood and Timber Waste, Glass Waste, Paper and Cardboard Waste, Mineral and Inert Waste such as Bricks and Ceramics, Radioactive, Unclassified Waste)
- Market Segmentation, Forecast, and Trends by Geography
- Saudi Arabia
- United Arab Emirates
- Qatar
- Oman
- Kuwait
- Bahrain
Data Sources, Market Sizing, and Validation
Desk Research
Desk work starts with building the demand context and policy reality for the GCC, since waste volumes and mandated diversion targets shape spending on collection, treatment, and disposal. We refer to public sources such as national statistics offices and environment ministries in GCC countries, municipal portals, regional policy publications, and international bodies such as the World Bank and UN agencies for solid waste baselines and definitions.
Next, the operating side is mapped using sources like government tenders and procurement notices, regulator and ministry updates on landfill, recycling, and waste-to-energy programs, and company annual reports and investor presentations for service mix and capacity clues. Patent databases are also checked to understand the pace of adoption for sorting, treatment, and recycling technologies, because that timing can change cost and pricing assumptions over the forecast horizon. The sources listed here are illustrative only, and many other public references were used to collect data, cross-check assumptions, and clarify open points.
Primary Interviews and Surveys
We interview municipal officials, contractors, recyclers, treatment operators, and industrial waste buyers across the six GCC countries. Their input helps test fee levels, collection coverage, facility utilization, project timing, and gaps in country data. Surveys provide additional detail on waste volumes and service preferences, while unusual responses are checked against desk evidence before the final GCC model is triangulated.
Distribution of primary research fieldwork respondents
| Company type | Respondent position |
|---|---|
| Top tier: 25% | CXOs: 18% |
| Mid tier: 55% | Functional/Unit leaders: 32% |
| Smaller Players: 20% | Managers: 50% |
Market-Sizing & Forecasting
The core model is built using a top-down approach where population and urbanization patterns, per-capita waste generation, and country-level diversion and treatment pathways are used to reconstruct the payable waste management demand pool across the GCC. Once the waste stream is shaped, it is translated into value using service price ranges observed in tenders and contracts, and then it is split across collection, sorting, recycling, treatment, and disposal activities.
To keep the totals realistic, we corroborate with selective bottom-up checks, such as sampling facility capacities for landfills, recycling lines, and waste-to-energy plants, followed by utilization and average fee assumptions that can be defended in interviews. Practical inputs that move the forecast include municipal and industrial waste growth, construction and demolition activity, landfill gate fees and hauling charges, recycling offtake economics, and the timing of new processing capacity additions. For forecasting, scenario analysis is used with a base case anchored to policy execution speed and procurement timelines, and the variable paths are tested with interview feedback before finalizing the curve. Where bottom-up data is missing for smaller cities or where informal handling is difficult to quantify, gaps are handled through penetration assumptions that are adjusted only after country-level checks are completed.
Data Validation & Update Cycle
Outputs are checked against independent signals such as reported waste volumes, announced diversion targets, tendered project pipelines, and the implied revenue per ton to flag values that do not make operational sense. If a variance looks material, the assumptions are reopened, and clarifying calls are triggered so the same datapoint is not carried forward by mistake.
Before sign-off, the model goes through stepwise internal review where calculations, units, and currency conversions are rechecked, and then the narrative is matched back to the numbers. Reports are refreshed annually, and interim updates are made when material events occur, such as major PPP awards, policy resets, or large capacity start-ups. Right before delivery, a final pass is done so clients receive the most current view available at that time.
Mordor Intelligence's Gcc Waste Management Market Size Measured Against Other Published Estimates
Published market sizes for GCC waste management do not always match, even when the topic name looks identical, because analysts often apply different service boundaries and different years for base values. The biggest swings usually come from what is counted as paid waste management activity, how recycling and treatment revenues are treated, and the time window used for inflation and currency conversions.
Tender pricing signals and country-level waste volume checks are the anchors used in Mordor Intelligence's estimate. Once these are applied consistently across collection, sorting, recycling, treatment, and disposal, adjacent but non-service value is screened out. In other publications, the spread can also come from longer forecast windows that assume aggressive policy delivery, or from mixing municipal and industrial pathways without validating capture rates and utilization for new capacity.
Benchmark comparison
| Source | Market Size | Gaps in Research Methodology |
|---|---|---|
| Mordor Intelligence | USD 68.25 B (2025) | |
| Global Consultancy A | USD 70.97 B (2025) | The scope description on the public summary is less explicit on how recycling and disposal revenues are separated from material value, and the CAGR period runs longer, which can shift the base-year normalization and implied price progression. |
| Regional Research Group B | USD 66.10 B (2024) | Uses a different base year and a longer forecast window, and the public outline does not clarify how service revenues are mapped across GCC countries when waste capture rates and formalization levels vary by location. |
Across the three figures, the gap is not large in absolute terms, but it is explainable once you line up base years, what counts as service revenue, and how quickly policy-led diversion is assumed to translate into paying volumes. Our approach stays traceable to observable waste volumes, capacity reality, and contract price signals, which helps keep the final number practical for planning and budgeting.
Key Questions Answered in the Report
What is the projected growth rate for GCC waste management services?
The sector is forecast to grow at an 8.95% CAGR from 2027 to 2032, reaching USD 112.4 billion by 2032.
Which GCC country has the largest waste services opportunity?
Saudi Arabia held 42.5% share in 2026 and has the region’s largest waste generation base, exceeding 110 million tons annually.
Which waste stream is expected to grow fastest in the GCC?
Industrial and manufacturing waste is forecast to grow at a 9.3% CAGR through 2032, supported by industrial activity and stricter treatment requirements.
What service category is growing most rapidly?
Collection, transportation, sorting, and segregation is projected to grow at a 9.2% CAGR through 2032 as cities upgrade collection and tracking systems.
Why is e-waste becoming more important in GCC countries?
E-waste is forecast to grow at an 9.5% CAGR through 2032, supported by Saudi recycling targets and the UAE’s extended producer responsibility pilot.
What factors limit the expansion of treatment facilities?
Landfill dependence, low source segregation, and the major capital and operating needs of recovery and waste-to-energy facilities remain key constraints.