
Functional Beverage Market Analysis by Mordor Intelligence
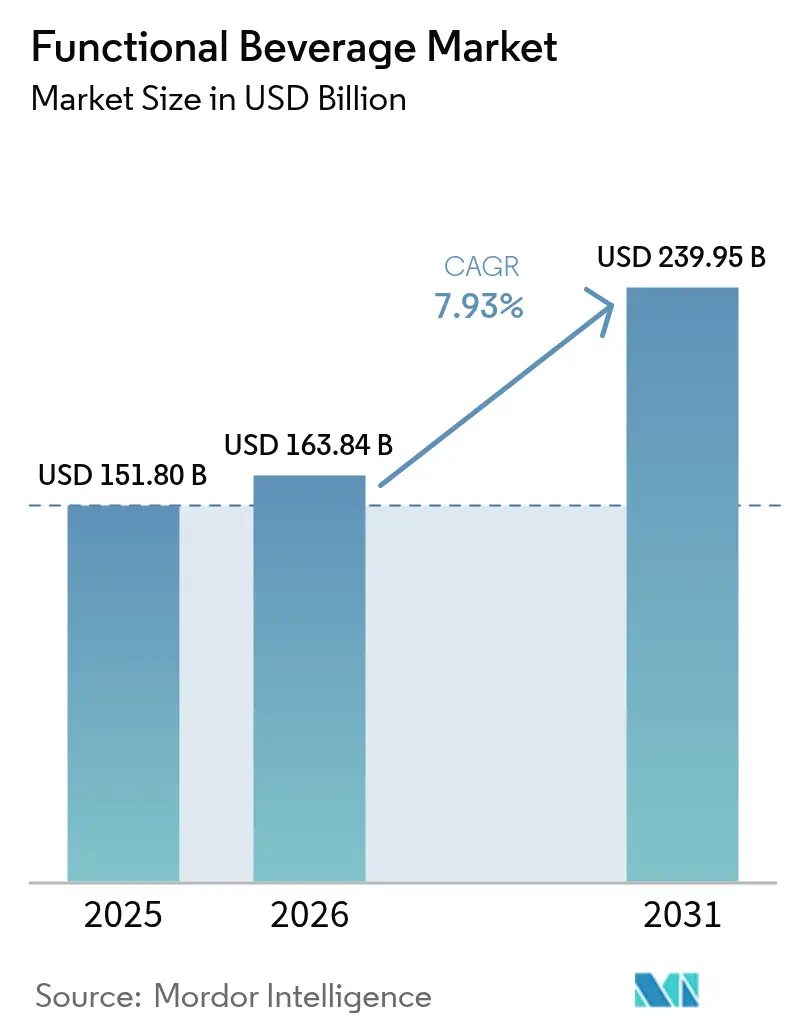
The functional beverage market size is expected to increase from USD 163.8 billion in 2026 to USD 176.8 billion in 2027 and reach USD 255.3 billion by 2032, growing at a CAGR of 7.62% over 2027-2032.
In the United States, wellness demand is bringing functional ingredients into familiar formats such as fiber-added cola. Portfolio acquisition gives a large beverage supplier a route to add a specialist proposition alongside reformulation within existing brands. Label restrictions in India can interrupt replenishment, while packaging fees in the United Kingdom add a separate cost to drinks sold in household packaging. The growth opportunity therefore depends on making added benefits meaningful at retail and in foodservice without allowing compliance or packaging costs to absorb their commercial value.
Key Report Takeaways
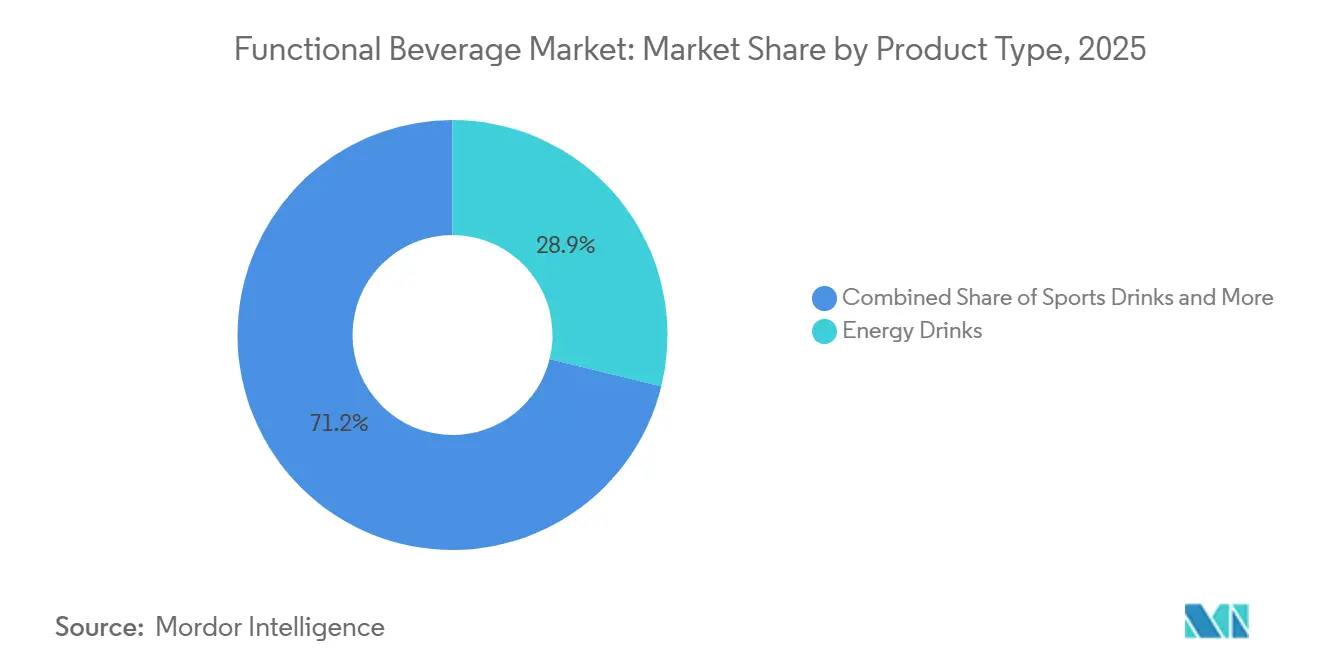
- By product type, energy drinks held a 28.77% functional beverage market share in 2026, while sports drinks are forecast to grow fastest at a CAGR of 8.11% over 2027-2032.
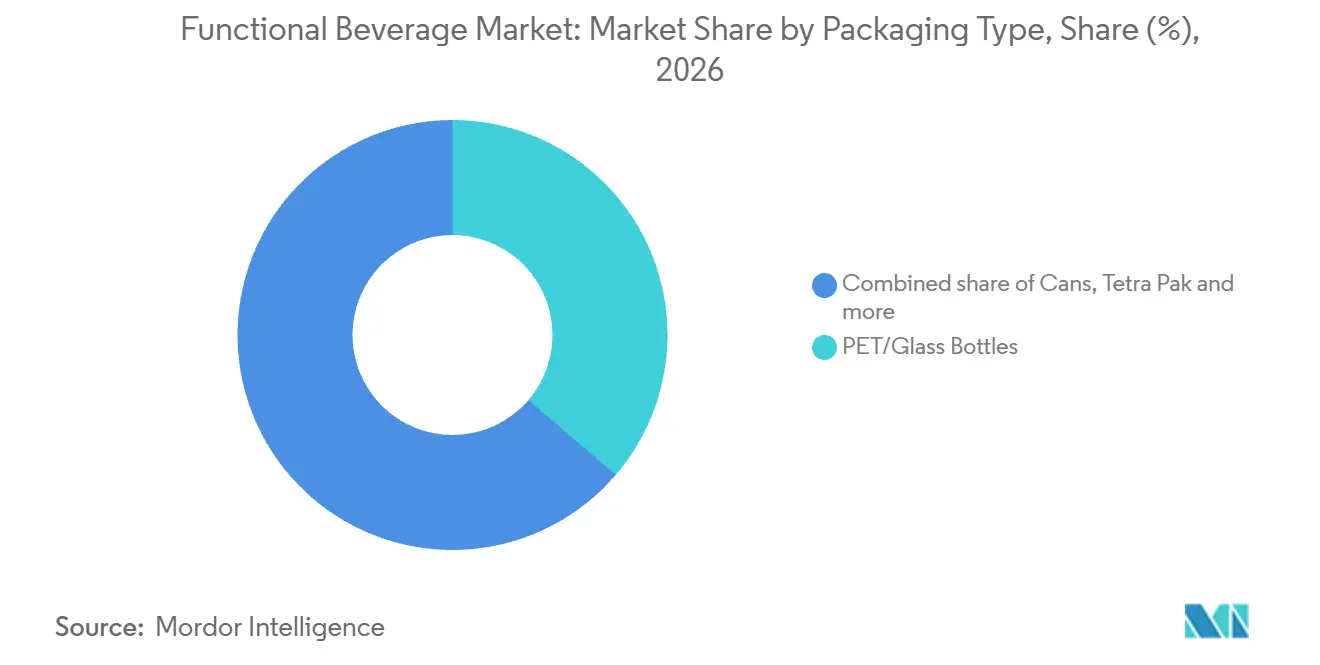
- In packaging, PET/glass bottles accounted for a 36.27% share of the functional beverage market size in 2026, with cans projected to grow fastest at a CAGR of 8.54% over 2027-2032.
- Across distribution channels, off-trade led with 54.65% of spending in 2026, whereas on-trade is forecast to grow fastest at a CAGR of 8.57% over 2027-2032.
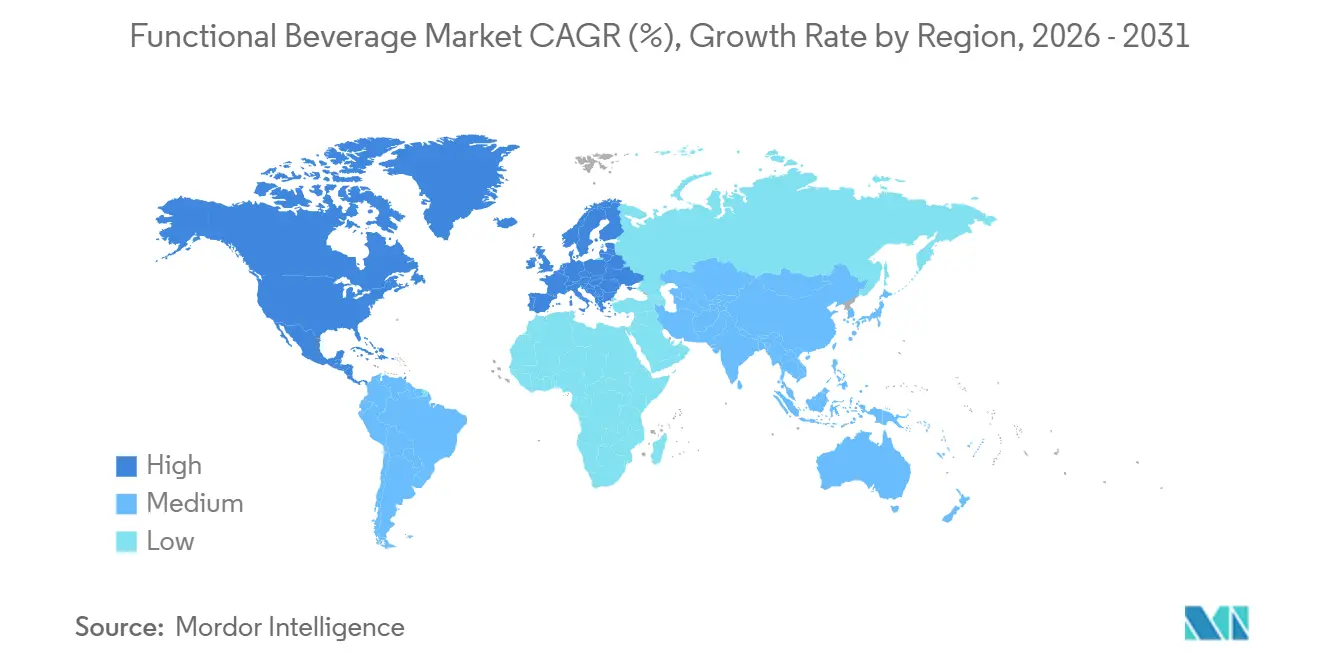
- Geographically, North America held the largest share at 38.82% in 2026, and Asia-Pacific is projected to grow fastest at a CAGR of 8.2% over 2027-2032.
Note: Market numbers in this report are based on Mordor Intelligence's proprietary estimation framework, which combines nine months of actuals with Q4 projections for base year 2026.
Market Trends and Insights
Drivers Impact Analysis of Functional Beverage Market*
| Driver | (~) % Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
|---|---|---|---|
| Increasing Consumer Focus on Health and Wellness | +3% | Across the United States | Medium term (2-4 years) |
| Demand for Clean Label and Natural Ingredients | +1.8% | Moscow area of Russia | Medium term (2-4 years) |
| Growing Awareness of Gut Health and Microbiome | +2.4% | Across the United States | Medium term (2-4 years) |
| Innovation in Ingredients and Formulations | +1.5% | Across the United States | Short term (≤ 2 years) |
| Sustainability and Ethical Sourcing Focus | +0.7% | Petrolina area in Brazil | Long term (≥ 4 years) |
| Personalization and Targeted Functional Benefits | +0.6% | Across the United States | Medium term (2-4 years) |
| Source: Mordor Intelligence | |||
Increasing Consumer Focus on Health and Wellness
Health-oriented demand gives beverage suppliers 2 commercial openings, recurring consumption and the possibility of a premium for a relevant benefit. In EY’s November 20 to December 11, 2025, survey, 65% of US respondents reported drinking functional beverages at least every 2 weeks.[1] In the same survey, 52% said they were willing to pay more for drinks supporting health and wellness goals. Together, these findings support differentiation around the benefit a drink offers within an established consumption routine. A premium proposition consequently needs a recognizable health purpose, which gives suppliers a reason to state the benefit plainly.
Demand for Clean Label and Natural Ingredients
Ingredient naturalness can support demand by reassuring buyers about a health-positioned drink, while other attributes help determine its appeal. In a June to July 2025 online survey of 144 Moscow adults, 71% identified ingredients and naturalness as a leading choice factor for soft drinks positioned as healthy. Taste ranked higher at 80%, while functional effect was selected by 51%. The authors found that composition mainly removed consumer doubts rather than prompted a choice. Clearing ingredient doubts leaves taste and a recognizable functional benefit to secure the drink’s appeal.
Growing Awareness of Gut Health and Microbiome
In the United States, gut-health positioning gives beverage producers a widely recognized personal priority to address, while use of specifically marketed functional products is narrower. The International Food Information Council (IFIC) found that US interest in gut-health benefits from foods, beverages and nutrients increased by 6 percentage points from 2022 to 2026.[2] Its separate 2026 survey found that 64% of US adults rated personal gut health a high or extremely high priority. Yet 13% reported using functional foods or beverages marketed for gut health during the 12 months before the May 2026 survey. Digestive-health drinks have room to recruit users by connecting a familiar priority to a specific beverage choice.
Innovation in Ingredients and Formulations
Adding functional ingredients to a familiar beverage can broaden demand without requiring consumers to adopt a different drinking occasion. PepsiCo launched Pepsi Prebiotic Cola nationwide in the United States in February 2026 with 3 grams of prebiotic fiber per can. PepsiCo identified Pepsi as the first legacy cola brand to introduce prebiotic fiber. The launch placed single cans and multipacks in the carbonated soft drink aisle at retailers and online. That combination gives the functional proposition a route into ordinary cola shopping, rather than relying entirely on specialist nutrition outlets. For formulation suppliers, the commercial opening extends to adapting familiar refreshment products around an additional nutritional benefit.
Restraints Impact Analysis of Functional Beverage Market*
| Restraint | (~) % Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
|---|---|---|---|
| Stringent Regulatory and Labeling Requirements | -0.9% | Nationwide across India | Short term (≤ 2 years) |
| Packaging and Sustainability Challenges | -0.7% | Across the United Kingdom | Medium term (2-4 years) |
| Taste and Consumer Palatability Challenges | -0.5% | Across the United States | Medium term (2-4 years) |
| High Production and Ingredient Costs | -0.3% | United States Midwest | Short term (≤ 2 years) |
| Source: Mordor Intelligence | |||
Stringent Regulatory and Labeling Requirements
Restrictions on a beverage’s label can interrupt availability even when the formulation itself is not the disputed issue. In July 2026, a 90-day labeling deadline from the Food Safety and Standards Authority of India (FSSAI) prompted distributors nationwide to reject existing energy-drink stocks, contributing to retail shortages of dozens of brands. On October 15, PepsiCo told the Delhi High Court that its Indian energy drinks could run out nationwide within 2 months while new production under the “energy drink” label remained barred. The court had not ruled on the merits, with another hearing set for October 30, 2026. For affected suppliers, labeling therefore reaches beyond communication into the ability to replenish saleable stock. PepsiCo’s unresolved manufacturing restriction left product availability exposed while the dispute continued.
Packaging and Sustainability Challenges
Packaging obligations can erode the return on a premium formulation before a functional drink reaches the consumer. In the United Kingdom, affected packaging suppliers and importers must register, report packaging data and pay registration fees. Large organizations also face recycling obligations and, since October 2025, disposal fees for qualifying household or commonly binned packaging and glass household drinks containers. These duties make packaging selection a recurring commercial decision rather than simply a choice about appearance. For a beverage supplier, a higher selling price must cover the formulation alongside applicable packaging charges and administration. Differentiation through ingredients therefore leaves a separate cost exposure that product performance alone cannot remove.
*Our forecasts treat driver/restraint impacts as directional, not additive. The impact forecasts reflect baseline growth, mix effects, and variable interactions.
Functional Beverage Market Segment Analysis
By Product Type:
Brand Scale Meets Formulation DifferentiationEnergy drinks accounted for a 28.77% share of the functional beverage market size in 2026, making them the largest segment. Monster Beverage’s Monster Energy Drinks segment reported USD 7.67 billion in net sales in 2025. That company segment primarily included Monster, Reign Total Body Fuel, Reign Storm and Bang Energy drinks. Reporting these franchises together in one segment shows a single owner building its energy-drink sales across several named lines.
Sports drinks are the fastest-growing segment, with a forecast CAGR of 8.11% over 2027-2032. Gatorade recorded North American volume growth in PepsiCo’s Q3 2026 results, covering the 12 weeks ended September 5, 2026. Gatorade Lower Sugar and Gatorlyte each gained value and volume share during that period. Lower Sugar’s formulation contained no artificial flavors, sweeteners or colors, giving the sports-drink proposition a specific ingredient profile alongside hydration. The gains by Lower Sugar and Gatorlyte show how formulation variants can contribute to expansion within an established sports-drink franchise.

By Packaging Type:
Established Bottles Face Uneven Can ExpansionPET/glass bottles represented a 36.27% functional beverage market share in 2026, making them the largest segment. Across the Coca-Cola system’s broader beverage portfolio, non-refillable PET bottles accounted for 48% of global packaging mix by units in 2025. A functional drink in non-refillable PET can therefore use a format already established across the Coca-Cola system’s owned and independent bottling partners.
Cans are the fastest-growing segment, with a forecast CAGR of 8.54% over 2027-2032. Crown Holdings reported 5% global beverage-can volume growth in Q2 2026 across its broader alcoholic and non-alcoholic beverage business. Double-digit gains in Asia, 7% in Europe and 5% in North America more than offset softer demand in Latin America. A can supplier allocating capacity between Asia and Latin America would therefore face contrasting regional demand signals.
By Distribution Channel:
Retail Scale Meets Restaurant Menu ExpansionOff-trade was the largest segment, accounting for 54.65% of spending in 2026. PepsiCo reported estimated 2025 retail sales of nearly USD 745 million for poppi, its prebiotic soda, up more than 45% from 2024. Propel, its enhanced-water brand, exceeded USD 1 billion in estimated annual retail sales in 2025, more than doubling its 2019 level. Together, a prebiotic soda and an enhanced-water brand show retail supporting 2 separate large functional propositions at once.
On-trade is the fastest-growing segment, with a forecast CAGR of 8.57% over 2027-2032. SpotOn’s US independent-restaurant menu data showed 41% more functional non-alcoholic beverage additions in January 2026 than in January 2025. Functional drinks represented 17.8% of non-alcoholic menu additions in its sample from January 1, 2025, through February 15, 2026. SpotOn identified functional items by menu phrases such as adaptogenic, immunity, probiotic and prebiotic. For beverage suppliers, menu naming offers a way to communicate a functional purpose at the point of ordering.
Geography Analysis
North America Functional Beverage Market
North America held a 38.82% share of the functional beverage market size in 2026. Celsius Holdings reported USD 2.42 billion in North American company revenue in 2025. Alani Nu’s sales in tracked US ready-to-drink energy retail channels rose 55.7% year over year in the 13 weeks ended June 28, 2026. Celsius, which owns Alani Nu, attributed that growth to innovation, expanded distribution and continued adoption by new consumers, showing retail access and new buyers adding demand for that brand.
Asia-Pacific Functional Beverage Market
Asia-Pacific is the fastest-growing region, with a forecast CAGR of 8.2% over 2027-2032. Otsuka Pharmaceutical launched POCARI SWEAT retail sales in India in July 2025 through Otsuka Nutraceutical India Private Limited, using products manufactured by its Indonesian subsidiary, PT Amerta Indah Otsuka. Otsuka linked Indian demand to extreme heatwaves and a growing need for beverages that support hydration and electrolyte replenishment. The Coca-Cola Company reported 8% unit case volume growth across its Asia Pacific portfolio in the second quarter of 2026. Otsuka’s hydration launch entered a region where a major beverage system subsequently reported volume growth.
Europe, South America and Middle East and Africa show different commercial paths through individual bottlers’ functional beverage portfolios. In Spain, Coca-Cola Europacific Partners linked its 2025 company-wide sports-drink volume growth to Aquarius, supported by the Red Peach variant launched at the start of the year. In Brazil, Coca-Cola FEMSA reported sustained 2025 demand for energy and sports drinks within its own portfolio. Coca-Cola HBC reported double-digit energy-drink volume growth in Nigeria in 2025, driven by Predator. A supplier serving these regions faces different entry tasks, from refreshing an established sports brand in Spain to securing a role in an energy-led bottler portfolio in Nigeria.
Regulatory Framework and Outlook
The comparison evaluates selected jurisdictions from the perspective of manufacturers selling packaged functional drinks into retail and foodservice, including energy beverages. Ratings weigh the label, claim and product requirements affecting that participant’s commercial flexibility. The US proposal for a front-of-package Nutrition Info box would cover most packaged foods required to bear Nutrition Facts labels. Proposed compliance would follow a future final rule’s effective date by 3 years for businesses with at least USD 10 million in annual food sales, and 4 years for smaller businesses.
Regulatory Table of Functional Beverage Market
| Decision factor | United States | Brazil | Germany | China | Saudi Arabia |
|---|---|---|---|---|---|
| Primary authority | Food and Drug Administration | Anvisa | Competent state food-control authorities | State Administration for Market Regulation and county-level-or-higher local regulators under the March 2027 rules | Saudi Food and Drug Authority |
| Key instruments or direction | 21 CFR 101.9 and 101.14; proposed front-of-package Nutrition Info box | Nutrition-labeling rules; proposed packaged-food nutrition-label revision | Regulations (EU) No. 1169/2011 and (EC) No. 1924/2006; national energy-drink ordinance | Pre-transition food-label provisions; Order 100 and GB 7718-2025 effective March 16, 2027 | GSO 1926 energy-drink requirements; caffeine-menu disclosure since July 1, 2025 |
| Commercial effect | Nutrition labeling and authorization conditions for regulated health claims | Nutrition tables for most beverages; packaged waters have a table exemption under separate constituent rules | Authorized, substantiated health claims; energy-drink composition limits and applicable caffeine warnings | Existing date and shelf-life marking; adopted date-placement and legibility changes for prepackaged foods | Energy-drink preregistration, ingredient limits and package warnings; restaurants and cafes carry the menu duty |
| Current policy attractiveness | Medium | Medium | Low | Medium | Low |
| Future direction of policy attractiveness | Hardening | No change | No change | Hardening | No change |
| Source: Mordor Intelligence | |||||
The US Medium rating reflects nutrition-label and regulated health-claim duties, with Hardening indicated because the FDA’s Unified Agenda entry schedules a final front-of-package rule for December 2026, while Brazil’s Medium and No change judgments reflect the operative RDC 429/2020 nutrition-table rules, which continue to apply alongside revisions that Anvisa approved for 120-day public consultations on October 29, 2025. Germany is rated Low because claim authorization and energy-drink controls constrain formulations and positioning, and No change reflects continued operative controls while EU revision objectives remain prospective. China’s Medium rating moves toward Hardening because more prescriptive prepackaged-food date placement and type-size requirements take effect on March 16, 2027. Saudi Arabia’s Low and No change judgments reflect established energy-drink registration, composition and package-warning duties, alongside the restaurant and cafe caffeine-menu regime effective since July 1, 2025.
Value Chain Stages
Earnings arise at distinct stages, from formulation inputs and branded concentrates to containers and finished beverages, beginning with premix and flavor solutions supplied by Glanbia. The Coca-Cola Company earns revenue from concentrate and syrup sales to authorized bottlers under agreements subject to specified terms and local law, while PepsiCo’s International Beverages Franchise also sells concentrates to authorized and independent bottlers. Ball earns container revenue primarily through multi-year supply contracts with beverage fillers. Coca-Cola FEMSA, which operated 55 bottling plants across Latin America in 2025, captures value through finished-beverage sales after converting inputs into packaged drinks.
Value Chain Analysis Table of Functional Beverage Market
| Primary activity | Key participants | Value capture | Bottleneck | Resilience response |
|---|---|---|---|---|
| Ingredient and formulation development | Premix and flavor suppliers such as Glanbia Plc | Premix and flavor solution sales | Translating a benefit into a usable beverage formulation | Develop premix and flavor together around the finished drink’s purpose |
| Beverage concentrate production | Concentrate suppliers such as The Coca-Cola Company and PepsiCo Inc. | Concentrate and syrup sales | Coordinating the brand owner’s input with independent bottling operations | Define preparation and supply responsibilities in locally applicable agreements |
| Container manufacturing | Aluminum beverage-container manufacturers such as Ball Corporation | Container sales, primarily through multi-year supply contracts | Demand mismatches within longer-term container commitments | Align container commitments with finished-beverage production plans |
| Beverage preparation and bottling | Integrated beverage bottlers such as Coca-Cola FEMSA | Finished-beverage sales | Synchronizing beverage and packaging flows across bottling operations | Coordinate filling schedules and material delivery at the plant level |
| Finished-beverage distribution | Direct-store-delivery operators such as PepsiCo Inc., alongside its independent bottlers and distributors | Branded beverage sales through retail delivery | Coordinating delivery across company, bottler and distributor roles | Assign outlet-service responsibilities among the delivery operators |
| Source: Mordor Intelligence | ||||
Ball reported that recycled sources supplied 74% of the aluminum used in its Beverage Packaging business in 2025.[3] That input mix ties the container stage to the collection and reprocessing of used aluminum. A filler buying Ball cans is therefore exposed to the availability of recovered aluminum.
Competitive Landscape
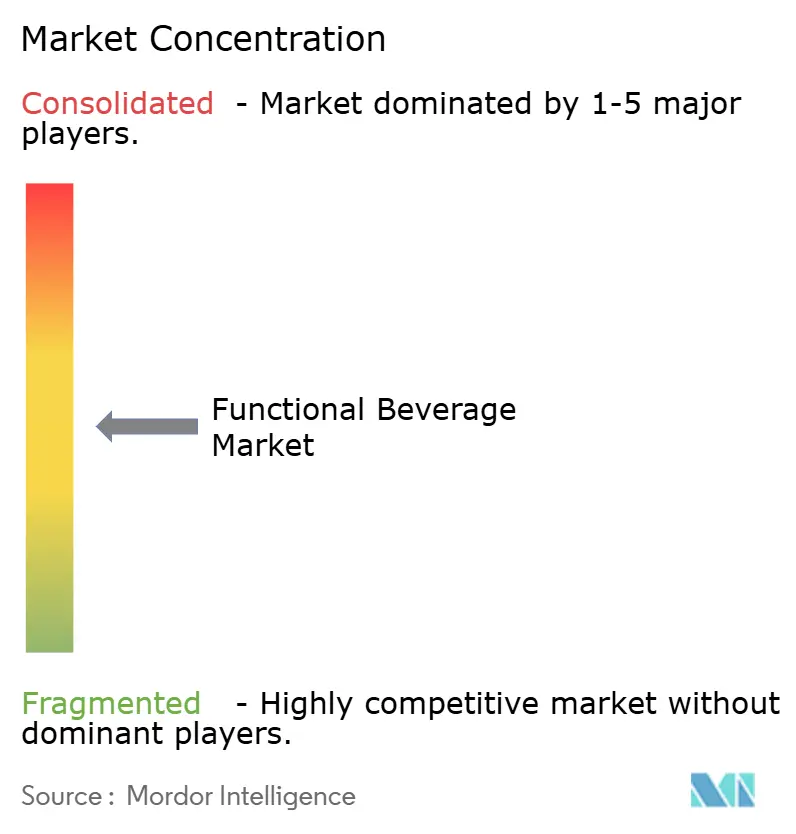
Major suppliers combine different portfolio structures, with PepsiCo Inc. owning prebiotic soda brand poppi and Monster Beverage Corp. operating a dedicated energy-drinks segment. Red Bull GmbH sold almost 14 billion cans of its energy drink in 2025, more than 10% above 2024. Danone SA’s Waters division, encompassing plain water, flavored water and functional beverages, accounted for 18% of group sales in 2025. The Coca-Cola Company reported 1% sports-drink unit-case volume growth across its beverage system in 2025, primarily driven by North America and Europe, the Middle East and Africa. These structures place functional drinks both at the center of specialist businesses and within wider beverage portfolios.
PepsiCo completed its acquisition of poppi, a US prebiotic soda brand, on May 19, 2025. The announced consideration was USD 1.95 billion, including USD 300 million in anticipated cash tax benefits, for a net purchase price of USD 1.65 billion. Beyond that consideration, the transaction included a performance-based earnout contingent on achieving specified performance metrics. With poppi inside PepsiCo’s portfolio after the May 19, 2025, closing, other prebiotic soda suppliers compete against a brand backed by a diversified incumbent.
On October 15, 2025, the EU General Court dismissed the challenge by Red Bull GmbH, Red Bull France SASU and Red Bull Nederland BV to a European Commission inspection order in the energy-drinks sector. The case concerned the validity of an inspection order based on suspected competition-law infringements. On August 4, 2026, The Economic Times cited industry executives reporting new Sting cans and bottles being manufactured without “energy” in India while related advertising was being reworked. The report also attributed to industry executives separate requests by Red Bull, Reliance Consumer Products, Monster and Hell to delay the 90-day compliance deadline beginning July 1, 2026. These responses show energy-drink suppliers addressing scrutiny of competitive conduct in the EU and changes to product presentation in India.
Functional Beverage Industry Leaders
-
PepsiCo Inc.
-
Monster Beverage Corp.
-
Red Bull GmbH
-
Danone SA
-
The Coca-Cola Company
- *Disclaimer: Major Players sorted in no particular order
Functional Beverage Market Companies Covered in this Report
- PepsiCo Inc.
- The Coca-Cola Company
- Red Bull GmbH
- Monster Beverage Corp.
- Danone SA
- CENTR Brands Corporation (Centr)
- Nestle SA
- Otsuka Holdings Co. Ltd
- Blue Diamond Growers
- Oatly Group AB
- Keurig Dr Pepper Inc.
- Celsius Holdings Inc.
- Yakult Honsha Co. Ltd
- Vita Coco Company Inc.
- Hint Inc.
- Flow Beverage Corp. (Flow)
- Vitamin Well
- BioSteel Sports Inc.
- VOSS Water Global
- Glanbia Plc
Key Opportunities for Market Participants
The opportunities compare benefit-based retail navigation with focused protein and mood-support beverage propositions for US grocery shoppers. In its survey fielded May 19 to 26, 2026, FMI, the Food Industry Association, found that these shoppers increasingly sought hydration, energy, protein, digestive-health and mood-support benefits from beverages. FMI also identified an opportunity for US food retailers to organize beverage merchandising around functional needs and drinking occasions. This places retailers alongside product developers as participants in functional beverage differentiation.
Market Opportunities Table of Functional Beverage Market
| Opportunity | Why now | Buyer / lead segment | Recommended play | Main barrier | Likely beneficiaries |
|---|---|---|---|---|---|
| Benefit-based beverage navigation | 2026 research connects beverage choice with functional needs and occasions | US grocery retailers | Group relevant finished beverages by need and occasion | Keeping overlapping benefits understandable | Retailers and suppliers with clearly defined beverage propositions |
| Focused ready-to-drink protein propositions | Protein is among the benefits US shoppers seek | US grocery shoppers seeking protein | Develop a drink around a specific protein-led use | Turning benefit interest into a product-specific choice | Ready-to-drink protein beverage suppliers |
| Mood-oriented drinking occasions | US shopper research identifies mood support as a sought benefit | US grocery shoppers seeking mood support | Define a narrow drinking occasion with a defensible benefit proposition | Matching the promised purpose to substantiated product claims | Suppliers of beverages positioned for mood support |
| Source: Mordor Intelligence | |||||
The central opening is to make a particular benefit easier to find and understand at the point of sale. A shelf organized by need would group protein, digestive-health and mood-support drinks separately, so each supplier’s product would be judged against others sold for the same benefit. An existing formulation could therefore reach benefit-seeking shoppers through category design, giving its supplier a merchandising option alongside product development.
Recent Industry Developments in Functional Beverage Market
- Oct 2026: PepsiCo told the Delhi High Court on October 15 that its Indian energy drinks could run out nationwide within 2 months while new production under the “energy drink” label remained barred. The merits remained undecided, with another hearing set for October 30, 2026.
- Jun 2026: Beyond Meat, Inc. began the initial retail and foodservice launch of Beyond Immerse, its first functional beverage line, in the New York metro area. Its distribution agreement with Big Geyser provided access to more than 26,000 outlets.
- Jun 2026: The Coca-Cola Company’s BODYARMOR brand launched BODYARMOR FIT on June 1, introducing a sparkling sports drink in 12-ounce cans across US stores and online.
Functional Beverage Market Report Scope and Research Methodology
Market Definition and Coverage
The functional beverage market covers non-alcoholic drinks sold for hydration or refreshment with ingredients or formulations positioned to provide nutritional or functional benefits. It measures annual spending in USD on these packaged beverages through retail and foodservice sales worldwide.
Scope exclusions: Alcoholic beverages, conventional beverages without a nutritional or functional benefit positioning, dietary supplements sold as powders, capsules, tablets, or similar products, and separately sold ingredients and beverage packaging are excluded.
Segments Covered in This Report
- By Product Type
- Energy Drinks
- Sports Drinks
- Fortified Juice
- Dairy and Dairy Alternative Beverages
- Functional/Fortified Water
- Others
- By Packaging Type
- PET/Glass Bottles
- Cans
- Tetra Pak
- Other Types
- By Distribution Channel
- On-Trade
- Off-Trade
- Supermarkets/Hypermarkets
- Pharmacies and Health Stores
- Convenience Stores
- Online Retail Stores
- Other Retail Channels
- By Geography
- North America
- United States
- Canada
- Mexico
- Rest of North America
- South America
- Brazil
- Argentina
- Colombia
- Chile
- Rest of South America
- Europe
- United Kingdom
- Germany
- France
- Italy
- Spain
- Russia
- Sweden
- Belgium
- Poland
- Netherlands
- Rest of Europe
- Asia-Pacific
- China
- Japan
- India
- Thailand
- Singapore
- Indonesia
- South Korea
- Australia
- New Zealand
- Rest of Asia-Pacific
- Middle East and Africa
- United Arab Emirates
- South Africa
- Saudi Arabia
- Nigeria
- Egypt
- Morocco
- Turkey
- Rest of Middle East and Africa
- North America
Data Sources, Market Sizing, and Validation
Desk Research
To compare available beverage supply, retail and foodservice sales, and claim context, analysts use sources such as the USDA Economic Research Service food availability series, U.S. Census Bureau retail and foodservice sales data, Codex guidance on food claims, and the World Health Organization's review of non-sugar sweeteners. These sources describe different measures, so analysts use availability as a volume signal, sales data as channel context and guidance as a regulatory reference.
To check product, sales, distribution and investment developments, analysts consult company annual reports, 10-K and other regulatory filings, investor materials and reputable press coverage. The named sources are illustrative rather than exhaustive, and further sources inform collection, validation and clarification.
Primary Interviews and Surveys
Interviews and structured surveys would target beverage manufacturers, brand owners, retailers, foodservice operators and ingredient or packaging specialists, with respondents covering commercial, category, finance, sales and regulatory roles across APAC, EMEA and the Americas. Their input would test secondary findings on product definitions, realized selling prices, channel mix, category growth and regional demand, while resolving gaps through focused follow-up and comparison with company disclosures and public market indicators. Analysts would triangulate disagreements at the variable and segment level before incorporating supported adjustments into the estimates.
Distribution of primary research fieldwork respondents
| Company type | Respondent position | Region |
|---|---|---|
| Top tier: 34% | CXOs: 20% | APAC: 40% |
| Mid tier: 43% | Functional/Unit leaders: 35% | EMEA: 30% |
| Smaller Players: 23% | Managers: 45% | Americas: 30% |
Market-Sizing & Forecasting
Annual global value is estimated top down from finished-beverage demand and spending through retail and foodservice, using beverage availability and sales indicators, product mix across the defined drink types, country-level purchasing power and distribution access to establish the total and its allocation across product, packaging, channel and regional dimensions. Segment shares draw on published category splits where available and are checked against product portfolios, channel structure and country demand, and where a split is unavailable, analysts estimate category shares from these signals and reconcile each axis to the market total. Scenario analysis projects volume demand using economic conditions, wellness interest, category growth, retail access and regulatory or packaging costs, while realized prices and product mix are assessed separately to derive value growth. Selective bottom-up checks use sampled average selling prices multiplied by volumes, supplier roll-ups and channel checks, while gaps in these checks are reconciled to the top-down estimate using public disclosures and primary research, and experts review the direction and assumptions of each key variable forecast.
Data Validation & Update Cycle
Analysts triangulate company disclosures, official statistics, public market indicators and primary findings, then check totals, segment shares, historical movement and source definitions for anomalies or material variances. A second analyst reviews calculations and evidence, with senior review resolving flagged differences before sign-off, and respondents are re-contacted when definitions conflict, an input changes materially or a gap could alter a segment conclusion. The model is refreshed annually, revisited between cycles after material market or regulatory events, and given a fresh pre-delivery review of sources, calculations and narrative consistency.
Mordor Intelligence's Functional Beverage Market Size Measured Against Other Published Estimates
Published estimates can differ in the transactions and products they count and the inputs used to model demand. The functional beverage market covers non-alcoholic drinks sold for hydration or refreshment with ingredients or formulations positioned to provide nutritional or functional benefits.
Key Gap Drivers include the study's defined coverage and market-specific modeling choices. Annual global value is estimated top down from finished-beverage demand and spending through retail and foodservice, using beverage availability and sales indicators, product mix across the defined drink types, country-level purchasing power and distribution access to establish the total and its allocation across product, packaging, channel and regional dimensions.
Benchmark comparison
| Source | Market Size | Gaps in Research Methodology |
|---|---|---|
| Mordor Intelligence | USD 176.8 B (2027) | |
| Global Market Research Firm A | USD 151.7 B (2025) | At its 2025 base, this estimate is 14.2% below this report's 2027 value of USD 176.8 B, 2 years later. Growth after its base period can raise the later reported value. |
| Global Market Research Firm B | USD 164.7 B (2025) | At its 2025 base, this estimate is 6.9% below this report's 2027 value of USD 176.8 B, 2 years later. Growth after its base period can raise the later reported value. |
Mordor Intelligence's analysts triangulate company disclosures, official statistics, public market indicators and primary findings, then check totals, segment shares, historical movement and source definitions for anomalies or material variances.
Key Questions Answered in the Report
What is the functional beverage market size and growth outlook?
The market is expected to grow from USD 176.8 billion in 2027 to USD 255.3 billion by 2032, at a CAGR of 7.62% over 2027-2032.
What drives demand for functional drinks?
Health and wellness demand is a key driver. In EY’s 2025 US survey, 52% of consumers said they were willing to pay more for drinks supporting health and wellness goals.
Which functional drink type leads sales?
Energy drinks held the largest share at 28.77% in 2026, while sports drinks are forecast to grow fastest at a CAGR of 8.11% over 2027-2032.
Which companies are major functional beverage suppliers?
Major suppliers include PepsiCo Inc., Monster Beverage Corp., Red Bull GmbH, Danone SA and The Coca-Cola Company.
What could limit growth in functional drinks?
Packaging obligations add costs. Since October 2025, qualifying large UK organizations have faced disposal fees for household or commonly binned packaging and glass household drinks containers.
Which regions lead functional beverage spending and growth?
North America held 38.82% of global spending in 2026, while Asia-Pacific is projected to grow fastest at a CAGR of 8.2% over 2027-2032.