
Europe Satellite Manufacturing Market Size and Share
Market Overview
| Study Period | 2019 - 2031 |
|---|---|
| Forecast Data Period | 2026 - 2031 |
| Base Year Market Size (2025) | USD 3.25 Billion |
| Market Size (2026) | USD 3.62 Billion |
| Market Size (2031) | USD 9.62 Billion |
| Growth Rate (2026 - 2031) | 21.59 % |
| Market Concentration | Medium |
Major Players *Disclaimer: Major Players sorted in no particular order Image © Mordor Intelligence. Reuse requires attribution under CC BY 4.0. | |
Europe Satellite Manufacturing Market Analysis by Mordor Intelligence
Europe Satellite Manufacturing Market Analysis by Mordor Intelligence
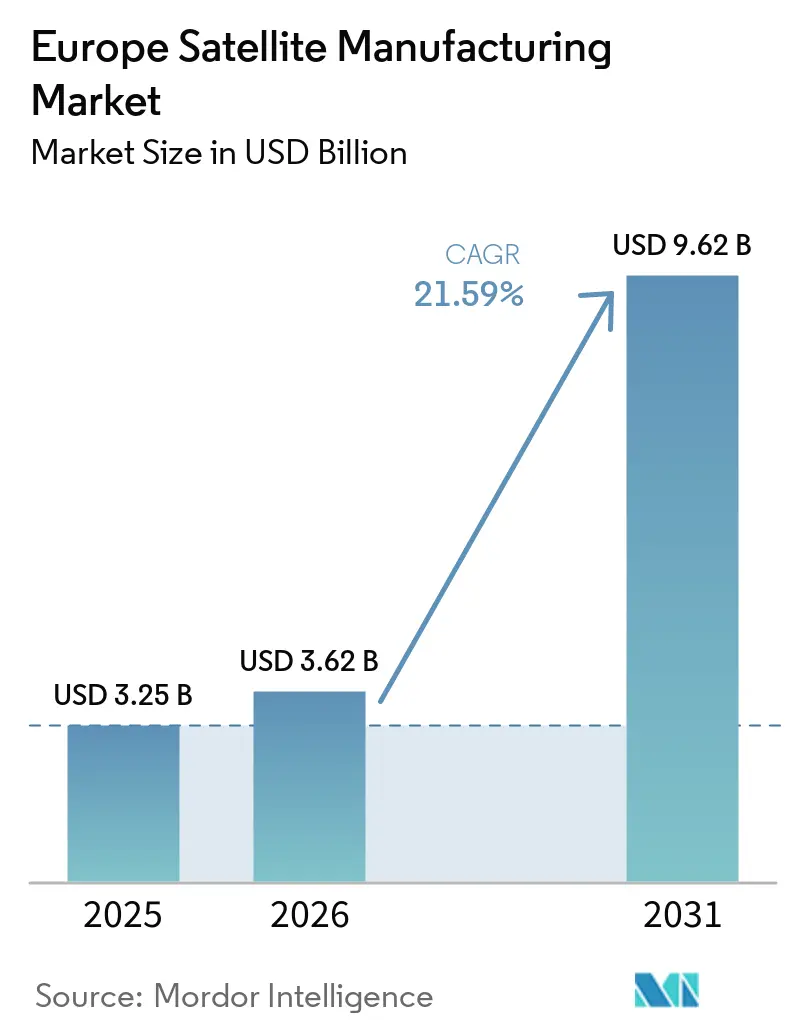
The Europe satellite manufacturing market size was valued at USD 3.25 billion in 2025 and is estimated to grow from USD 3.62 billion in 2026 to reach USD 9.62 billion by 2031, at a CAGR of 21.59% during the forecast period (2026-2031). The market is supported by a regional shift toward secure connectivity, independent Earth observation, and sovereign space systems. The EUR 10.60 billion (USD 11.45 billion) IRIS² concession creates a lengthy procurement cycle for 348 satellites across LEO and MEO orbits. The market also benefits from rising institutional demand for radar, optical, and hyperspectral missions, which raises the value of platforms and payloads. Large programs favor suppliers with qualified production lines, while smaller manufacturers are gaining contracts where serial production and delivery speed are decisive. Launch capacity, national procurement preferences, and qualification requirements remain practical limits on how quickly the Europe satellite manufacturing market can turn its contracted orders into delivered satellites.
Key Report Takeaways
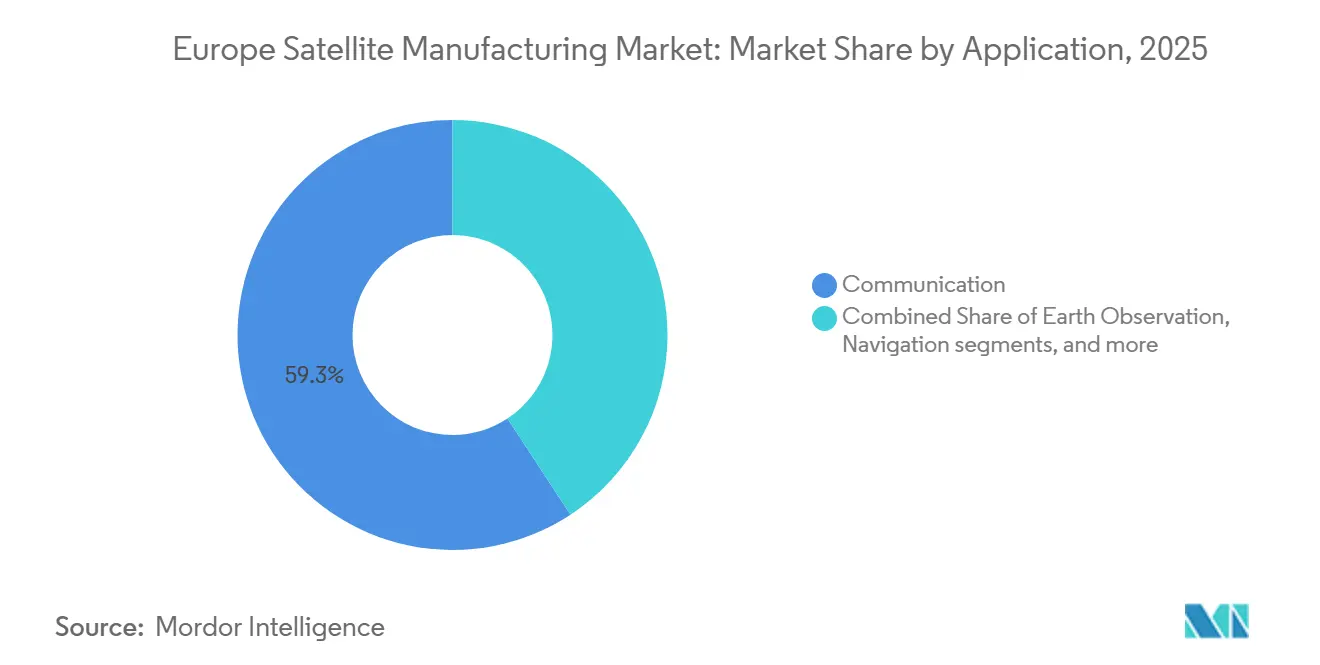
- By application, communication satellites held 59.25% of the Europe satellite manufacturing market share in 2025, while Earth observation is forecast to grow at a 23.71% CAGR through 2031.
- By satellite mass, medium satellites accounted for 52.89% of the Europe satellite manufacturing market share in 2025, while small satellites are projected to expand at a 24.52% CAGR through 2031.
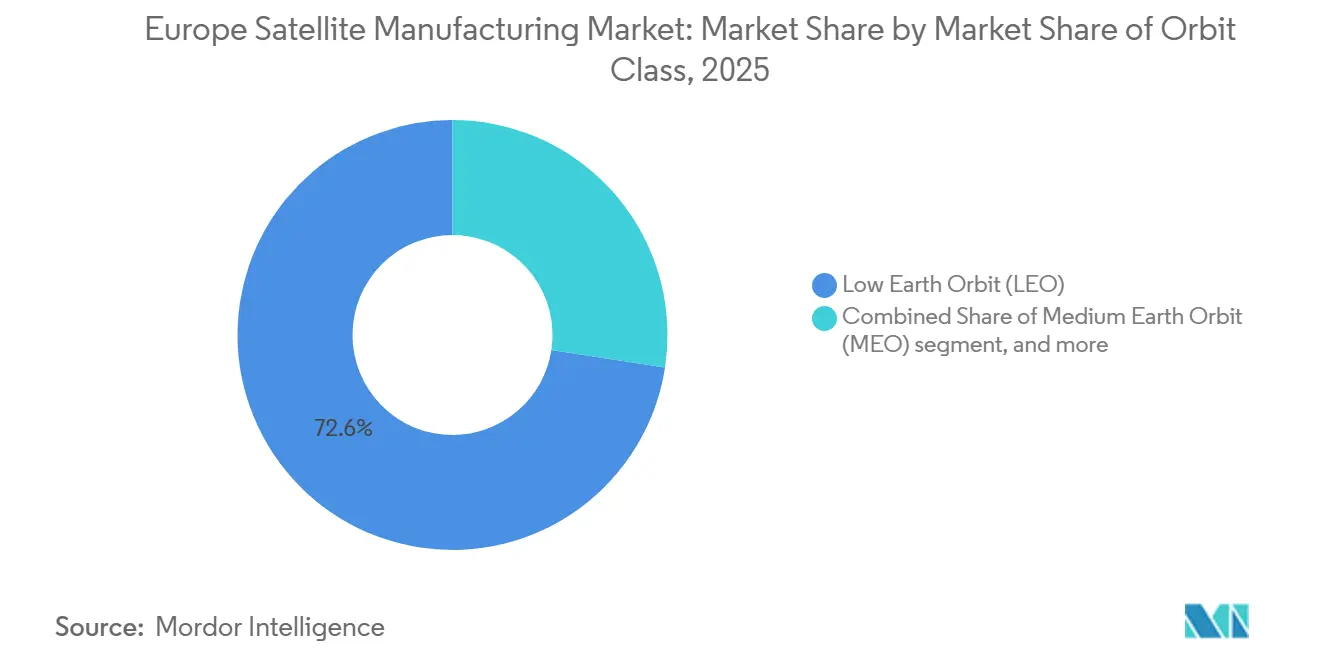
- By orbit class, LEO satellites held 65.75% of the Europe satellite manufacturing market share in 2025, while MEO satellites are forecast to grow at a 24.83% CAGR through 2031.
- By end user, commercial users accounted for 65.32% of the Europe satellite manufacturing market share in 2025 and are expected to grow at a 25.94% CAGR through 2031.
- By geography, France held 43.77% of the Europe satellite manufacturing market share in 2025, while the United Kingdom is projected to grow at a 26.42% CAGR through 2031.
Note: Market size and forecast figures in this report are generated using Mordor Intelligence’s proprietary estimation framework, updated with the latest available data and insights as of January 2026.
Europe Satellite Manufacturing Market Trends and Insights
Drivers Impact Analysis*
| DRIVER | (~) % IMPACT ON CAGR FORECAST | GEOGRAPHIC RELEVANCE | IMPACT TIMELINE |
|---|---|---|---|
| Sovereign secure connectivity and defense spending | 5.50% | Global, concentrated in France, Germany, and Eastern Europe | Short term (≤ 2 years) |
| Institutional earth observation and climate monitoring procurement | 4.20% | France, Germany, Italy, the UK, with spillover to the Nordics and Eastern Europe | Medium term (2-4 years) |
| Small-satellite constellation industrialization | 3.80% | France, the UK, Germany, and Belgium | Medium term (2-4 years) |
| Satellite miniaturization and digital production | 2.90% | France, Germany, and Italy | Long term (≥ 4 years) |
| Resilient European supply-chain procurement | 2.10% | Pan-European, with early gains in France, Germany, and Eastern Europe | Medium term (2-4 years) |
| Zero-debris design as a product differentiator | 1.40% | Pan-European, led by Eurpoean Space Agency signatory nations | Long term (≥ 4 years) |
| Source: Mordor Intelligence | |||
Sovereign Secure Connectivity and Defense Spending
European governments are directing more procurement toward systems they can own, operate, and secure within the region. The IRIS² concession signed in December 2024 commits EUR 10.60 billion (USD 11.45 billion) over 12 years for 348 satellites in LEO and MEO orbits.[1] This framework gives the Europe satellite manufacturing market a visible order base beyond shorter commercial replacement cycles. Portugal, Poland, Sweden, and Finland are also seeking complete systems that include spacecraft, ground equipment, and operations. This arrangement expands the value captured by manufacturers that can act as prime contractors rather than component suppliers. Germany’s planned military space investment and parallel national programs further support demand for intelligence, surveillance, and reconnaissance (ISR), secure communications, and spacecraft.[2]
Institutional Earth Observation and Climate Monitoring Procurement
Earth observation procurement has become more closely connected to defense needs for radar, optical imaging, and hyperspectral collection. Thales Alenia Space received the June 2026 prime contract for 2 Copernicus Sentinel-1 Next Generation satellites, with a first tranche of EUR 700 million (USD 784.44 million).[3] These missions extend continuity for radar monitoring and give suppliers longer program visibility. The European Space Agency (ESA) also awarded architecture studies for the European Earth Observation Governmental Service to ICEYE and Leonardo.[4] Dual-use designs can support both civil monitoring and military surveillance within related platform architectures. That overlap supports higher-value payload integration and reduces the dependence on any single civilian program. The Europe satellite manufacturing market, therefore, has a broader institutional customer base for Earth observation missions.
Small Satellite Constellation Industrialization
Serial production is becoming a key requirement for companies seeking constellation-scale contracts. Aerospacelab secured a EUR 2.40 billion (USD 2.64 billion) contract in September 2026 to build 264 LEO satellites for IRIS². The award shows that installed factory capacity can be evaluated before a contract is awarded. Smaller standardized platforms also help manufacturers repeat integration and test procedures across many units. ESA's work on reduced interfaces for mid-size LEO satellites supports more repeatable manufacturing practices. These changes favor suppliers that can document throughput, supplier capacity, and consistent quality. They also increase pressure on legacy primes to adapt traditional project-based processes for higher production volumes.
Satellite Miniaturization and Digital Production
Miniaturization is changing satellite manufacturing by replacing some fixed hardware functions with software-defined systems. Digital production methods also allow factories to use common processes across several platform types. Thales Alenia Space opened a EUR 100 million (USD 112.60 million) digital manufacturing facility in Rome in 2025. Airbus has continued to expand production of OneWeb spacecraft in Toulouse under its Eutelsat contracts.[5] Standardized modular designs can reduce repeat engineering work and improve the use of specialized labor. This model enables manufacturers to respond to multiple constellations without building a separate line for every customer. It also creates an opportunity for industrial companies to enter the Europe satellite manufacturing market through partnerships with established spacecraft specialists.
Restraints Impact Analysis*
| RESTRAINT | (~) % IMPACT ON CAGR FORECAST | GEOGRAPHIC RELEVANCE | IMPACT TIMELINE |
|---|---|---|---|
| Fragmented procurement and national industrial preferences | -1.80% | Pan-European, most acute in smaller European Space Agency member states | Medium term (2-4 years) |
| Launch slot and independent access-to-space bottlenecks | -1.60% | Pan-European, with highest impact on the UK, Germany, and Italy | Short term (≤ 2 years) |
| Qualification, cybersecurity, and COTS compliance burden | -1.20% | Pan-European, most acute for new market entrants | Long term (≥ 4 years) |
| High capital, testing, and launch costs | -1.00% | Pan-European, most acute for smaller manufacturers | Long term (≥ 4 years) |
| Source: Mordor Intelligence | |||
Fragmented Procurement and National Industrial Preferences
European procurement is coordinated through common institutions, but national contributions and industrial return practices still influence contract allocation. This can lead to similar capabilities being maintained in several national supply chains. New manufacturers must also meet qualification, cybersecurity, export-control, and subcontractor approval requirements developed for large prime contractors. These processes increase the time and cost required to gain admission to institutional programs. The effect is most significant for businesses that have production capacity but limited heritage in major public missions. The Europe satellite manufacturing market may therefore consolidate more slowly than its demand profile would otherwise support.
Launch Slot and Independent Access to Space Bottlenecks
Satellite manufacturing output depends on the availability of launch opportunities after a spacecraft leaves the factory. European launch systems improved their cadence in 2025, but available capacity remains limited relative to rising demand for constellation deployment. This constraint can delay acceptance of deliveries and increase reliance on rideshare options. It also adds planning risk for programs that require specific orbital planes or rapid replenishment. Manufacturers with flexible launch planning and customers with diversified launch options are better positioned to manage the limitation. The issue is especially relevant for serial producers that need regular launches to keep working capital moving through their production lines.
*Our forecasts treat driver/restraint impacts as directional, not additive. The impact forecasts reflect baseline growth, mix effects, and variable interactions.
Segment Analysis
By Application: Communication Anchors Revenue, Earth Observation Accelerates
Communication satellites accounted for 59.25% of the Europe satellite manufacturing market in 2025, supported by institutional connectivity programs and frequent replenishment of broadband constellations. Airbus continued to receive OneWeb-related production work from Eutelsat during 2026. The segment benefits from the need to replace and expand multi-satellite networks rather than relying on isolated spacecraft orders. Secure communications systems also use established supply chains for satellite buses, antennas, and payload integration.
Earth observation is forecast to grow at a 23.71% CAGR through 2031. Demand is linked to intelligence, surveillance, reconnaissance, environmental monitoring, and climate services. The Sentinel-1 Next Generation contract shows continued procurement for radar observation systems. Navigation, space observation, technology demonstrations, hosted payloads, and in-orbit validation missions remain smaller but valuable sources of specialized work.

By Satellite Mass: Medium Platforms Lead by Value, Small Grows Fastest
Medium satellites accounted for 52.89% of the Europe satellite manufacturing market size in 2025. Platforms in the 200 kg to 500 kg range can carry more capable payloads than a small satellite while remaining suitable for constellations. Their capacity makes them relevant to secure connectivity, MEO systems, and dual-use intelligence missions. The class offers a balance between payload capability, power requirements, and unit numbers for large programs.
Small satellites are projected to grow at a 24.52% CAGR through 2031. Their lower mass supports grouped launches and repeat production, which can improve deployment speed. Aerospacelab’s 264-satellite IRIS² contract demonstrates the scale that is possible with standardized LEO platforms. Large satellites remain relevant for sovereign geostationary communications and complex missions, although lower commercial demand limits their wider role.
By Orbit Class: LEO Drives Volume, MEO Claims the Premium Tier
LEO satellites held 65.75% of the Europe satellite manufacturing market share in 2025. Its position reflects the large number of standardized satellites needed for broadband, Earth observation, and secure connectivity constellations. Airbus’s Toulouse activity for OneWeb demonstrates the production cadence associated with this orbit class. Recurring replenishment creates a broader competitive field for small and medium satellite manufacturers.
MEO satellites are forecast to grow at a 24.83% CAGR through 2031. OHB signed a contract worth EUR 1 billion (USD 1.12 billion) in August 2026 for 18 IRIS² MEO satellite platforms. These spacecraft need greater power, thermal management, and platform integration, which keeps the supplier base narrower and unit values higher. GEO satellites remain relevant for sovereign communications and defense missions, but commercial demand has shifted toward lower orbit systems.
By End User: Commercial Demand Anchors the Market
Commercial users accounted for 65.32% of the Europe satellite manufacturing market in 2025. The category includes private constellation operators and commercially structured public-private programs such as IRIS². Commercial customers place value on delivery schedules, standardized designs, and scalable production capacity. The European Commission’s CASSINI initiative also supports a wider group of space businesses and downstream users.
Commercial end users are forecast to grow at a 25.94% CAGR through 2031. Broadband constellations require recurring spacecraft replacements and entail longer-running production programs. Government and civil buyers continue to purchase high-specification systems for meteorology, environmental monitoring, and security missions. Manufacturers with diverse commercial and institutional order books are better able to manage delays in individual public programs.
Geography Analysis
France held 43.77% of the Europe satellite manufacturing market share in 2025. Airbus’s Toulouse facility and Thales Alenia Space’s French operations provide capacity for complex systems and serial integration. The supplied research identifies EUR 6.40 billion, or USD 6.98 billion, in French military space funding through 2030. France’s role in ESA and civil space research spending supports continuity across long mission development cycles.
The UK is forecast to grow at a 26.42% CAGR through 2031. The country has a substantial operational satellite base and is building greater domestic manufacturing capability. The UK Space Agency reported GBP 775 million (USD 1.01 billion) in disbursements for 2025-26. This funding supports commercial development, national security, and technology programs.
Germany’s forward procurement pipeline is supported by military space investment and a EUR 5.10 billion (USD 5.71 billion) contribution from the ESA for 2026-2028, as reported in the supplied research. Bremen, Berlin, and Munich are important locations for established manufacturers and newer space companies. Italy supports the Europe satellite manufacturing market through Thales Alenia Space Italia’s Rome digital factory and other production hubs. Russia’s role has contracted following sanctions and the suspension of ESA-Roscosmos programs. The rest of Europe is expanding through Aerospacelab, EnduroSat, NanoAvionics, GomSpace, and SatRev. These companies show that constellation manufacturing is spreading beyond the traditional French, German, Italian, and British centers.
Competitive Landscape
The Europe satellite manufacturing market is moderately concentrated around Airbus SE, Thales Alenia Space, and OHB SE, which hold major institutional mandates. Their experience with complex missions, compliance processes, and public procurement strengthens their position in high-value programs. ESA selected these large integrators in June 2024 for work on zero-debris large LEO satellite buses. These contracts require system engineering, reliability assurance, and environmental design capabilities. The established firms are also investing in standardized production for constellation programs.
Competitive pressure is increasing from Aerospacelab, EnduroSat, ICEYE, and NanoAvionics. Aerospacelab’s September 2026 IRIS² award shows that a newer manufacturer can secure a major institutional production mandate. ICEYE delivered Poland’s MikroSAR system in under 12 months, including 4 radar satellites, a ground segment, and operator training. Thales Alenia Space won the Sentinel-1 Next Generation prime contract in June 2026. The middle tier is an opportunity for suppliers capable of producing 50 to 300 satellites per year at a lower cost than the largest primes.
Strategic approaches differ between established and newer companies. Legacy suppliers use qualification records and institutional relationships to secure high-specification contracts. Newer companies compete through modular platforms, short delivery cycles, and factory capacity. Airbus signed development work for 66 Ka-band LEO IRIS² satellites for Eutelsat in September 2026.
Europe Satellite Manufacturing Industry Leaders
-
Airbus SE
-
Thales Alenia Space
-
OHB SE
-
AAC Clyde Space AB
-
GomSpace A/S
- *Disclaimer: Major Players sorted in no particular order
Recent Industry Developments
- September 2026: Aerospacelab secured a EUR 2.40 billion (USD 2.64 billion) contract to manufacture 264 LEO satellite platforms for IRIS², with delivery targeted ahead of 2030.
- September 2026: Thales Alenia Space secured an initial EUR 500 million (USD 560.32 million) tranche for secure governmental payloads for 330 IRIS² LEO satellites.
- September 2026: Airbus started development of 66 Ka-band LEO satellites for Eutelsat’s IRIS² program and received authorization for 229 additional OneWeb satellites.
- August 2026: OHB SE signed a contract worth nearly EUR 1 billion (USD 1.12 billion) with SES for 18 IRIS² MEO satellite platforms.
- June 2026: Thales Alenia Space received the Sentinel-1 Next Generation prime contract, with a first tranche of EUR 700 million (USD 784.44 million)
Europe Satellite Manufacturing Market Report Scope
The satellite manufacturing market includes the design, engineering, production, assembly, integration, and testing of satellites and their major subsystems for deployment in Earth orbit or beyond. It covers the manufacture of satellite platforms/buses, payloads, propulsion systems, power systems, thermal and structural components, avionics, communication systems, and other spacecraft subsystems.
The Europe satellite manufacturing market report is segmented by application, satellite mass, orbit class, end user, and geography. By application, the market is segmented by communication, Earth observation, navigation, space observation, and others. By satellite mass, the market is segmented into small, medium, and large. By orbit class, the market is segmented into low Earth orbit (LEO), medium Earth orbit (MEO), and geostationary orbit (GEO). By end user, the market is segmented into commercial, government and civil, and military. The report also covers the market sizes and forecasts for the Europe satellite manufacturing market in five countries across the region. For each segment, the market size is provided in terms of value (USD).
| Communication |
| Earth Observation |
| Navigation |
| Space Observation |
| Others |
| Small |
| Medium |
| Large |
| Low Earth Orbit (LEO) |
| Medium Earth Orbit (MEO) |
| Geostationary Orbit (GEO) |
| Commercial |
| Government and Civil |
| Military |
| United Kingdom |
| France |
| Germany |
| Russia |
| Italy |
| Rest of Europe |
| By Application | Communication |
| Earth Observation | |
| Navigation | |
| Space Observation | |
| Others | |
| By Satellite Mass | Small |
| Medium | |
| Large | |
| By Orbit Class | Low Earth Orbit (LEO) |
| Medium Earth Orbit (MEO) | |
| Geostationary Orbit (GEO) | |
| By End User | Commercial |
| Government and Civil | |
| Military | |
| By Geography | United Kingdom |
| France | |
| Germany | |
| Russia | |
| Italy | |
| Rest of Europe |
Market Definition
- Application - Various applications or purposes of the satellites are classified into communication, earth observation, space observation, navigation, and others. The purposes listed are those self-reported by the satellite’s operator.
- End User - The primary users or end users of the satellite is described as civil (academic, amateur), commercial, government (meteorological, scientific, etc.), military. Satellites can be multi-use, for both commercial and military applications.
- Launch Vehicle MTOW - The launch vehicle MTOW (maximum take-off weight) means the maximum weight of the launch vehicle during take-off, including the weight of payload, equipment and fuel.
- Orbit Class - The satellite orbits are divided into three broad classes namely GEO, LEO, and MEO. Satellites in elliptical orbits have apogees and perigees that differ significantly from each other and categorized satellite orbits with eccentricity 0.14 and higher as elliptical.
- Propulsion tech - Under this segment, different types of satellite propulsion systems have been classified as electric, liquid-fuel and gas-based propulsion systems.
- Satellite Mass - Under this segment, different types of satellite propulsion systems have been classified as electric, liquid-fuel and gas-based propulsion systems.
- Satellite Subsystem - All the components and subsystems which includes propellants, buses, solar panels, other hardware of satellites are included under this segment.
| Keyword | Definition |
|---|---|
| Attitude Control | The orientation of the satellite relative to the Earth and the sun. |
| INTELSAT | The International Telecommunications Satellite Organization operates a network of satellites for international transmission. |
| Geostationary Earth Orbit (GEO) | Geostationary satellites in Earth orbit 35,786 km (22,282 mi) above the equator in the same direction and at the same speed as the earth rotates on its axis, making them appear fixed in the sky. |
| Low Earth Orbit (LEO) | Low Earth Orbit satellites orbit from 160-2000km above the earth, take approximately 1.5 hours for a full orbit and only cover a portion of the earth’s surface. |
| Medium Earth Orbit (MEO) | MEO satellites are located above LEO and below GEO satellites and typically travel in an elliptical orbit over the North and South Pole or in an equatorial orbit. |
| Very Small Aperture Terminal (VSAT) | Very Small Aperture Terminal is an antenna that is typically less than 3 meters in diameter |
| CubeSat | CubeSat is a class of miniature satellites based on a form factor consisting of 10 cm cubes. CubeSats weigh no more than 2 kg per unit and typically use commercially available components for their construction and electronics. |
| Small Satellite Launch Vehicles (SSLVs) | Small Satellite Launch Vehicle (SSLV) is a three-stage Launch Vehicle configured with three Solid Propulsion Stages and a liquid propulsion-based Velocity Trimming Module (VTM) as a terminal stage |
| Space Mining | Asteroid mining is the hypothesis of extracting material from asteroids and other asteroids, including near-Earth objects. |
| Nano Satellites | Nanosatellites are loosely defined as any satellite weighing less than 10 kilograms. |
| Automatic Identification System (AIS) | Automatic identification system (AIS) is an automatic tracking system used to identify and locate ships by exchanging electronic data with other nearby ships, AIS base stations, and satellites. Satellite AIS (S-AIS) is the term used to describe when a satellite is used to detect AIS signatures. |
| Reusable launch vehicles (RLVs) | Reusable launch vehicle (RLV) means a launch vehicle that is designed to return to Earth substantially intact and therefore may be launched more than one time or that contains vehicle stages that may be recovered by a launch operator for future use in the operation of a substantially similar launch vehicle. |
| Apogee | The point in an elliptical satellite orbit which is farthest from the surface of the earth. Geosynchronous satellites which maintain circular orbits around the earth are first launched into highly elliptical orbits with apogees of 22,237 miles. |
Research Methodology
Mordor Intelligence follows a four-step methodology in all our reports.
- Step-1: Identify Key Variables: In order to build a robust forecasting methodology, the variables and factors identified in Step-1 are tested against available historical market numbers. Through an iterative process, the variables required for market forecast are set and the model is built on the basis of these variables.
- Step-2: Build a Market Model: Market-size estimations for the historical and forecast years have been provided in revenue and volume terms. For sales conversion to volume, the average selling price (ASP) is kept constant throughout the forecast period for each country, and inflation is not a part of the pricing.
- Step-3: Validate and Finalize: In this important step, all market numbers, variables and analyst calls are validated through an extensive network of primary research experts from the market studied. The respondents are selected across levels and functions to generate a holistic picture of the market studied.
- Step-4: Research Outputs: Syndicated Reports, Custom Consulting Assignments, Databases & Subscription Platforms.


