
Market Overview
| Study Period | 2021 - 2031 |
|---|---|
| Forecast Data Period | 2026 - 2031 |
| Base Year Market Size (2025) | USD 3.92 Billion |
| Market Size (2026) | USD 4.11 Billion |
| Market Size (2031) | USD 5.12 Billion |
| Growth Rate (2026 - 2031) | 4.85 % |
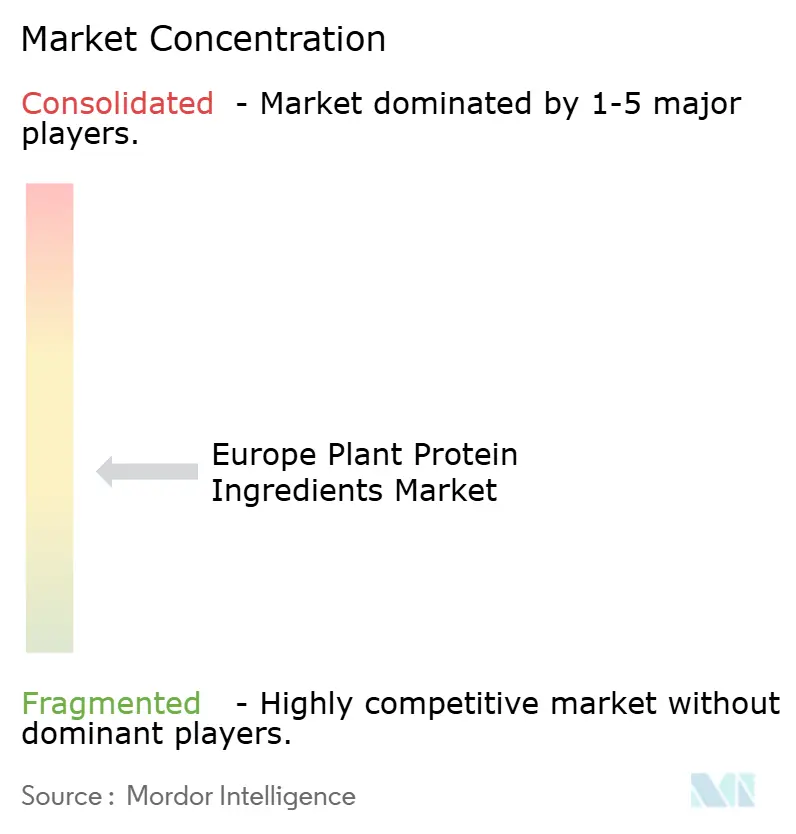
| Market Concentration | Medium |
Major Players *Disclaimer: Major Players sorted in no particular order Image © Mordor Intelligence. Reuse requires attribution under CC BY 4.0. | |
Europe Plant Protein Ingredients Market Analysis by Mordor Intelligence
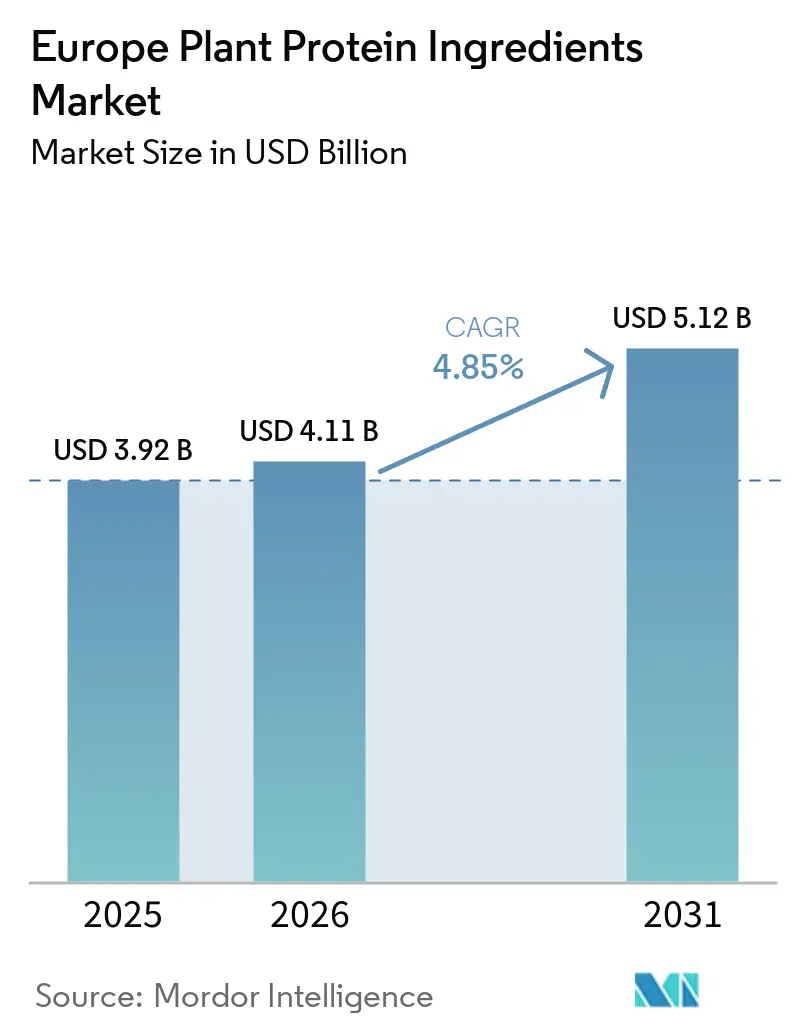
The Europe plant protein ingredients market size is projected to be USD 3.92 billion in 2025, USD 4.11 billion in 2026, and reach USD 5.12 billion by 2031, growing at a CAGR of 4.85% from 2026 to 2031. The Europe plant protein ingredients market is moving toward specialty isolates, textured proteins, and locally sourced pulse inputs as retailers and food producers place greater weight on sustainability and reformulation. Plant-based food retail across Europe’s 6 largest markets reached EUR 16.30 billion in 2025 and increased 5.10% from the prior year, broadening the customer base for ingredient suppliers beyond specialist brands. Procurement decisions increasingly reflect supply security, ingredient traceability, and the ability to reduce dependence on imported soy. The Europe plant protein ingredients market also faces a cost gap against conventional proteins, which limits use in price-sensitive products while encouraging investment in efficient regional processing.
Key Report Takeaways
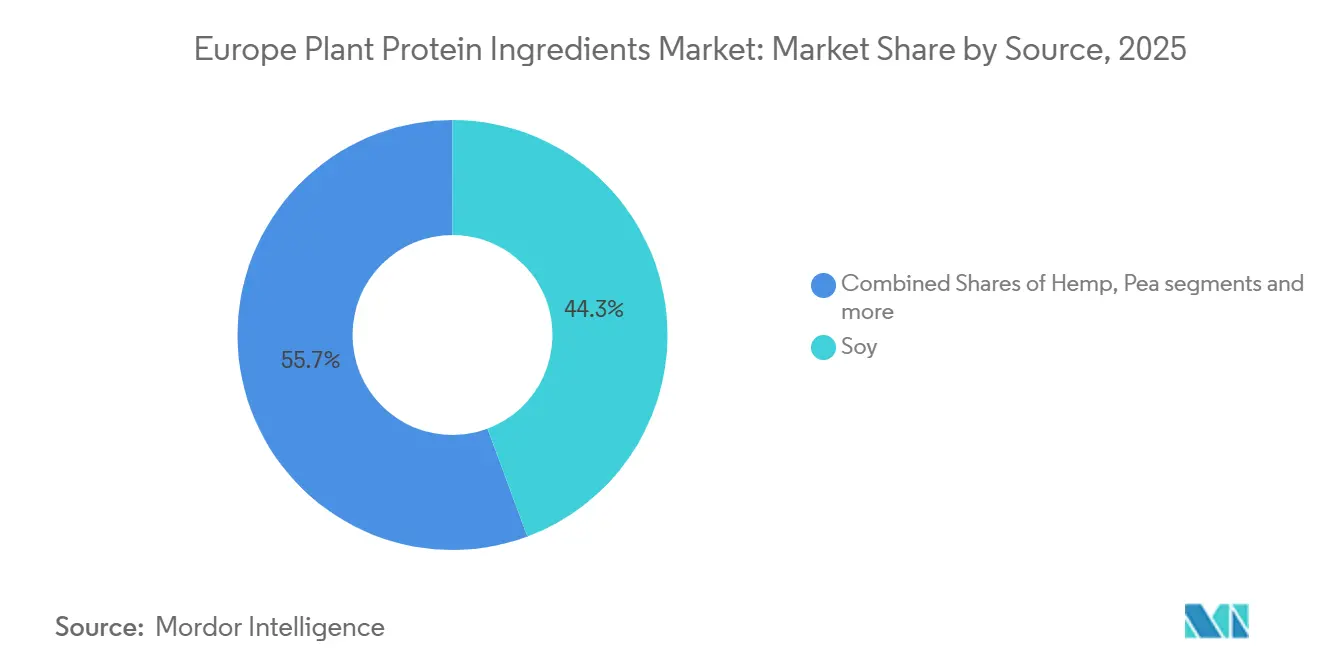
- By source, soy held 44.32% of Europe plant protein ingredient demand in 2025, while pea protein is forecast to grow at a 5.68% CAGR through 2031.
- By form, isolates accounted for 56.42% of Europe plant protein ingredient demand in 2025, while textured and hydrolyzed proteins are forecast to grow at a 6.11% CAGR through 2031.
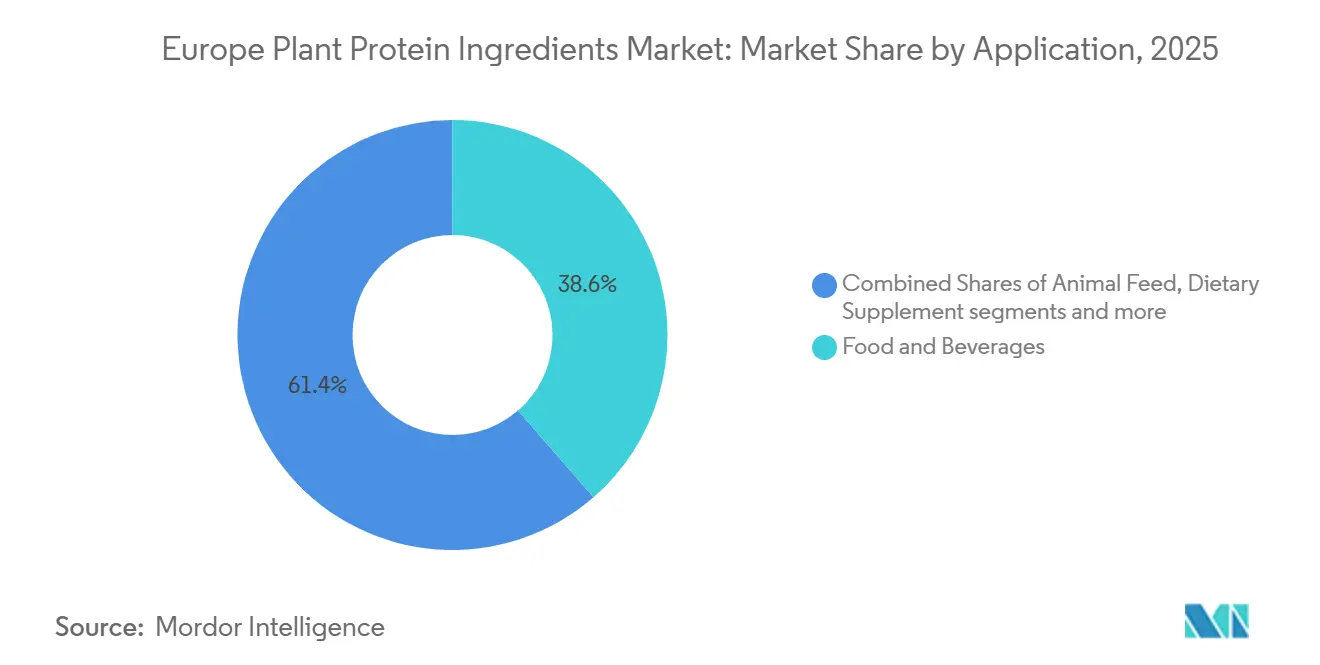
- By application, food and beverages held 38.62% of Europe plant protein ingredient demand in 2025, while dietary supplements and sports nutrition are forecast to grow at a 5.85% CAGR through 2031.
- By geography, Germany held 41.28% of Europe plant protein ingredient demand in 2025, while France is forecast to grow at a 6.21% CAGR through 2031.
Note: Market size and forecast figures in this report are generated using Mordor Intelligence’s proprietary estimation framework, updated with the latest available data and insights as of January 2026.
Europe Plant Protein Ingredients Market Trends and Insights
Drivers Impact Analysis*
| Driver | (~) % Impact on CAGR Forecasts | Geographic Relevance | Impact Timeline |
|---|---|---|---|
| Rising adoption of vegan and flexitarian diets | +1.3% | Germany, UK, France, Netherlands | Short term (≤ 2 years) |
| Growing demand for plant-based meat and dairy alternatives | +1.0% | Germany, France, Italy, Spain, spillover to Poland and Sweden | Medium term (2-4 years) |
| Strong demand for clean-label and minimally processed ingredients | +0.7% | Germany, Netherlands, UK | Medium term (2-4 years) |
| Expansion of plant-based food and beverage product launches | +0.5% | Global, strongest in APAC core and Germany | Short term (≤ 2 years) |
| Growing investment in plant protein extraction and processing technologies | +0.6% | France, Netherlands, Belgium, research clusters in Germany and the Nordics | Long term (≥ 4 years) |
| Increasing demand for sustainable and lower-impact protein sources | +0.4% | Global, strongest policy pull in Germany and the Nordics | Long term (≥ 4 years) |
| Source: Mordor Intelligence | |||
Rising Adoption of Vegan and Flexitarian Diets
A more durable dietary shift is supporting the Europe plant protein ingredients market. A survey of 4,827 adults found that 39% of German adults and 31% of UK adults identified as flexitarians in late 2024. The same research found that 51% of combined respondents intended to increase plant-based consumption[1]. Flexitarian consumers tend to compare price and quality closely, so they often choose reformulated conventional products rather than dedicated plant-based brands. This pattern increases the use of isolates and textured formats in mainstream food products. In 2025, 60% of German respondents and 56% of United Kingdom respondents said they consumed plant-based products at least monthly.
Growing Demand for Plant-Based Meat and Dairy Alternatives
Plant-based meat and dairy alternatives are increasing demand for functional proteins in the Europe plant protein ingredients market. France recorded 16.8% volume growth in plant-based meat in 2025 as prices declined. Germany’s plant-based milk category represented 9.2% of all milk sold, and private-label products represented 60% of plant milk volumes. In the Europe plant protein ingredients market, private-label growth supports steady demand for mid-grade concentrates and can increase throughput for specialized suppliers. Roquette introduced NUTRALYS® T WHEAT 600L in June 2025, its first textured wheat protein with more than 60% protein content for chicken-style alternatives. Food producers are placing more value on ingredients that help recreate the texture and eating experience of animal products.
Strong Demand for Clean-Label and Minimally Processed Ingredients
Clean-label requirements are shaping formulation choices across the Europe plant protein ingredients market. Roquette cited an Innova Trends Survey that identified protein as a leading food and beverage theme for 2026, with nearly 60% of consumers globally seeking to increase protein intake. Food and beverage launches with protein and weight-management claims grew 29% during 2024 and 2025 compared with the preceding period. Formulators have often relied on flavor masking systems when high protein functionality and a simple label were both required. Roquette launched NUTRALYS® Pea 850F in February 2026 to reduce vegetal off-notes without processing aids. The product can be labeled simply as pea protein isolate, which is relevant for beverages and dairy alternatives where ingredient-list simplicity matters.
Growing Investment in Plant Protein Extraction and Processing Technologies
Processing investment is strengthening the production base for the Europe plant protein ingredients market. Elian secured EUR 40 million, equivalent to USD 46 million, in September 2026 as part of a EUR 300 million, equivalent to USD 344.5 million, investment in its Port of Barcelona facility. The facility targets more than 100,000 tonnes of annual protein derivative capacity by 2028. The ECONEXT consortium is developing dry fractionation technology that may lower energy use and support greater use of yellow peas and faba beans grown in Europe. Research from VTT Finland reported a dry extrusion-based faba bean separation process with 71%-77% protein content and 60%-85% yield[2]. These developments place greater emphasis on process efficiency and regional raw material supply.
Restraints Impact Analysis*
| Restraint | (~) % Impact on CAGR Forecasts | Geographic Relevance | Impact Timeline |
|---|---|---|---|
| Higher Production Costs Compared With Conventional Protein Ingredients | -1.2% | Germany, Netherlands, Belgium, where energy and labor costs are highest | Medium term (2-4 years) |
| Sensory Limitations, Including Taste, Texture, and Mouthfeel | -0.9% | Spain and UK, where price parity with conventional meat and dairy remains distant | Short term (≤ 2 years) |
| Competition Among Soy, Pea, Wheat, Rice, Potato, and Other Plant Proteins | -0.5% | Netherlands, Belgium, France, where intra-European competition is most intense | Medium term (2-4 years) |
| Consumer Concerns Regarding Highly Processed Plant-Based Products | -0.6% | UK, Germany, Netherlands, where processing skepticism is highest | Short term (≤ 2 years) |
| Source: Mordor Intelligence | |||
Higher Production Costs Compared With Conventional Protein Ingredients
Production costs remain a material restraint for the Europe plant protein ingredients market. Commercial-scale soy protein isolate facilities with ultrafiltration and spray-drying capabilities require EUR 50 million-EUR 100 million in capital expenditure. This entry threshold can limit new processing capacity and slow competitive cost reductions. European soy and pea isolates traded at EUR 4,000-EUR 8,000 per metric tonne, creating a premium over conventional proteins in cost-sensitive uses. Domestic legume cultivation and dry fractionation offer a route to lower feedstock and process costs over time. Processors with established local sourcing may therefore have a stronger position as these cost improvements develop.
Sensory Limitations, Including Taste, Texture, and Mouthfeel
Taste and texture remain central barriers to wider use of plant proteins. GFI Europe’s 2025 consumer research identified taste and texture as key barriers among consumers with flexitarian intentions. In Germany, 37% of plant-based meat buyers said they would be more likely to buy an alternative if it closely resembled meaty texture. A further 52% of German adults preferred dairy alternatives without processed ingredients such as emulsifiers, according to Agriculture and Agri-Food Canada[3]. Fraunhofer researchers showed in 2025 that rapeseed protein from the EthaNa® process could suit burger patties and pasta applications. Beverage and protein bar applications can adopt substitutes sooner than structured meat alternatives because their texture requirements are less demanding.
*Our forecasts treat driver/restraint impacts as directional, not additive. The impact forecasts reflect baseline growth, mix effects, and variable interactions.
Segment Analysis
By Source: Soy Remains Established While Pea Gains Volume
Soy held 44.32% of the Europe plant protein ingredients market share in 2025, supported by established formulation systems and long-term supply arrangements. Pea protein recorded the fastest source-level growth outlook at a 5.68% CAGR through 2031. European yellow and green peas do not carry the same deforestation exposure as imported soy under the EU Deforestation Regulation, which added a reported 10%-15% restructuring cost burden to EU soy supply chains in 2024 and 2025. This difference is encouraging reformulation toward pea isolates and concentrates in Germany, France, and the Netherlands. The shift is particularly relevant in meat alternatives and dairy beverages where non-GMO and clean-label claims have commercial value.
Wheat protein remains important in bakery and savory products, while rice protein is gaining attention in sports nutrition and dairy alternatives because of its hypoallergenic profile. Hemp and potato proteins remain smaller niche sources. Rapeseed protein has gained novel food recognition, adding a European non-GMO source to the available ingredient pool. Suppliers that can provide traceable pea and faba bean proteins at competitive prices can benefit as reformulation cycles progress.

By Form: Isolates Hold Value While Textured Proteins Grow Faster
Isolates accounted for 56.42% of European plant protein ingredient demand in 2025. Their position reflects high protein content and solubility requirements in beverages, dairy alternatives, and clinical nutrition. These applications often require protein content above 85%. Roquette launched NUTRALYS Pea 850F in February 2026 to reduce vegetal notes without processing aids and help manufacturers use simpler ingredient declarations. Isolates also benefit from demand for high-protein, low-volume formats among GLP-1 medication users.
Concentrates remain cost-effective ingredients for animal feed, bakery, and mid-range food products. Textured and hydrolyzed proteins are projected to grow at a 6.11% CAGR through 2031, the fastest rate among form categories. The Europe plant protein ingredients market size for this form benefits from high-moisture extrusion used in structured meat alternatives. is developing dry-fractionated concentrates designed for high-moisture extrusion at commercial scale. ISPT Roquette’s NUTRALYS T PEA 700XC has 70% protein content and requires limited hydration.
By Application: Food and Beverages Lead While Sports Nutrition Expands
Food and beverages accounted for 38.62% of European plant protein ingredient demand in 2025. The category includes bakery, confectionery, meat alternatives, dairy alternatives, beverages, and infant nutrition. Dairy alternatives are expanding faster than meat alternatives in several markets and can reach consumers at lower price premiums. In Germany, plant-based milk represented 9.2% of all milk sold in 2025. Infant and early-life nutrition provides a high-value application because amino acid profile and digestibility requirements are exacting.
Dietary supplements and sports nutrition are forecast to grow at a 5.85% CAGR through 2031. The Europe plant protein ingredients market size in this application is supported by a wider group of active adults, older consumers, and general wellness users. A 2026 peer-reviewed review found that pea-rice blends can approach whey performance when their complementary amino acid profiles are combined appropriately. Animal feed remains an important volume application and relies heavily on soy protein concentrates. Personal care and pharmaceuticals are smaller, higher-margin uses where specific protein fractions can command premium positioning.
Geography Analysis
Germany held 41.28% of the Europe plant protein ingredients market share in 2025 and remains the region’s largest demand center. Its plant-based food retail volume increased 6.2% in 2025, while tofu, tempeh, and seitan volumes rose 30%, and plant-based milk represented 9.2% of all milk sold. GFI EUROPE Vegetable protein ingredient volumes in Germany were projected to grow at a 6.1% CAGR through 2029 as the market matured. The United Kingdom remains an important demand hub because of its large processed food manufacturing base. Greater sales through discount channels are raising formulation cost pressure.
France is forecast to grow at a 6.21% CAGR through 2031, the fastest rate among the geographic segments. Plant-based retail in France reached EUR 572 million in 2025, an 11% increase from the prior year, while plant-based meat volume rose 16.8% as prices fell. France’s PROTEIN 2030 program supports domestic legume development and may improve the traceability and cost position of French processors. Italy recorded 4.5% plant-based retail value growth in 2025, while Spain recorded 7.7% growth and plant-based milk approached price parity with conventional dairy in some retail formats.
Sweden, Poland, Belgium, and the Netherlands form an important second tier of demand and processing activity. Belgium hosts Cosucra Groupe Warcoing’s pea protein operations, while Sweden’s market favors organic and sustainability-certified proteins. Poland offers growth from a lower penetration base as flexitarian adoption broadens in urban areas. The Netherlands recorded a slight decline in plant-based retail sales in 2025 but remained Europe’s third-highest per-capita plant-based spend market and a critical pea and soy processing node. This node remains important to the Europe plant protein ingredients market as suppliers seek regional processing capacity.
Competitive Landscape
The Europe plant protein ingredients market has a moderate concentration because global ingredient companies, regional pulse processors, and specialist distributors operate alongside one another. Roquette Frères holds a leading position in pea protein isolate output through wet fractionation facilities in France and Belgium. Its NUTRALYS® range covers pea, wheat, rice, and fava bean proteins. Roquette’s Shift & Lead plan, introduced in January 2026, prioritizes specialty protein and fiber revenue, operating performance, and cash generation. Its first-half 2026 results showed higher protein volumes than the prior year.
Cosucra Groupe Warcoing and Ingredion’s Netherlands operations compete in functional pea protein grades. ADM and IFF have broad positions across soy and other protein formats because of their integrated supply networks. BENEO is investing EUR 50 million in faba bean processing in Rhineland-Palatinate, Germany. Roquette’s February 2026 launch of NUTRALYS® Pea 850F adds a sensory-focused isolate for drinks, dairy alternatives, specialized nutrition, and high-protein products. Its June 2025 launches of textured wheat and pea proteins extend its position in meat analog and hybrid product development.
Rapeseed protein concentrate gained EU novel food status, and EFSA issued a positive opinion on soy leghemoglobin in November 2024, pending a final European Commission decision. Faba bean protein is moving from pilot work toward commercial use at multiple European sites. ExSeed commissioned Europe’s first sunflower protein isolate pilot facility in July 2025. Smaller entrants in the Europe plant protein ingredients market compete through processing capability, regulatory progress, and application-specific performance.
Europe Plant Protein Ingredients Industry Leaders
-
Archer Daniels Midland Company
-
Ingredion Incorporated
-
International Flavors & Fragrances Inc.
-
Kerry Group PLC
-
Südzucker AG
- *Disclaimer: Major Players sorted in no particular order
Recent Industry Developments
- February 2026: Roquette launched NUTRALYS® Pea 850F, a sensory-optimized pea protein isolate engineered to reduce vegetal off-notes without processing aids, enabling simple "pea protein isolate" ingredient declarations, targeted applications include ready-to-drink beverages, dairy alternatives, specialized nutrition, and high-protein formats for GLP-1 dietary positioning.
- June 2025: ACI Group announced a strategic distribution agreement with IFF, securing the rights to distribute IFF’s soy and pea protein ingredients in the UK and Ireland. This long-term partnership enhanced ACI’s role in the traditional meat and plant-based food markets, providing customers with access to a comprehensive range of non-GMO protein solutions supported by advanced technical expertise.
- March 2025: ACI Group announced a new range of plant-based proteins, expanding its portfolio to address the increasing demand for sustainable and functional ingredients in food manufacturing. The new offerings included a wide variety of pea, soy, and wheat proteins, as well as a blended plant protein concentrate designed for diverse product formulations.
Europe Plant Protein Ingredients Market Report Scope
Hemp Protein, Pea Protein, Potato Protein, Rice Protein, Soy Protein, Wheat Protein are covered as segments by Protein Type. Animal Feed, Food and Beverages, Personal Care and Cosmetics, Supplements are covered as segments by End User. Belgium, France, Germany, Italy, Netherlands, Russia, Spain, Turkey, United Kingdom are covered as segments by Country. By Source
| Soy |
| Pea |
| Wheat |
| Rice |
| Potato |
| Hemp |
| Others |
By Form
| Concentrates |
| Isolates |
| Textured/Hydrolyzed |
By Application
| Food and Beverages | Bakery and Confectionery |
| Meat Analogs and Extenders | |
| Dairy Alternatives | |
| Savoury Snacks and Bars | |
| Beverages | |
| Infant and Early-Life Nutrition | |
| Dietary Supplements and Sports Nutrition | |
| Animal Feed | |
| Personal Care and Cosmetics | |
| Pharmaceuticals and Clinical Nutrition |
By Geography
| Germany |
| United Kingdom |
| France |
| Italy |
| Spain |
| Netherlands |
| Sweden |
| Poland |
| Belgium |
| Rest of Europe |
| By Source | Soy | |
| Pea | ||
| Wheat | ||
| Rice | ||
| Potato | ||
| Hemp | ||
| Others | ||
| By Form | Concentrates | |
| Isolates | ||
| Textured/Hydrolyzed | ||
| By Application | Food and Beverages | Bakery and Confectionery |
| Meat Analogs and Extenders | ||
| Dairy Alternatives | ||
| Savoury Snacks and Bars | ||
| Beverages | ||
| Infant and Early-Life Nutrition | ||
| Dietary Supplements and Sports Nutrition | ||
| Animal Feed | ||
| Personal Care and Cosmetics | ||
| Pharmaceuticals and Clinical Nutrition | ||
| By Geography | Germany | |
| United Kingdom | ||
| France | ||
| Italy | ||
| Spain | ||
| Netherlands | ||
| Sweden | ||
| Poland | ||
| Belgium | ||
| Rest of Europe | ||
Market Definition
- End User - The Protein Ingredients Market operates on a B2B basis. Food, Beverages, Supplements, Animal Feed, and Personal Care & Cosmetic manufacturers are considered to be end-consumers in the market studied. The scope excludes manufacturers buying liquid/dry whey to be used for application as a binding agent or thickener or other non-protein applications.
- Penetration Rate - Penetration Rate is defined as the percentage of Protein-Fortified End User Market Volume in the Overall End User Market Volume.
- Average Protein Content - Average protein content is the average protein content present per 100 g of product manufactured by all end-user companies considered under the scope of this report.
- End User Market Volume - End-user market volume is the consolidated volume of all types and forms of end-user products in the country or region.
| Keyword | Definition |
|---|---|
| Alpha-lactalbumin (α-Lactalbumin) | It is a protein that regulates the production of lactose in the milk of almost all mammalian species. |
| Amino acid | It is an organic compound that contains both amino and carboxylic acid functional groups, which are required for the synthesis of body protein and other important nitrogen-containing compounds, such as creatine, peptide hormones, and some neurotransmitters. |
| Blanching | It is the process of briefly heating vegetables with steam or boiling water. |
| BRC | British Retail Consortium |
| Bread improver | It is a flour-based blend of several components with specific functional properties designed to modify dough characteristics and give quality attributes to bread. |
| BSF | Black Soldier Fly |
| Caseinate | It is a substance produced by adding an alkali to acid casein, a derivative of casein. |
| Celiac disease | Celiac disease is an immune reaction to eating gluten, a protein found in wheat, barley, and rye. |
| Colostrum | It is a milky fluid that’s released by mammals that have recently given birth before breast milk production begins. |
| Concentrate | It is the least processed form of protein and has a protein content ranging from 40-90% by weight. |
| Dry protein basis | It refers to the percentage of "pure protein" present in a supplement after the water in it is completely removed through heat. |
| Dry whey | It is the product resulting from drying fresh whey which has been pasteurized and to which nothing has been added as a preservative. |
| Egg protein | It is a mixture of individual proteins, including ovalbumin, ovomucoid, ovoglobulin, conalbumin, vitellin, and vitellenin. |
| Emulsifier | It is a food additive that facilitates the blending of foods that are immiscible with one another, such as oil and water. |
| Enrichment | It is the process of addition of micronutrients that are lost during the processing of the product. |
| ERS | Economic Research Service of the USDA |
| Extrusion | It is the process of forcing soft mixed ingredients through an opening in a perforated plate or die designed to produce the required shape. The extruded food is then cut to a specific size by blades. |
| Fava | Also known as Faba, it is another word for yellow split beans. |
| FDA | Food and Drug Administration |
| Flaking | It is a process in which typically a cereal grain (like corn, wheat, or rice) is broken down into grits, cooked with flavors and syrups, and then pressed into flakes between cooled rollers. |
| Foaming agent | It is a food ingredient that makes it possible to form or maintain a uniform dispersion of a gaseous phase in a liquid or solid food. |
| Foodservice | It refers to the part of the food industry which includes businesses, institutions, and companies which prepare meals outside the home. It includes restaurants, school and hospital cafeterias, catering operations, and many other formats. |
| Fortification | It is the deliberate addition of micronutrients that are not found in them naturally or which are lost during processing, to improve a food product's nutritional value. |
| FSANZ | Food Standards Australia New Zealand |
| FSIS | Food Safety and Inspection Service |
| FSSAI | Food Safety and Standards Authority of India |
| Gelling agent | It is an ingredient that functions as a stabilizer and thickener to provide thickening without stiffness through the formation of gel. |
| GHG | Greenhouse Gas |
| Gluten | It is a family of proteins found in grains, including wheat, rye, spelt, and barley. |
| Hemp | It is a botanical class of Cannabis sativa cultivars grown specifically for industrial or medicinal use. |
| Hydrolysate | It is a form of protein manufactured by exposing the protein to enzymes that can partially break the bonds between the protein's amino acids and break down large, complicated proteins into smaller pieces. Its processing makes it easier and quicker to digest. |
| Hypoallergenic | It refers to a substance that causes fewer allergic reactions. |
| Isolate | It is the purest and most processed form of protein which has undergone separation to obtain a pure protein fraction. It typically contains ≥ 90% of protein by weight. |
| Keratin | It is a protein that helps form hair, nails, and the outer layer of skin. |
| Lactalbumin | It is the albumin contained in milk and obtained from whey. |
| Lactoferrin | It is an iron‑binding glycoprotein that is present in the milk of most mammals. |
| Lupin | It is the yellow legume seeds of the genus Lupinus. |
| Millenial | Also known as Generation Y or Gen Y, it refers to the people born from 1981 to 1996. |
| Monogastric | It refers to an animal with a single-compartmented stomach. Examples of monogastric include humans, poultry, pigs, horses, rabbits, dogs, and cats. Most monogastric are generally unable to digest much cellulose food materials such as grasses. |
| MPC | Milk protein concentrate |
| MPI | Milk protein isolate |
| MSPI | Methylated soy protein isolate |
| Mycoprotein | Mycoprotein is a form of single-cell protein, also known as fungal protein, derived from fungi for human consumption. |
| Nutricosmetics | It is a category of products and ingredients that act as nutritional supplements to care for skin, nails, and hair natural beauty. |
| Osteoporosis | It is a medical condition in which the bones become brittle and fragile from loss of tissue, typically as a result of hormonal changes, or deficiency of calcium or vitamin D. |
| PDCAAS | Protein digestibility-corrected amino acid score (PDCAAS) is a method of evaluating the quality of a protein based on both the amino acid requirements of humans and their ability to digest it. |
| Per-capita consumption of animal protein | It is the average amount of animal protein (such as milk, whey, gelatin, collagen, and egg proteins) that is readily available for consumption by each person in an actual population. |
| Per-capita consumption of plant protein | It is the average amount of plant protein (such as soy, wheat, pea, oat, and hemp proteins) that is readily available for consumption by each person in an actual population. |
| Quorn | It is a microbial protein manufactured using mycoprotein as an ingredient, in which the fungus culture is dried and mixed with egg albumen or potato protein, which acts as a binder, and then is adjusted in texture and pressed into various forms. |
| Ready-to-Cook (RTC) | It refers to food products that include all of the ingredients, where some preparation or cooking is required through a process that is given on the package. |
| Ready-to-Eat (RTE) | It refers to a food product prepared or cooked in advance, with no further cooking or preparation required before being eaten. |
| RTD | Ready-to-Drink |
| RTS | Ready-to-Serve |
| Saturated fat | It is a type of fat in which the fatty acid chains have all single bonds. It is generally considered unhealthy. |
| Sausage | It is a meat product made of finely chopped and seasoned meat, which may be fresh, smoked, or pickled and which is then usually stuffed into a casing. |
| Seitan | It is a plant-based meat substitute made out of wheat gluten. |
| Softgel | It is a gelatin-based capsule with a liquid fill. |
| SPC | Soy protein concentrate |
| SPI | Soy protein isolate |
| Spirulina | It is a biomass of cyanobacteria that can be consumed by humans and animals. |
| Stabilizer | It is an ingredient added to food products to help maintain or enhance their original texture, and physical and chemical characteristics. |
| Supplementation | It is the consumption or provision of concentrated sources of nutrients or other substances that are intended to supplement nutrients in the diet and is intended to correct nutritional deficiencies. |
| Texturant | It is a specific type of food ingredient that is used to control and alter the mouthfeel and texture of food and beverage products. |
| Thickener | It is an ingredient that is used to increase the viscosity of a liquid or dough and make it thicker, without substantially changing its other properties. |
| Trans fat | Also called trans-unsaturated fatty acids or trans fatty acids, it is a type of unsaturated fat that naturally occurs in small amounts in meat. |
| TSP | Textured soy protein |
| TVP | Textured vegetable protein |
| WPC | Whey protein concentrate |
| WPI | Whey protein isolate |
Research Methodology
Mordor Intelligence follows a four-step methodology in all our reports.
- Step-1: Identify Key Variables: The quantifiable key variables (industry and extraneous) pertaining to the specific product segment and country are selected from a group of relevant variables & factors based on desk research & literature review; along with primary expert inputs. These variables are further confirmed through regression modeling (wherever required).
- Step-2: Build a Market Model: In order to build a robust forecasting methodology, the variables and factors identified in Step-1 are tested against available historical market numbers. Through an iterative process, the variables required for market forecast are set and the model is built on the basis of these variables.
- Step-3: Validate and Finalize: In this important step, all market numbers, variables and analyst calls are validated through an extensive network of primary research experts from the market studied. The respondents are selected across levels and functions to generate a holistic picture of the market studied.
- Step-4: Research Outputs: Syndicated Reports, Custom Consulting Assignments, Databases & Subscription Platforms


