
Market Overview
| Study Period | 2020 - 2032 |
|---|---|
| Forecast Data Period | 2027 - 2032 |
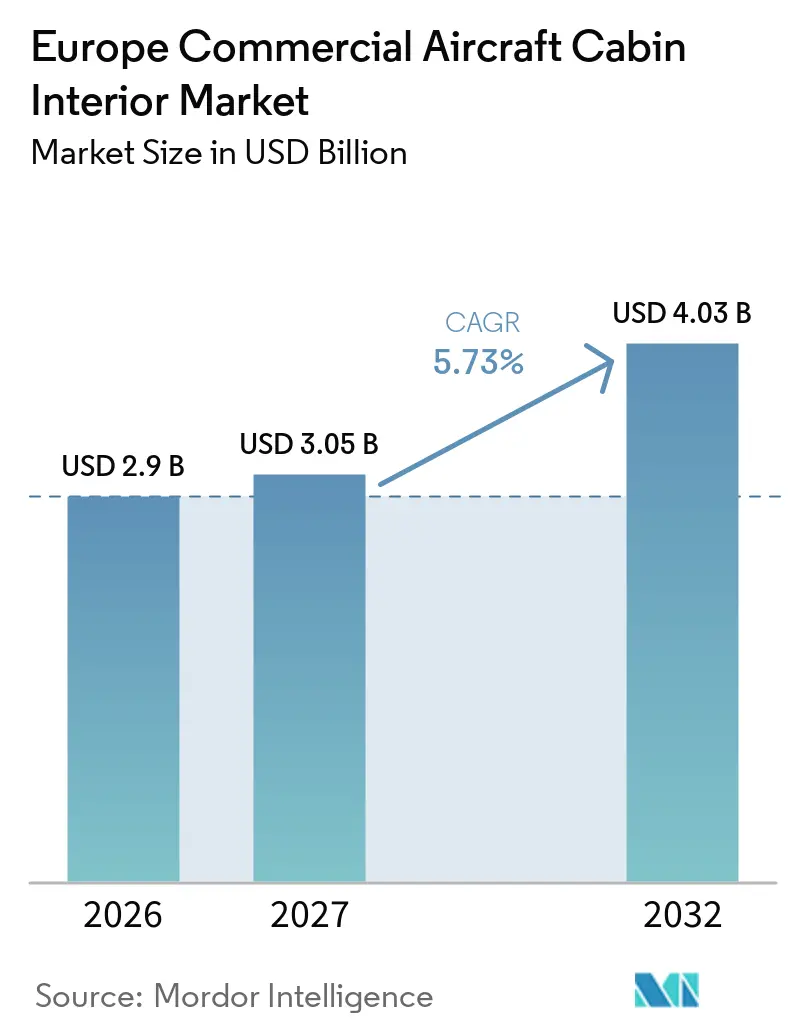
| Base Year Market Size (2026) | USD 2.9 Billion |
| Market Size (2027) | USD 3.05 Billion |
| Market Size (2032) | USD 4.03 Billion |
| Growth Rate (2027 - 2032) | 5.73 % |
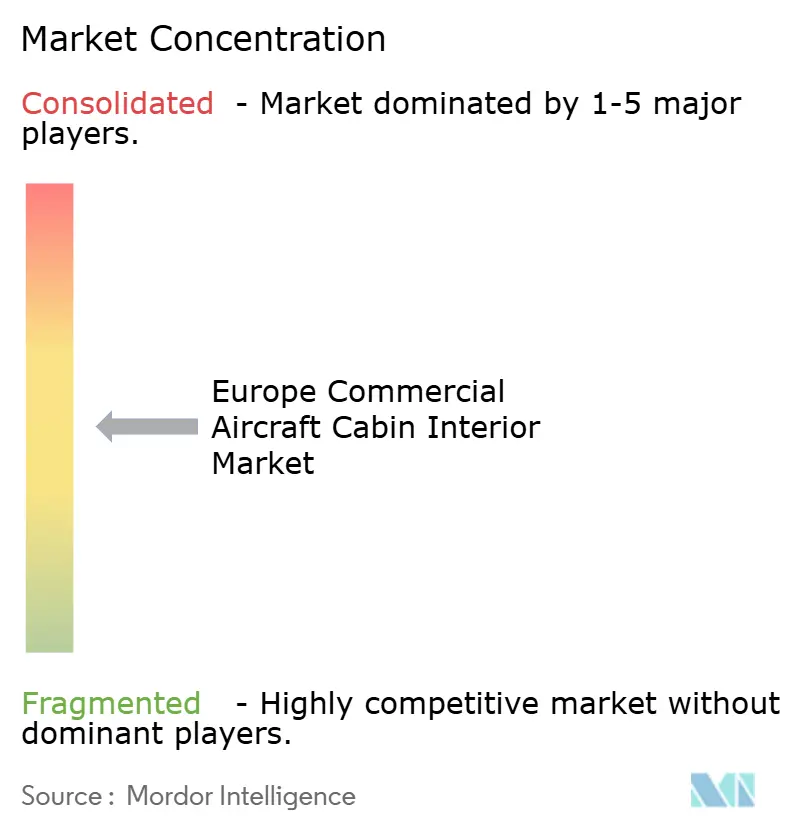
| Market Concentration | Medium |
Major Players *Disclaimer: Major Players sorted in no particular order Image © Mordor Intelligence. Reuse requires attribution under CC BY 4.0. | |
Europe Commercial Aircraft Cabin Interior Market Analysis by Mordor Intelligence
The Europe commercial aircraft cabin interior market size was valued at USD 2.90 billion in 2026 and is forecast to grow from USD 3.05 billion in 2027 to USD 4.03 billion by 2032, registering a 5.73% CAGR between 2027 and 2032. Retrofit, refurbishment, and maintenance work support demand as carriers renew their cabins and take delivery of Airbus aircraft. The cabin is increasingly tied to passenger yield, especially where airlines add premium seating and improve long-haul products. The A321XLR supports sophisticated interiors and differentiated layouts on longer single-aisle routes. Connectivity, lighter materials, and certification requirements shape equipment selection and program timing. The market benefits as carriers extend fleet life through cabin upgrades.
Key Report Takeaways
- By product type, seating held 29.90% of revenue in 2026, while IFEC is forecast to grow at a 7.55% CAGR through 2032.
- By aircraft type, narrowbody aircraft accounted for 48.60% of the Europe commercial aircraft cabin interior market size in 2026, while widebody aircraft is projected to expand at a 6.66% CAGR through 2032.
- By cabin class, economy class held 66.10% of revenue in 2026, while premium economy class is forecast to grow at a 6.79% CAGR through 2032.
- By fit type, OEM-fit interiors accounted for 56.72% of revenue in 2026, while aftermarket interiors are projected to expand at a 6.48% CAGR through 2032.
- By material, composites held 41.50% of revenue in 2026, while advanced thermoplastics are forecast to grow at a 6.85% CAGR through 2032.
- By geography, the United Kingdom accounted for 23.81% of revenue in 2026, while France is projected to expand at a 7.02% CAGR through 2032.
Note: Market numbers in this report are based on Mordor Intelligence's proprietary estimation framework, which combines nine months of actuals with Q4 projections for base year 2026.
Europe Commercial Aircraft Cabin Interior Market Trends and Insights
Drivers Impact Analysis*
| Driver | (~) % Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
|---|---|---|---|
| Premium cabin retrofit monetization accelerates growth | +1.80% | UK, Germany, France, Spain | Short term (≤ 2 years) |
| European fleet renewal supports interior demand | +1.50% | Pan-European, concentrated in Western Europe | Medium term (2-4 years) |
| Connected cabin revenue drives IFC adoption | +1.20% | UK, Germany, Scandinavia, Rest of Europe | Short term (≤ 2 years) |
| Sustainability push accelerates lightweight interior adoption | +0.80% | Germany, France, Netherlands | Medium term (2-4 years) |
| Accessibility requirements drive cabin reconfiguration demand | +0.40% | EU-wide | Long term (≥ 4 years) |
| Widebody midlife retrofits expand upgrade opportunities | +0.60% | UK, Germany, France | Medium term (2-4 years) |
| Source: Mordor Intelligence | |||
Premium Cabin Retrofit Monetization Accelerates Growth
Premium cabin retrofits are expanding aftermarket opportunities for European aircraft interior suppliers beyond new aircraft deliveries. Lufthansa is scheduled to upgrade eight A380 aircraft, each with 68 Thompson Aero business-class seats featuring direct aisle access, Bluetooth connectivity, and 18-inch Panasonic entertainment screens. The first upgraded aircraft, D-AIMC, returned to service in April 2026, while the remaining fleet is expected to be completed by mid-2027.[1] British Airways announced a major A380 cabin modernization program in October 2026, including new premium seating and entertainment systems across cabin classes. These investments will support demand for aircraft seating, in-flight entertainment (IFE), cabin modifications, and associated installation services.
European Fleet Renewal Supports Interior Demand
European aircraft fleet renewal is expected to support demand for new cabin installations and interior upgrades. Lufthansa Group reported 219 firm aircraft orders at the end of 2025, with deliveries scheduled between 2026 and 2032. These orders include A350, B787-9, A220, and A320-family aircraft, as well as other passenger and freighter aircraft types. In June 2026, easyJet received its 100th Airbus neo-family aircraft, featuring the latest Airbus Airspace cabin.[2] The airline also plans to retrofit 81 existing A320neo and A321neo aircraft with Airspace cabin enhancements. These programs will directly support demand for seating, cabin panels, lighting, accessibility features, and interior integration across European airline fleets.
Connected Cabin Revenue Drives IFC Adoption
Airline investments in passenger connectivity are expected to increase demand for aircraft modifications and cabin integration across Europe. In September 2026, SAS completed Starlink installations across all 81 Airbus A320neo aircraft in its fleet within six months. KLM introduced free in-flight Wi-Fi on European services in January 2026 through a phased rollout across A321neo, E195-E2, and selected B737-800 aircraft. Connectivity installations will create demand for aircraft-specific equipment integration, electrical modifications, and related certification and installation work. For cabin interior suppliers, opportunities will center on compatible cabin hardware, installation activities, and interior modifications rather than connectivity service revenue.
Sustainability Push Accelerates Lightweight Interior Adoption
European aircraft cabin interior suppliers are advancing lightweight, recyclable materials to support airlines' sustainability and operating efficiency objectives. Lufthansa Technik's AeroFLAX composite offers potential component-level weight reductions of up to 20% while meeting aircraft cabin flammability requirements. DIAB has developed a fully recyclable thermoplastic sandwich panel for cabin interiors that incorporates recycled production material. According to the manufacturer, its production approach can reduce manufacturing costs by up to 20% and component weight by up to 10%. These developments strengthen opportunities for qualified lightweight panels, renewable materials, and recyclable cabin structures, particularly as aircraft manufacturers and airlines prioritize material performance, compliance, and weight reduction.
Restraints Impact Analysis*
| Restraint | (~) % Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
|---|---|---|---|
| Seat supply and certification bottlenecks persist | -0.70% | Pan-European, particularly Germany, UK, France | Short term (≤ 2 years) |
| MRO capacity and labor constraints intensify | -0.60% | UK, Germany, Malta, Ireland | Short term (≤ 2 years) |
| Aircraft downtime raises cabin modification costs | -0.50% | Pan-European | Medium term (2-4 years) |
| Material certification complexity delays interior adoption | -0.40% | Pan-European | Medium term (2-4 years) |
| Source: Mordor Intelligence | |||
Seat Supply and Certification Bottlenecks Persist
Certification complexity can slow the Europe commercial aircraft cabin interior market when a new seat or revised layout needs aircraft-specific approval. EASA cabin reconfiguration guidance shows that cabin modifications must be assessed against CS-25 requirements and documented through the approved design process.[3] Premium seat programs combine bespoke mechanisms, electronics, monuments, and a particular seat pitch. Each combination can add engineering work before installation. The result is a longer path from airline specification to revenue service. Airlines may need to coordinate design, production, and maintenance organizations. This protects safety but limits the speed at which carriers can introduce new cabin products.
MRO Capacity and Labor Constraints Intensify
Limited maintenance capacity and specialist installation resources are reducing the scheduling flexibility of cabin refurbishment programs across Europe. Airbus identifies MRO slot availability as a key consideration for A350 cabin upgrades, as airlines typically seek to align installations with scheduled maintenance activities to minimize operational disruptions. In July 2026, Ryanair announced a proposed EUR 50 million (USD 56.96 million) expansion of its Shannon maintenance facility, including four additional hangar bays and an engineering training program. Such investments underscore the importance of maintenance infrastructure and skilled personnel. Competition for available maintenance slots, combined with aircraft downtime requirements, can delay cabin modification programs and increase installation costs.
*Our forecasts treat driver/restraint impacts as directional, not additive. The impact forecasts reflect baseline growth, mix effects, and variable interactions.
Segment Analysis
By Product Type: Seating Anchors Revenue as IFEC Leads Growth
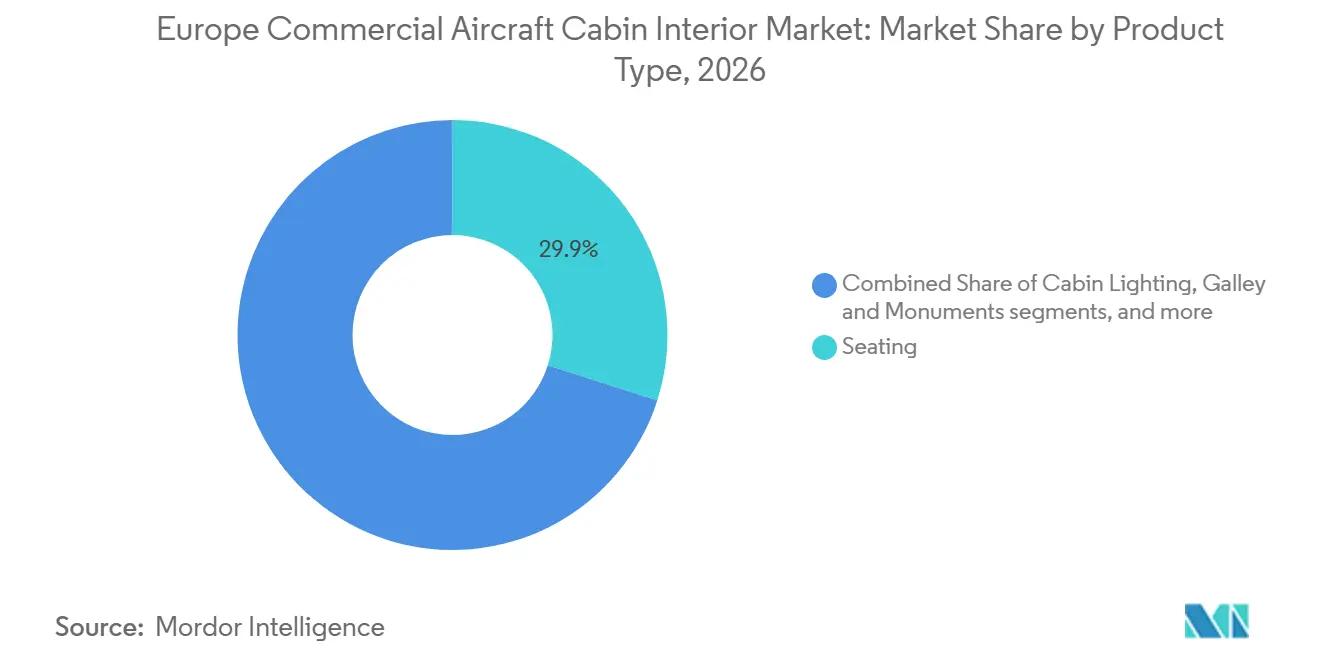
Seating is projected to account for 29.90% of revenue in the Europe commercial aircraft cabin interior market in 2026, making it the largest product category in the supplied estimates. Demand is supported by premium cabin upgrades, economy seat replacements, and new aircraft deliveries. In April 2026, Collins Aerospace announced three international airline launch customers for its Helix main-cabin seat, covering approximately 200 A320 and B737 aircraft. Lufthansa also modernized 38 A320 aircraft with Geven seats, larger overhead bins, and USB charging ports as part of a refurbishment program that began in 2025. These developments demonstrate continued investment in seating comfort, weight efficiency, and cabin modernization across OEM and aftermarket programs.
IFEC is forecast to register the fastest growth among product segments, at a 7.55% CAGR through 2032, supported by airline investments in passenger connectivity and entertainment upgrades. In September 2026, SAS completed Starlink installations across its fleet of 81 A320neo aircraft, demonstrating the scale of connectivity integration across European airline operations. IFEC installations can generate demand for onboard equipment, electrical integration, cabin modification, and certification work. Premium cabin modernization also supports demand for upgraded passenger displays and entertainment systems. However, the revenue opportunity for cabin interior suppliers is concentrated in eligible equipment and installation activities rather than ongoing connectivity subscription services.

By Aircraft Type: Narrowbody Backbone, Widebody Retrofits Gain Strategic Weight
Narrowbody aircraft are projected to account for 48.60% of Europe commercial aircraft cabin interior market revenue in 2026, reflecting their extensive deployment across short- and medium-haul airline networks. In June 2026, easyJet received its 100th A320neo-family aircraft, featuring Airbus Airspace cabin enhancements, as will future neo-platform deliveries. The airline has also announced plans to retrofit 81 existing A320neo and A321neo aircraft with Airspace improvements. Separately, Lufthansa will upgrade 38 A320 aircraft with new seating, charging facilities, and larger overhead bins. These programs support demand for narrowbody seating, lighting, cabin furnishings, and interior integration across new-delivery and refurbishment activities.
Widebody aircraft are forecast to record the fastest growth among aircraft types, at a 6.66% CAGR through 2032, supported by long-haul fleet modernization and premium cabin upgrades. Lufthansa's A380 refurbishment program covers eight aircraft, each of which will receive 68 new business-class seats, with fleet completion scheduled for mid-2027. British Airways also announced a comprehensive A380 modernization program in October 2026, covering First, Club World, World Traveler Plus, and World Traveler cabins. Widebody upgrades typically involve extensive seating, monuments, entertainment systems, and associated integration work. These large-scale refurbishment programs support aftermarket opportunities for cabin equipment manufacturers, engineering specialists, and approved modification providers.
By Cabin Class: Economy Volume Leads, Premium Economy Reshapes Airline Revenue Architecture
Economy class is projected to account for 66.10% of the Europe commercial aircraft cabin interior market revenue in 2026, making it the largest cabin-class segment in the supplied estimates. Demand is supported by high seat volumes, narrowbody fleet renewal, and periodic interior modernization. LOT Polish Airlines has selected Airbus A220 aircraft for deliveries beginning in 2027, with cabin specifications that include 18-inch-wide seats, USB-C charging, and improved overhead storage. Meanwhile, Lufthansa's A320 modernization program includes new economy seating and passenger charging facilities. Airline investments in cabin density, seat weight, durability, and passenger comfort support continued demand for economy-class interior equipment across European fleets.
Premium economy is forecast to register the fastest growth among cabin classes, at a 6.79% CAGR through 2032, supported by airline investments in differentiated long-haul passenger accommodation. Airbus identifies the installation and expansion of premium economy as important drivers of A350 cabin modernization, as airlines introduce the class or increase its share in existing layouts. Finnair completed a major A330 and A350 cabin upgrade in 2024, introducing premium economy alongside redesigned business-class and refreshed economy interiors. Premium economy installations can require new seating layouts, cabin partitions, electrical interfaces, and passenger-service modifications. These projects support demand for higher-value cabin equipment and integrated refurbishment services.
By Fit Type: OEM Deliveries Define Volume, Aftermarket Commands the Margin
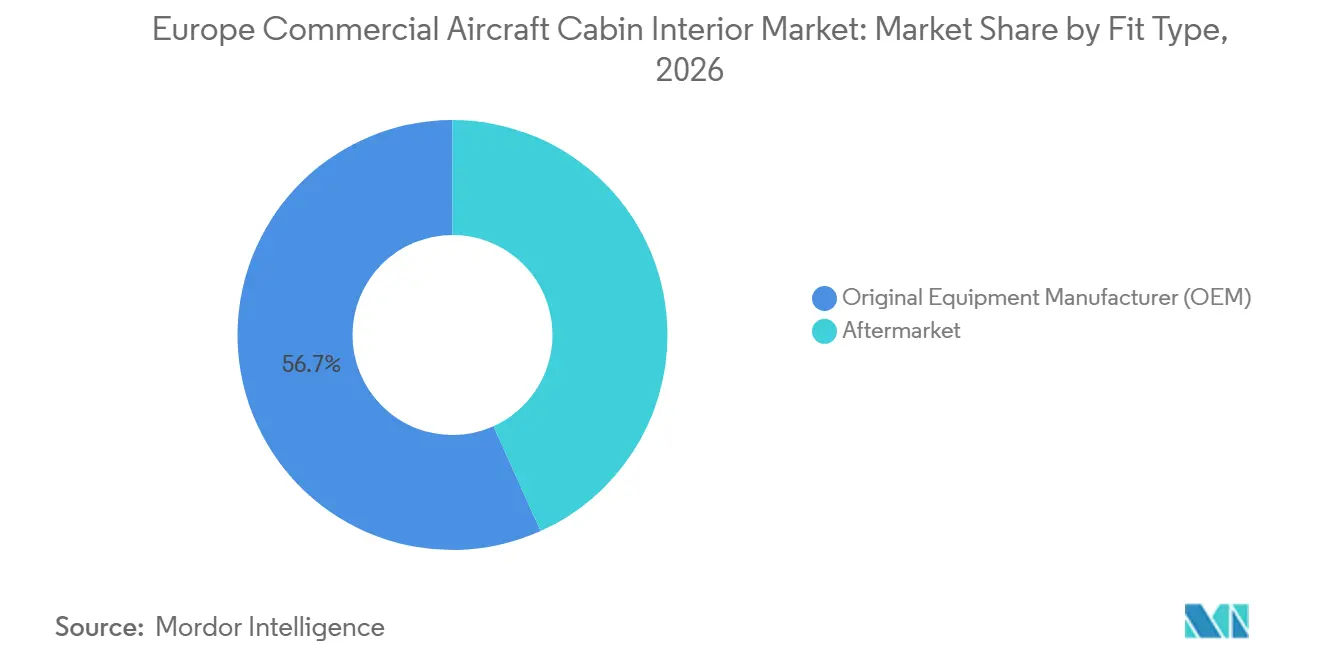
OEM-fit interiors are projected to account for 56.72% of revenue in the Europe commercial aircraft cabin interior market in 2026, supported by aircraft production and airline fleet renewal. Lufthansa Group reported 219 firm aircraft orders at the end of 2025, including seven B777-8F freighters, with deliveries scheduled between 2026 and 2032. The passenger aircraft pipeline supports future demand for seating, galleys, lavatories, lighting, and other cabin equipment. In April 2026, Safran Cabin secured an agreement to supply customized galleys and stowage for flyadeal's 10 A330neo aircraft, with production at its facility in Rokycany, Czech Republic. Such orders demonstrate opportunities for European cabin manufacturers serving global aircraft delivery programs.
Aftermarket interiors are forecast to record the fastest growth among fit types, at a 6.48% CAGR through 2032, supported by airline investments in existing aircraft cabins. Lufthansa's A380 and A320 refurbishment programs demonstrate demand for premium seating, overhead storage, and passenger service upgrades beyond new aircraft deliveries. Airbus also identifies growing A350 retrofit opportunities as in-service aircraft approach typical cabin refurbishment milestones. Aftermarket programs range from component replacements to comprehensive cabin reconfigurations that require engineering, certification, and coordination of installation. These activities support recurring demand for equipment suppliers and modification providers, although project scheduling remains dependent on component availability and maintenance capacity.
By Material: Composites Lead, Advanced Thermoplastics Drive the Next Specification Cycle
Composites are projected to account for 41.50% of material revenue in the Europe commercial aircraft cabin interior market in 2026, making them the largest material category in the supplied estimates. Their strength-to-weight characteristics support applications such as cabin panels, sidewalls, ceilings, overhead bins, and lavatory structures. Lufthansa Technik's AeroFLAX composite illustrates ongoing material innovation, offering potential component-level weight reductions of up to 20% while meeting applicable cabin flammability requirements. DIAB also supplies structural foam-core materials for aircraft interiors, supporting lightweight sandwich-panel construction. Demand for composites is supported by aircraft weight-reduction objectives, material durability requirements, and the continued qualification of sustainable cabin components.
Advanced thermoplastics are forecast to register the fastest growth among material segments, at a 6.85% CAGR through 2032, supported by demand for recyclable materials and more efficient cabin-component manufacturing. DIAB has developed a fully recyclable thermoplastic sandwich panel specifically for aircraft cabin interiors. According to the manufacturer, its manufacturing approach offers potential production cost savings of up to 20% and component weight reductions of up to 10%. The solution combines thermoplastic skins with a structural foam core and incorporates recycled production material. Such developments create opportunities for lightweight cabin panels and interior structures, although commercial adoption remains dependent on material qualification, production scalability, and requirements from airlines and aircraft manufacturers.
Geography Analysis
The UK is projected to account for 23.81% of Europe commercial aircraft cabin interior market revenue in 2026, making it the largest country market in the supplied estimates. British Airways announced a comprehensive A380 cabin modernization program in October 2026, including 106 Club Suites on the upper deck and upgrades across all cabin classes. The country is also home to established aircraft seating manufacturers, including Thompson Aero Seating, Acro Aircraft Seating, and Mirus Aircraft Seating. These companies support OEM and aftermarket cabin programs through seating development, manufacturing, and engineering activities. British Airways' premium-cabin investments and the country's specialized supplier base present identifiable opportunities in the European aircraft interior industry.
France is forecast to register the fastest geographic growth, at a 7.02% CAGR through 2032, supported by aircraft fleet modernization and cabin-equipment manufacturing activities. Safran maintains a major presence in aircraft seating and cabin equipment, supplying passenger airlines and aircraft manufacturers internationally. In April 2026, Safran Cabin secured an agreement to supply customized galleys and stowages for flyadeal's 10 A330neo aircraft, demonstrating export opportunities for its European manufacturing operations. Air France's ongoing fleet renewal and cabin modernization activities also contribute to demand for new seating, entertainment systems, and interior equipment. Together, airline investments and manufacturing capabilities support France's position within the European cabin interior supply chain.
Germany, Spain, Italy, and the Rest of Europe contribute through airline fleet renewal, cabin manufacturing, and retrofit programs. Lufthansa's A380 and A320 refurbishment activities support demand in Germany, while Diehl Aviation maintains a substantial presence in aircraft cabin systems. Iberia's Flight Plan 2030 includes long-haul fleet expansion and narrowbody renewal, creating opportunities for seating and interior upgrades in Spain. Italy contributes through aircraft seating manufacturers, including Geven and Aviointeriors. Elsewhere in Europe, SAS completed Starlink installations across 81 A320neo aircraft in September 2026, while KLM is progressively introducing free Wi-Fi across its European operations. These activities demonstrate investment across different airline business models and aircraft categories.
Competitive Landscape
The Europe commercial aircraft cabin interior market includes established Tier-1 suppliers and specialized manufacturers competing across distinct cabin equipment categories. Safran and Collins Aerospace offer broad portfolios covering seating, galleys, lavatories, lighting, and integrated cabin solutions. Diehl Aviation specializes in cabin lighting, cabin management systems, and interior integration, while Panasonic Avionics and Thales compete in the IFE and connectivity equipment segment. FACC supplies lightweight cabin structures and composite interior components. Key seating suppliers include RECARO, Geven, Thompson Aero Seating, Acro Aircraft Seating, Mirus Aircraft Seating, ZIM Aircraft Seating, Expliseat, and Aviointeriors. Supplier competitiveness depends on aircraft certification capabilities, product weight, manufacturing capacity, delivery reliability, and the ability to meet airline-specific cabin requirements.
Recent strategic developments reflect continued investment in new seating programs, customized cabin equipment, and production capacity. In April 2026, Collins Aerospace secured three international airline launch customers for its Helix main cabin seat, covering approximately 200 A320 and B737 aircraft, with initial shipset deliveries targeted for late 2027. During the same month, Safran Cabin signed an agreement to supply customized galleys and stowage solutions for flyadeal's ten A330neo aircraft, with production planned at its Rokycany facility in the Czech Republic. European airline refurbishment programs, including Lufthansa's planned A380 and A320 upgrades, also support demand for specialized seating, cabin systems, and modification suppliers. These developments underscore competition based on product innovation, manufacturing readiness, and program execution capabilities.
Aftermarket competition extends beyond equipment manufacturers to approved MRO providers and cabin modification specialists. Lufthansa Technik, Air France Industries, KLM Engineering & Maintenance, SR Technics, and Sabena Technics participate in aircraft maintenance and modification activities, though their cabin-modification capabilities vary. In March 2026, Lufthansa Technik Malta completed its first B787 cabin modification, including seating reconfiguration and cabin monument upgrades. In May 2026, Lufthansa Technik also received EASA Certain STC Privilege for qualifying A320ceo cabin changes, strengthening its ability to manage recurring modifications within an approved scope. Engineering approvals, installation capacity, and maintenance scheduling influence competition for complex refurbishment programs. Suppliers that combine cabin integration expertise with qualified modification capabilities are well-positioned to address increasingly complex airline retrofit requirements.
Europe Commercial Aircraft Cabin Interior Industry Leaders
-
Safran SA
-
Collins Aerospace (RTX Corporation)
-
Diehl Stiftung & Co. KG
-
Panasonic Holdings Corporation
-
RECARO Aircraft Seating GmbH & Co. KG (RECARO Holding GmbH)
- *Disclaimer: Major Players sorted in no particular order
Recent Industry Developments
- October 2026: British Airways’ A380 cabin refurbishment across 12 aircraft, including new seating, 106 Club Suites per aircraft, and upgraded IFE, reflects rising investment by European airlines in widebody retrofit programs and premium cabin modernization.
- September 2026: SAS announced completion of Starlink inflight connectivity installation across its entire 81-aircraft A320neo fleet in six months, following the service launch in March 2026. The A320neo fleet constitutes approximately 70% of SAS’s total fleet. SAS stated that the aircraft type is the first in its fleet to be fully equipped with Starlink.
- June 2025: Acro Aircraft Seating’s selection by FlySafair to supply Series 9 Fixed Back seats for multiple B737 shipsets highlights continued airline demand for lightweight, low-maintenance seating, supporting replacement and retrofit opportunities for European aircraft seating suppliers.
Europe Commercial Aircraft Cabin Interior Market Report Scope
A commercial aircraft cabin interior comprises all structural, functional, and decorative elements within the passenger compartment and pressure hull. These systems are designed to ensure passenger safety, ergonomic comfort, crew functionality, and airline brand differentiation.
The Europe commercial aircraft cabin interior market is segmented by product type, aircraft type, cabin class, fit type, material, and geography. By product type, the market is segmented into seating, cabin lighting, in-flight entertainment and connectivity (IFEC), galleys and monuments, lavatory systems, cabin windows and windshields, overhead stowage bins, interior panels and floorboards, and others. By aircraft type, the market is segmented into narrowbody aircraft, widebody aircraft, regional jets, and turboprop aircraft. By cabin class, the market is segmented into first class and business class, premium economy class, and economy class. By fit type, the market is segmented into original equipment manufacturer (OEM) and aftermarket. By material, the market is segmented into composites, aluminum alloys, steel and other alloys, and advanced thermoplastics. The report also covers the market sizes and forecasts for the Europe commercial aircraft cabin interior market in six countries across the region. For each segment, the market size is provided in terms of value (USD).
By Product Type
| Seating |
| Cabin Lighting |
| In-Flight Entertainment and Connectivity (IFEC) |
| Galley and Monuments |
| Lavatory Systems |
| Cabin Windows and Windshields |
| Overhead Stowage Bins |
| Interior Panels and Floorboards |
| Others |
By Aircraft Type
| Narrowbody Aircraft |
| Widebody Aircraft |
| Regional Jets |
| Turboprop |
By Cabin Class
| First Class and Business Class |
| Premium Economy Class |
| Economy Class |
By Fit Type
| Original Equipment Manufacturer (OEM) |
| Aftermarket |
By Material
| Composites |
| Aluminum Alloys |
| Steel and Other Alloys |
| Advanced Thermoplastics |
By Geography
| United Kingdom |
| France |
| Germany |
| Spain |
| Italy |
| Russia |
| Rest of Europe |
| By Product Type | Seating |
| Cabin Lighting | |
| In-Flight Entertainment and Connectivity (IFEC) | |
| Galley and Monuments | |
| Lavatory Systems | |
| Cabin Windows and Windshields | |
| Overhead Stowage Bins | |
| Interior Panels and Floorboards | |
| Others | |
| By Aircraft Type | Narrowbody Aircraft |
| Widebody Aircraft | |
| Regional Jets | |
| Turboprop | |
| By Cabin Class | First Class and Business Class |
| Premium Economy Class | |
| Economy Class | |
| By Fit Type | Original Equipment Manufacturer (OEM) |
| Aftermarket | |
| By Material | Composites |
| Aluminum Alloys | |
| Steel and Other Alloys | |
| Advanced Thermoplastics | |
| By Geography | United Kingdom |
| France | |
| Germany | |
| Spain | |
| Italy | |
| Russia | |
| Rest of Europe |
Market Definition
- Product Type - Commercial Aircraft cabin interior products such as passenger seats, cabin lighting, inflight entertainment system, cabin windows, lavatories, galley, and stowage bins have been included under the product type in this study.
- Aircraft Type - All the passenger aircraft such as narrowbody and widebody which are single-aisle and twin-aisle are included in this study.
- Cabin Class - Business and First Class, economy and premium economy are classes of air travel provided by the airlines that offer various services to the passengers.
| Keyword | Definition |
|---|---|
| Gross domestic product (GDP) | Gross domestic product (GDP) is a monetary measure of the market value of all the final goods and services produced in a specific time period by countries. |
| Original Equipment Manufacturer (OEM) | An original equipment manufacturer (OEM) traditionally is defined as a company whose goods are used as components in the products of another company, which then sells the finished item to users. |
| High Dynamic Range (HDR) | Dynamic range describes the ratio between the brightest and darkest parts of an image. HDR is used to capture a greater dynamic range than SDR. |
| Federal Aviation Administration (FAA) | The division of the Department of Transportation is concerned with aviation. It operates Air Traffic Control and regulates everything from aircraft manufacturing to pilot training to airport operations in the United States. |
| European Aviation Safety Agency (EASA) | The European Aviation Safety Agency is a European Union agency established in 2002 with the task of overseeing civil aviation safety and regulation. |
| 4K Display | 4K resolution refers to a horizontal display resolution of approximately 4,000 pixels. |
| Organic Light Emitting Diode (OLED) | It is the light-emitting diode (LED) in which the emissive electroluminescent layer is a film of organic compound that emits light in response to an electric current. |
| Mean Time Between Failures (MTBF) | The mean time between failures is the predicted elapsed time between inherent failures of a mechanical or electronic system, during normal system operation. |
| (Low-Cost Carrier (LCCs) | It is an airline that is operated with an especially high emphasis on minimizing operating costs and without some of the traditional services and amenities provided in the fare |
| Electronically Dimmable Windows (EDW) | It is a type of window that blocks up to 99.96% of all visible light and provide full opacity, integrated into the window cassette of the sidewall panel. |
Research Methodology
Mordor Intelligence follows a four-step methodology in all our reports.
- Step 1: Identify Key Variables: In order to build a robust forecasting methodology, the variables and factors identified in Step-1 are tested against available historical market numbers. Through an iterative process, the variables required for market forecast are set and the model is built on the basis of these variables.
- Step 2: Build a Market Model: Market-size estimations for the historical and forecast years have been provided in revenue terms. For sales conversion to volume, the average selling price (ASP) is kept constant throughout the forecast period for each country, and inflation is not a part of the pricing.
- Step 3: Validate and Finalize: In this important step, all market numbers, variables and analyst calls are validated through an extensive network of primary research experts from the market studied. The respondents are selected across levels and functions to generate a holistic picture of the market studied.
- Step 4: Research Outputs: Syndicated Reports, Custom Consulting Assignments, Databases & Subscription Platforms


