
Bread Market Size and Share
Bread Market Analysis by Mordor Intelligence
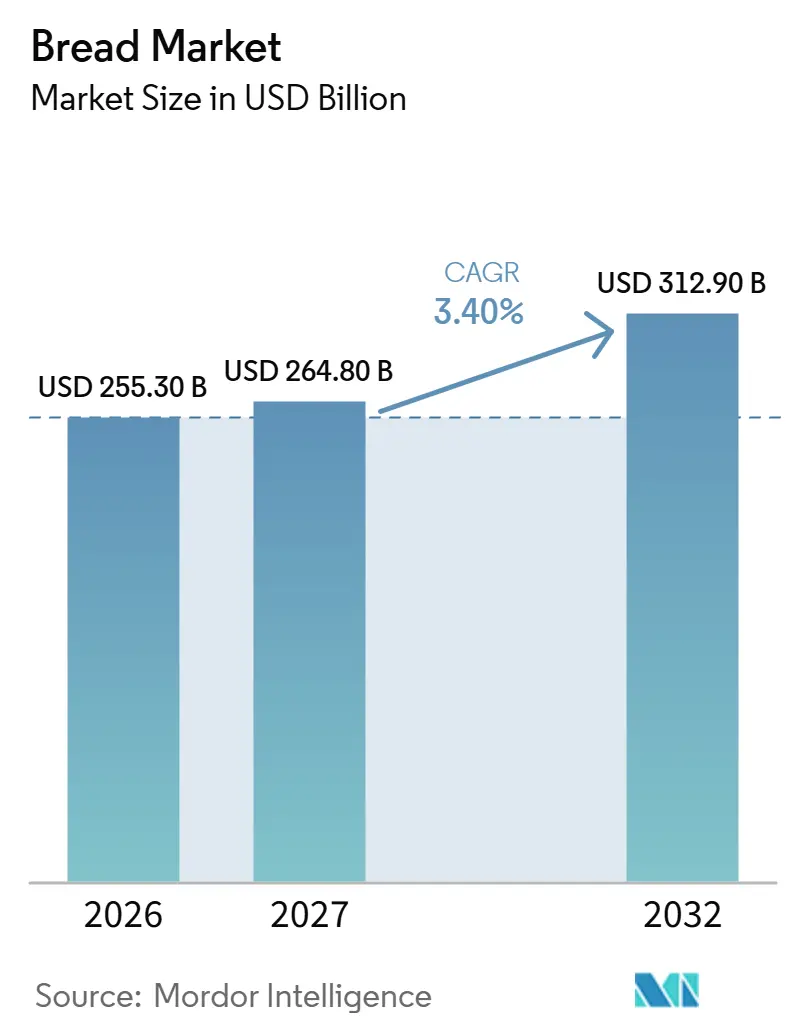
The bread market size is expected to grow from USD 255.3 billion in 2026 to USD 264.8 billion in 2027 and is forecast to reach USD 312.9 billion by 2032 at 3.4% CAGR over 2027-2032. The bread market volume is expected to grow from 100.2 million tons in 2026 to 101.8 million tons in 2027 and is forecast to reach 110.2 million tons by 2032 at 1.6% CAGR over 2027-2032.
Nutrition-focused recipes and wider urban distribution create opportunities for bread producers. In India, packaged formats connect demand with regional production and trade-channel reach. Ingredient-cost uncertainty and recalls make reliable supply consequential alongside differentiation. With value forecast to grow about twice as fast as volume, capacity investment in premium and specialty loaves offers a route to higher revenue per loaf through wider distribution.
Key Report Takeaways
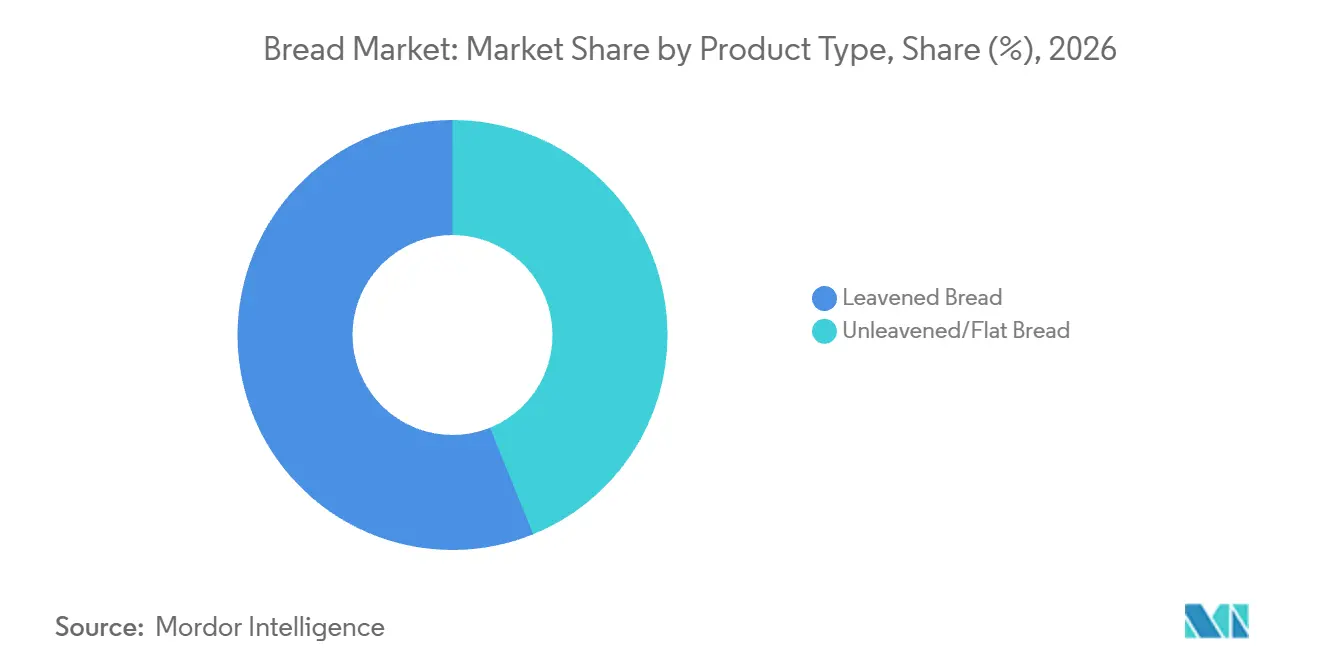
- By product type, leavened bread led with a 56.12% bread market share in 2026, while unleavened/flat bread is forecast to grow fastest at 3.65% CAGR over 2027-2032.
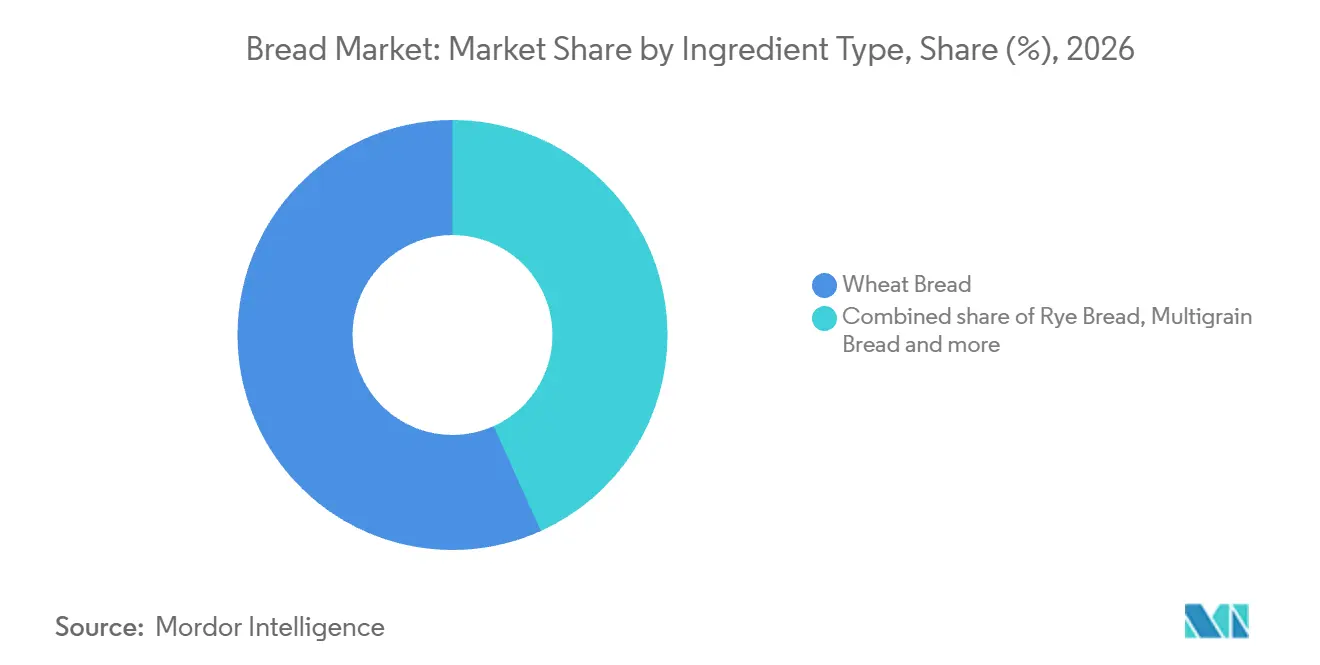
- Within the ingredient mix, wheat bread held a 56.74% share of the bread market size in 2026, and multigrain bread is forecast to grow fastest at 3.85% CAGR over 2027-2032.
- By nature, conventional bread led with an 83.99% value share in 2026, with free-from bread forecast to grow fastest at 5% CAGR over 2027-2032.
- Across distribution channels, off-trade held a 63.8% value share in 2026, while on-trade is forecast to grow fastest at 4.55% CAGR over 2027-2032.
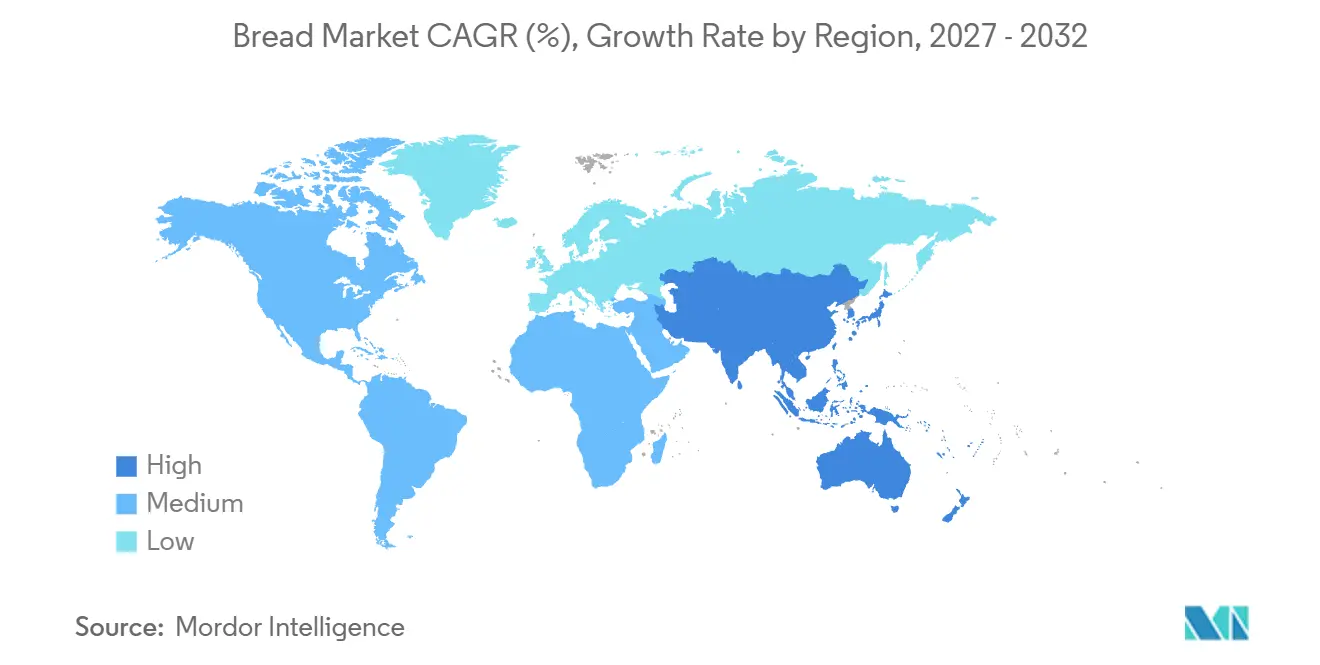
- Geographically, Europe led with a 29.2% value share in 2026, and Asia-Pacific is forecast to grow fastest at 4.9% CAGR over 2027-2032.
Note: Market numbers in this report are based on Mordor Intelligence's proprietary estimation framework, which combines nine months of actuals with Q4 projections for base year 2026.
Market Trends and Insights
Drivers Impact Analysis of Bread Market*
| Driver | (~) % Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
|---|---|---|---|
| Rising demand for functional and fortified breads boosts demand | +1.2% | United States and South Korea | Short term (≤ 2 years) |
| Rapid urbanization driving packaged bread adoption | +1% | India’s metropolitan and secondary cities | Medium term (2-4 years) |
| Expansion of artisanal in-store bakeries | +0.9% | United Kingdom supermarket bakery locations | Medium term (2-4 years) |
| Advancements in baking technology improve production efficiency | +0.8% | Germany’s Ruhr region | Medium term (2-4 years) |
| E-commerce penetration is increasing direct-to-consumer frozen bread sales | +0.5% | Across the United States | Medium term (2-4 years) |
| Government wheat subsidy programs increasing affordability | +0.3% | Egypt’s ration-card bread distribution network | Short term (≤ 2 years) |
| Source: Mordor Intelligence | |||
Rising demand for functional and fortified breads boosts demand
Nutrition-led bread offers can address specific dietary preferences while preserving a familiar product format. In a 2025 survey, 37% of US consumers said they wanted to increase their consumption of whole-grain bread, rolls, or buns.[1] In South Korea, GS Retail reported that protein-bread-related sales at its GS25 convenience stores in April 2025 were 6.4 times their August 2024 level, when the lineup was rolled out in earnest. Whole-grain offers address an intention to change consumption, while the protein-bread result reflects sales through a single convenience chain. For suppliers choosing nutritional recipes, channel sales results provide a firmer basis for committing production than dietary intentions alone.
Rapid urbanization driving packaged bread adoption
Extending packaged-bread availability to additional city markets requires supply operations capable of serving those locations. Using its standardized city definition, the United Nations Population Division estimated that cities housed 45% of the global population in 2025, more than double the proportion in 1950. Mrs Bectors Food Specialities’ FY2025-26 review identified branded bakery expansion beyond metropolitan markets, while its FY2024-25 bread review had described reach into Tier 2 regions and beyond in India. In September 2025, the company said bakery supply constraints left some quick-service restaurants and business partners beyond its reach. It commissioned its Hooghly bakery plant, adjacent to Kolkata, in January 2026, enabling regional service to general trade, modern trade, and institutional partners. Serving additional trade and institutional accounts requires production coverage to match distribution ambitions, because the company’s reported constraint was physical supply.
Expansion of artisanal in-store bakeries
Demand for premium specialty bread can influence how a supermarket organizes its in-store bakery offer. In 2025, Tesco introduced a new in-store finishing model after demand increased for its premium Finest specialty breads. Its in-store offer covered baguettes, white bread, and multipack rolls alongside Finest signature bakes and sweet treats. Because the new model also covers white bread and multipack rolls, rising demand for premium Finest breads changed how Tesco finishes its everyday bread lines in store, not only its specialty range.
Advancements in baking technology improve production efficiency
Automating frozen-dough loading can give bakeries a defined preparation stage through which to organize production. Malzers Bakery operated the frozen-dough loading line in Germany, with the automation system designed and installed by ADM Automation & Engineering. The line processed 9,000 dough pieces per hour during its acceptance trial against a specified 8,000. Malzers employees previously loaded the trays and sheets by hand, a task taken over by 6 industrial robots. With trays feeding main-site production and sheets delivered to branches for on-site baking, central loading automation can support fresh branch output while leaving final baking close to customers.
Restraints Impact Analysis of Bread Market*
| Restraint | (~) % Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
|---|---|---|---|
| Volatility in global wheat prices compressing margins | -0.6% | Bakery manufacturing locations in Canada | Short term (≤ 2 years) |
| Safety concerns and product recalls | -0.4% | Seattle and Tacoma metropolitan areas | Short term (≤ 2 years) |
| Cold-chain gaps limiting frozen bread distribution | -0.2% | Frozen-food distribution locations in India | Long term (≥ 4 years) |
| Growing popularity of low-carb diets negatively impacts bread consumption | -0.2% | Across the United States | Medium term (2-4 years) |
| Source: Mordor Intelligence | |||
Volatility in global wheat prices compressing margins
Flour-cost pressure can constrain bread producers by reducing the room between ingredient spending and the price of a finished loaf. Farm Credit Canada’s (FCC) 2026 bakery report described several years of elevated flour and flour-based product price pressure for Canadian manufacturers. FCC identifies flour as these processors’ largest and most essential ingredient cost, with wheat as its foundational input. Aryzta AG’s 2025 annual report identified increased wheat-flour price volatility caused by changing yields in its key sourcing markets. The wheat Raw Materials Price Index fell 5.6% in 2025 compared with 2024, though FCC’s lower-price outlook for the 2026-27 crop year depended on growing conditions. Yield-sensitive flour costs leave bakery margins exposed to sourcing-market conditions even when an annual wheat index falls.
Safety concerns and product recalls
Physical contamination can interrupt bread availability across several selling routes even when the affected product is narrowly defined. Grand Central Bakery recalled potato sourdough bread over possible metal contamination after sales in the Seattle and Tacoma metro areas on August 10, 2026.[2] The affected bread had reached grocery stores, restaurants, wholesalers, and bakery cafes, making the exposure broader than a single shop. Because those lots were sold through several channels on a single day, recall communications needed to cover each customer type. Even a narrow product line can generate notification and handling costs across multiple selling routes when contamination prompts a recall.
*Our forecasts treat driver/restraint impacts as directional, not additive. The impact forecasts reflect baseline growth, mix effects, and variable interactions.
Bread Market Segment Analysis
By Product Type:
Established Loaves and Expanding FlatbreadsLeavened bread accounted for a 56.12% share of the bread market size in 2026, making it the largest segment. In October 2026, Geary’s Bakeries said its new Glenfield site in Leicester had 2 sourdough production lines. Geary’s expected the site to increase Jason’s Sourdough Ciabattin and Boule loaf output and more than double company production capacity. The site was intended to combine production, packing, and distribution for delivery across the UK. Expected output growth centers on 2 loaf formats, Ciabattin and Boule, so the expansion tests how far a single sourdough brand can scale through UK-wide distribution.
Unleavened/flat bread is forecast to be the fastest-growing segment, at 3.65% CAGR over 2027-2032. The flatbread category recorded 44% value growth since 2023, according to Numerator data cited in January 2026. Signature Flatbreads said more than 100 new products launched in the UK and internationally delivered growth in the year ended July 26, 2025. Those launches included high-fiber, high-protein, and whole-grain flatbreads alongside morning goods. Nutritional recipes extend flatbread differentiation beyond shape, allowing manufacturers to address different dietary preferences within the same product format.

By Ingredient Type:
Household Wheat Demand and Specialty InterestWheat bread represented a 56.74% bread market share in 2026, making it the largest segment. In 2025, at-home wheat-bread consumption in Russia averaged 23.7 kilograms per person. The corresponding combined figure for other bread types was 11.1 kilograms per person. Total at-home bread consumption in Russia was 34.8 kilograms per person in 2025, its lowest level since 2006. For Russian wheat-bread suppliers, a staple position provides substantial household volume, but the historically low total puts the commercial emphasis on retaining that volume.
Multigrain bread is forecast to be the fastest-growing segment, at 3.85% CAGR over 2027-2032. Mrs Bectors Food Specialities’ FY2025-26 review reported higher interest in India for whole-wheat, multigrain, nutritional, gourmet, and specialty breads. It said higher-value categories collectively grew faster than average. Multigrain producers can position their recipes within this higher-value assortment, where nutritional attributes can support differentiation from staple loaves. Rye bread had a distinct dietary role in Finland, where Fazer’s 2025 Great Bread Study found that 77% of Finns considered it important to a healthy diet.
By Nature:
Conventional Scale and Gluten-Free Brand DevelopmentConventional bread was the largest segment, with an 83.99% share in 2026. Traditional ambient bread formed a major part of the UK’s broader bread and baked goods retail category in the 52 weeks ending February 22, 2026. Tip Top Bakeries opened a fresh-bread line at Canning Vale, Western Australia, on February 20, 2026, doubling site capacity. The new line’s stated capacity was 8,350 loaves per hour. At Canning Vale, the added capacity allows Tip Top to accommodate more fresh-bread demand at an existing production site.
Free-from bread is forecast to be the fastest-growing segment, at 5% CAGR over 2027-2032. Canyon Bakehouse, a US gluten-free bread brand, generated estimated retail sales of USD 174 million in fiscal 2025. It was the top-selling US gluten-free bread brand in the 53 weeks ending January 4, 2026. Canyon Bakehouse is owned by Flowers Foods, a US packaged-bakery producer.
By Distribution Channel:
Retail Reach and Foodservice ApplicationsOff-trade was the largest segment, with a 63.8% share in 2026. Great Britain’s pre-pack bread and morning-goods sales reached 3.84 billion packs in the 52 weeks ending March 22, 2026, up from 3.77 billion a year earlier. The rise of about 70 million packs shows packaged bakery volume growing in the measured British retail channel.
On-trade is forecast to be the fastest-growing segment, at 4.55% CAGR over 2027-2032. FCC’s 2026 report described quick-service restaurants as a resilient and expanding downstream market for breads, buns, and wraps in Canada. That buyer base connects bread demand to foodservice applications, giving manufacturers a route through products purchased for use in an operator’s menu. FCC also identifies quick-service restaurants as Canada’s largest foodservice channel. For bun and wrap suppliers, exposure to this large buyer group makes restaurant-menu applications a distinct commercial priority alongside household consumption.
Geography Analysis
Europe Bread Market
Europe held a 29.2% bread market share in 2026, making it the largest geography. Aryzta AG’s Europe segment recorded EUR 894 million (USD 1.01 billion) in 2025 revenue from its bread rolls and artisan loaves category. Kara Foodservice, a Finsbury Food Group bakery brand, produces bread rolls in Manchester and supplies wholesalers and direct foodservice customers across the UK. Kara’s distribution to over 250 food wholesalers shows how a European bread producer can reach foodservice buyers through intermediaries as well as direct accounts.
Asia-Pacific Bread Market
Asia-Pacific is the fastest-growing geography, with a forecast 4.9% CAGR over 2027-2032. In Japan, Yamazaki Baking’s Bread category net sales rose 3.7% in FY2025 from FY2024. Convenience Retail Asia reported double-digit FY2025 sales growth in its business-to-business bakery enterprise in Hong Kong and Macau, supported by existing customers and new accounts. That enterprise’s manufacturing areas included sourdough bread alongside festive offerings, sandwiches, and salads, while new accounts included coffee chains and hotels. For this bakery enterprise, expansion into coffee chains and hotels broadens the customer base over which its mixed-product manufacturing capabilities can earn sales.
In North America, US center-store sandwich bread sales fell 1.5% to USD 9.97 billion in multi-outlet retail during the 52 weeks ended August 9, 2026. A smaller measured sales pool raises the importance of winning rival sales for US sandwich bread suppliers seeking growth within that channel. In South America, Brazil’s bakery and confectionery association ABIP reported 332,558 active bakery and confectionery businesses across Brazil’s 27 states in 2025. Within Middle East and Africa, Tiger Brands’ South African Bakeries business increased general-trade penetration during the 6 months ended March 31, 2026. Commercial priorities differ between retaining US retail demand, reaching Brazil’s widespread bakery channel, and extending access through South African general trade.
Mordor Intelligence provides coverage of the bread market across other key regional markets. Detailed country-level analysis extends to United States incorporating local coverage and market participation, as required.
Regulatory Framework and Outlook
The comparison examines selected jurisdictions from the perspective of packaged-bread manufacturers selling to local consumers. The relevant commercial questions are how recipes may be formulated and what information packaging must carry. China’s operative GB 7718-2011 requires clearly shown production dates and shelf life, with characters at least 1.8 millimeters high.
Regulatory Table of Bread Market
| Decision factor | United States | Germany | China | Brazil | Saudi Arabia |
|---|---|---|---|---|---|
| Primary authority | Food and Drug Administration | State and local food-monitoring authorities | Local market-regulation departments; national oversight by the State Administration for Market Regulation from March 16, 2027 | Anvisa | Saudi Food and Drug Authority |
| Key instruments or direction | 21 CFR 136.110 for standardized bread, rolls, and buns | EU Regulation 1169/2011 and national food-information ordinance | GB 7099-2015 for pastry and bread; GB 7718-2011 labeling | RDC 429/2020 and IN 75/2020 packaged-food nutrition labeling | SFDA.FD 2362/2018 bread-production requirements |
| Commercial effect | Recipe, naming, and ingredient-label compliance for covered standardized products | Mandatory food information in German | Product-safety and prepackaged-food date-label compliance | Nutrition-table, claim, and applicable front-of-pack requirements | Bread salt limited to 1 g per 100 g of finished product |
| Current policy attractiveness | Medium | Medium | Medium | Medium | Medium |
| Future direction of policy attractiveness | Easing | No change | Hardening | Hardening | No change |
| Source: Mordor Intelligence | |||||
US standards impose bounded recipe and naming duties, with salt-substitute permission effective December 14, 2026, easing formulation choices, while Germany’s established disclosure and German-language duties support continuity in label compliance. China’s Food Labeling Supervision Measures raise the 1.8-millimeter baseline for production and expiry-date text to 3.0 millimeters, or 2.0 millimeters for packages below 35 square centimeters maximum surface area, from March 16, 2027, requiring packaging adjustments. Brazil’s nutrition-label duties and proposed broader added-sugar definition point toward additional classification work after a consultation that closed March 9, 2026, with the review process continuing. Saudi Arabia’s active salt ceiling creates a direct recipe constraint, with its continuing place in operative policy supporting a stable formulation requirement.
Value Chain Stages
The comparison follows flour supply, bread production, and delivery to selling locations, identifying where each supplier earns revenue. Ardent Mills buys grain from family farms and supplies flour and grain ingredients to commercial bakeries and distributors across North America. Warburtons contracts British farmers to grow wheat for its bakery products and also sources wheat from Canada. Warburtons uses its wheat blend for the taste, softness, and freshness it seeks in bread.
Value Chain Analysis Table of Bread Market
| Primary activity | Key participants | Value capture | Bottleneck | Resilience response |
|---|---|---|---|---|
| Grain sourcing and flour supply | Flour and grain-ingredient suppliers such as Ardent Mills | Flour and grain-ingredient sales | Matching grain inputs to baking specifications | Qualify alternative grain sources against product requirements |
| Bread production | Commercial bakers such as Warburtons and Tiger Brands | Finished-bread sales | Equipment stability and product damage | Upgrade bakery equipment and verify bread quality |
| Distribution and store delivery | Bakery distribution operators such as Flowers Foods | Product sales through store-delivery and warehouse channels | Coordinating orders, shelf stock, and unsold-product removal | Align deliveries with store orders and removal tasks |
| Source: Mordor Intelligence | ||||
In the year ended September 30, 2025, Tiger Brands invested in bakery equipment upgrades, fleet optimization, and route-to-market software in South Africa. Flowers Foods’ US direct-store-delivery model assigns independent distributors ordering, selling, stocking, and unsold-product removal tasks. This division of work makes the final commercial handoff consequential for value capture, since physical bread production and selling through customer stores sit with different participants.
Competitive Landscape
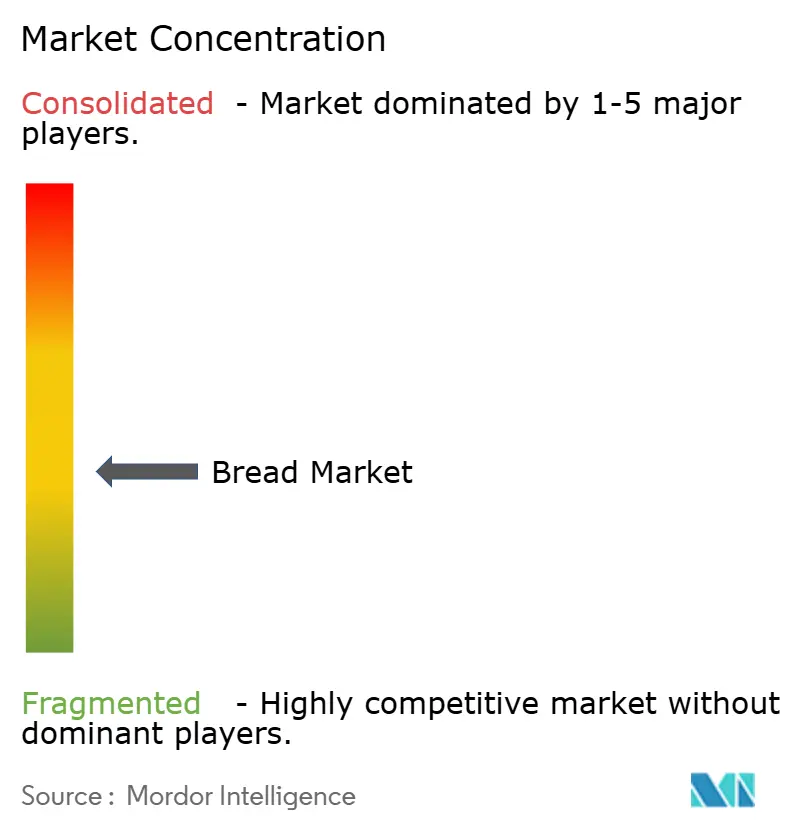
Industrial bakery competition includes large branded producers alongside regional, local, and retailer-owned suppliers in US breads and rolls. Grupo Bimbo S.A.B. de C.V. participates through Bimbo Bakeries USA, part of the group, while Yamazaki Baking Co., Ltd. manufactures and sells bread in Japan. Flowers Foods’ branded products held 16% of total US bread, bun, and roll brand share in the 53 weeks ending January 3, 2026.[3] The Campbell’s Company competes in US breads and rolls under Pepperidge Farm, while Associated British Foods Plc (ABF) operates the UK bakery business Hovis Bakeries.
Operating execution can qualify the advantage of a large brand portfolio when bread availability becomes the immediate customer concern. In fiscal Q4 2026, The Campbell’s Company reported that Pepperidge Farm fresh-bakery consumption declined 4.4%, an improvement from Q3. Management attributed the improvement to continued execution focus within its network and in stores, while identifying on-shelf availability as a near-term opportunity entering fiscal 2027. Flowers Foods ended bread and bun production at its Bailey Street Bakery in Atlanta on April 16, 2025, as part of capacity optimization. Campbell’s execution focus moderated declines without restoring consumption growth, while Flowers’ Bailey Street closure addressed production capacity, tying both responses to network performance rather than evidence of stronger demand.
On July 8, 2026, ABF completed its Hovis Group acquisition from Endless LLP and combined it with Allied Bakeries to operate as Hovis Bakeries. The UK Competition and Markets Authority had cleared the deal on June 16, finding Allied Bakeries would likely exit if it did not proceed. Both bakery businesses were significant own-brand suppliers to major UK supermarkets. The combination links corporate consolidation with the continuity of an industrial supply option for retailers selling bread under their own labels.
Bread Industry Leaders
-
Grupo Bimbo S.A.B. de C.V.
-
Yamazaki Baking Co., Ltd.
-
Flowers Foods Inc.
-
The Campbell’s Company
-
Associated British Foods Plc
- *Disclaimer: Major Players sorted in no particular order
Bread Market Companies Covered in this Report
- Grupo Bimbo S.A.B. de C.V.
- Associated British Foods Plc
- Yamazaki Baking Co., Ltd.
- Flowers Foods Inc.
- Barilla Group
- The Campbell’s Company
- George Weston Foods
- Finsbury Food Group
- Almarai Company
- Warburtons
- Lantmännen Unibake
- Paris Baguette
- Britannia Industries
- Aryzta AG
- Rich Products Corp.
- General Mills
- Nestlé S.A.
- Panera Bread
- Kellanova
- FGF Brands
Key Opportunities for Market Participants
The opportunities comparison focuses on commercially supplied bread for school meals and breakfast provision in England. In September 2026, the Department for Education proposed a minimum of 4 g of fiber per 100 g for manufactured school bread from September 2027, subject to parliamentary approval. Its proposed breakfast standard would require a starchy carbohydrate, with bread or cereal among the eligible options, on the same timetable and approval condition. These proposals create a preparation window for suppliers developing bread offers for school buyers.
Market Opportunities Table of Bread Market
| Opportunity | Why now | Buyer / lead segment | Recommended play | Main barrier | Likely beneficiaries |
|---|---|---|---|---|---|
| Manufactured bread meeting the proposed fiber specification | Proposed school-bread specification | School meal purchasers | Develop loaves against the proposed specification | Achieving the proposed fiber minimum | Commercial bread manufacturers |
| Bread offers for school breakfast provision | Proposed carbohydrate offer expressly includes bread | School breakfast clubs | Offer bread suited to the breakfast service | Menu-change difficulty under existing agreements | Bread suppliers serving school caterers |
| Specification changes through incumbent supply relationships | Respondents reported difficulty changing menus under existing agreements | School caterers tied to supply frameworks | Agree compliant bread substitutions within contract terms | Aligning recipe changes with contract terms | Incumbent bakery suppliers able to adapt recipes |
| Source: Mordor Intelligence | |||||
Consultation respondents reported that menu changes could be difficult where schools were tied into contracts, framework arrangements, or supplier agreements. Working through those relationships may therefore connect a compliant product with a practical route to adoption. The central opening is bread that meets the proposed nutritional specification and fits the school’s actual catering arrangement.
Recent Industry Developments in Bread Market
- Oct 2026: FDA published a final rule permitting salt substitutes in standardized bread, rolls, and buns, effective December 14, 2026.
- Sep 2026: Village Bakery resumed commercial bread production at the rebuilt Wrexham Industrial Estate bakery in the United Kingdom.
- Jul 2026: Associated British Foods Plc completed its acquisition of Hovis Group Limited from Endless LLP and combined it with Allied Bakeries, its UK bakery business, to operate as Hovis Bakeries.
Bread Market Report Scope and Research Methodology
Market Definition and Coverage
The bread market covers commercially sold finished bread products bought by households and foodservice operators through retail and foodservice channels worldwide. It measures annual spending on these products in USD.
Scope exclusions: Bread mixes, dough improvers, breadcrumbs, pizza crust blanks, and non-bread substitute bases are excluded.
Segments Covered in This Report
- By Product Type
- Leavened Bread
- Loaves
- Baguettes
- Burger Buns
- Sandwich Slices
- Ciabatta
- Other Product Types
- Unleavened/Flat Bread
- Tortilla
- Pita
- Chapati/Roti/Paratha
- Others
- Leavened Bread
- By Ingredient Type
- Wheat Bread
- Rye Bread
- Multigrain Bread
- Other Ingredients
- By Nature
- Conventional Bread
- Free-From Bread
- By Distribution Channel
- Off-Trade
- Convenience/Grocery Stores
- Specialist Retailers
- Supermarkets/Hypermarkets
- Online Retail
- Other Channels
- On-Trade
- Off-Trade
- By Geography
- North America
- United States
- Canada
- Mexico
- Rest of North America
- South America
- Brazil
- Argentina
- Colombia
- Chile
- Rest of South America
- Europe
- United Kingdom
- Germany
- France
- Italy
- Spain
- Russia
- Sweden
- Belgium
- Poland
- Netherlands
- Rest of Europe
- Asia-Pacific
- China
- Japan
- India
- Thailand
- Singapore
- Indonesia
- South Korea
- Australia
- New Zealand
- Rest of Asia-Pacific
- Middle East and Africa
- United Arab Emirates
- South Africa
- Saudi Arabia
- Nigeria
- Egypt
- Morocco
- Turkey
- Rest of Middle East and Africa
- North America
Data Sources, Market Sizing, and Validation
Desk Research
FAO's Country Cereal Balance Sheets and Eurostat's crop balances, for example, provide production, trade, stock, and domestic-use context for wheat and other cereals that helps interpret bread supply conditions. USDA Economic Research Service food-availability data provide a US consumption proxy built from commodity supply and use, while US Census Bureau retail and food-services sales series help track retail and food-service channel conditions.
Company filings and investor materials can clarify product portfolios, bakery capacity, selling channels, and reported sales, while reputable food-industry press can cross-check dated launches, closures, recalls, and supply changes. These sources are illustrative rather than exhaustive, and further sources inform collection, validation and clarification.
Primary Interviews and Surveys
Interviews and structured surveys would cover bakery manufacturers, ingredient and distribution specialists, and retail or foodservice buyers, with respondents able to discuss finished-bread sales, channel coverage, product mix, and price changes. Their evidence would be used to test secondary-source interpretations and clarify how each respondent distinguishes bread from wider bakery categories. Where observations conflict or leave a gap, the analyst would compare them with company disclosures, official supply and channel indicators, and sampled supplier or channel estimates before carrying an assumption into the model.
Distribution of primary research fieldwork respondents
| Company type | Respondent position | Region |
|---|---|---|
| Top tier: 30% | CXOs: 20% | APAC: 40% |
| Mid tier: 50% | Functional/Unit leaders: 35% | EMEA: 32% |
| Smaller Players: 20% | Managers: 45% | Americas: 28% |
Market-Sizing & Forecasting
A top-down model would estimate global finished-bread sales at the first transaction within the market boundary, then allocate value and volume across the report's product, ingredient, nature, channel, and regional cuts. Core indicators would include population and urbanization for the addressable buyer base, cereal and flour availability for supply context, household food spending and foodservice activity for demand, wheat and other ingredient prices for cost and price movement, and company disclosures on bakery sales or capacity for supplier checks. Segment shares would be built from reported category sales where available, then checked against product portfolios, channel exposure, regional consumption patterns, and respondent evidence so each set of segments reconciles to its relevant market total.
Value and volume would be forecast separately: value reflects units sold and realized prices, including premium and product-mix changes, while volume tracks finished-bread tonnage. A multivariate regression could relate historical value and volume to population, foodservice activity, flour prices, and income or spending indicators, with scenario analysis for unusual input-cost or channel shifts. Selective bottom-up checks would multiply sampled selling prices by observed or reported volumes for representative suppliers or channels and roll those checks up only where the coverage is clear. Missing indicators would be bounded with the closest official series and company disclosures, and primary respondents would test the variable assumptions and explain material departures before those assumptions are carried forward.
Data Validation & Update Cycle
Analysts would triangulate market totals and segment shares across official supply and consumption series, company disclosures, retail or foodservice indicators, and selective supplier or channel checks. Independent value, tonnage, price, and company-sales signals would be compared for direction and scale, with anomalies traced to timing, product coverage, channel counting, or currency and unit treatment before sign-off. Material gaps or unexplained differences would trigger source follow-up or respondent re-contact, followed by a second analyst review of the model inputs and reconciliations. The dataset would be refreshed annually, revisited between cycles after material events such as major capacity changes, acquisitions, or sharp ingredient-price shifts, and subjected to a fresh pre-delivery review.
Mordor Intelligence's Bread Market Size Versus Other Published Estimates
Published estimates can differ in the transactions and products they count and the inputs used to model demand. The bread market covers commercially sold finished bread products bought by households and foodservice operators through retail and foodservice channels worldwide.
Key Gap Drivers include the study's defined coverage and market-specific modeling choices. Core indicators would include population and urbanization for the addressable buyer base, cereal and flour availability for supply context, household food spending and foodservice activity for demand, wheat and other ingredient prices for cost and price movement, and company disclosures on bakery sales or capacity for supplier checks.
Benchmark comparison
| Source | Market Size | Gaps in Research Methodology |
|---|---|---|
| Mordor Intelligence | Value: USD 264.8 B (2027) / Volume: 101.8 million tons (2027) | |
| Global Consultancy A | USD 215.76 B (2025) | Its stated positive forecast trajectory means an earlier base can sit below a later-year estimate. |
| Regional Consultancy B | USD 239.44 B (2025) | Its positive forecast supports the lower earlier base, while added cake, pastry, and other bakery products broaden the reported category. |
Mordor Intelligence's analysts would triangulate market totals and segment shares across official supply and consumption series, company disclosures, retail or foodservice indicators, and selective supplier or channel checks.
Key Questions Answered in the Report
What is the bread market size and growth outlook?
The value is forecast to rise from USD 264.8 billion in 2027 to USD 312.9 billion in 2032 at 3.4% CAGR over 2027-2032.
What is supporting demand for nutrition-focused bread?
A 2025 US survey found that 37% of consumers wanted to increase consumption of whole-grain bread, rolls, or buns.
Which bread product type leads sales?
Leavened bread led with a 56.12% value share in 2026, while unleavened/flat bread is forecast to grow fastest at 3.65% CAGR over 2027-2032.
Which companies are major bread suppliers?
Major participants include Grupo Bimbo S.A.B. de C.V., Yamazaki Baking Co., Ltd., Flowers Foods Inc., The Campbell’s Company, and Associated British Foods Plc.
What safety challenge can interrupt bread supply?
Grand Central Bakery recalled potato sourdough bread over possible metal contamination after sales in Seattle and Tacoma metro areas on August 10, 2026.
Which region leads bread sales and which grows fastest?
Europe held a 29.2% value share in 2026, while Asia-Pacific is forecast to grow fastest at 4.9% CAGR over 2027-2032.