
Asia-Pacific Space Propulsion Market Size and Share
Market Overview
| Study Period | 2019 - 2031 |
|---|---|
| Forecast Data Period | 2026 - 2031 |
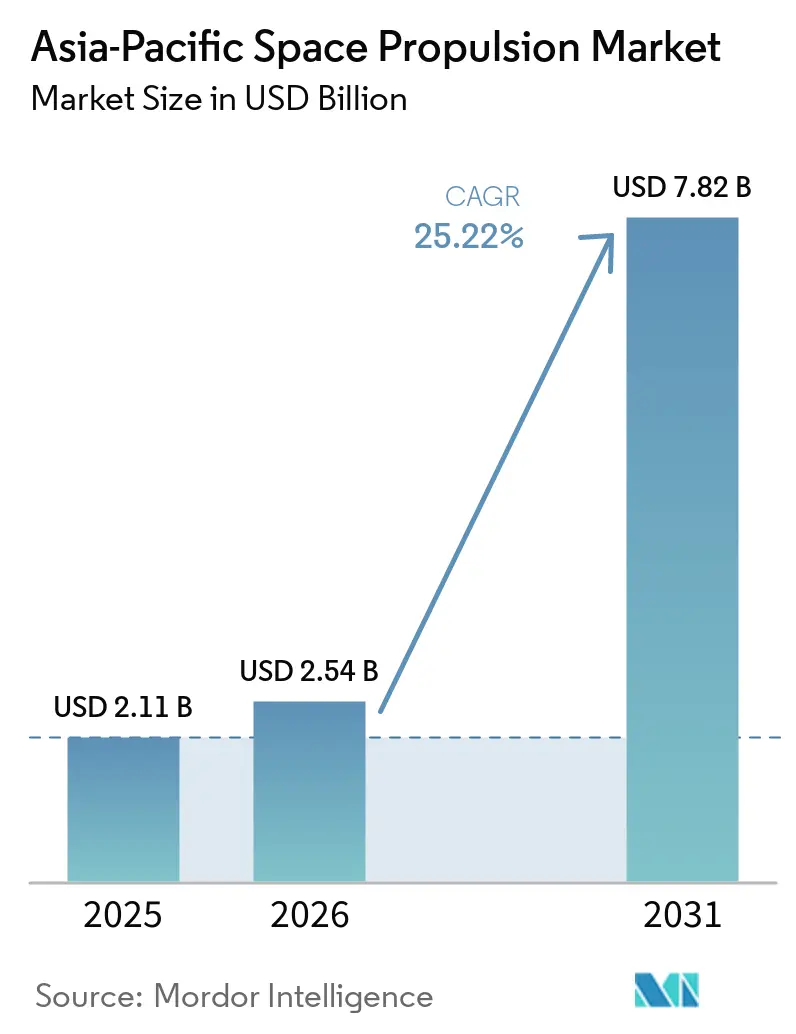
| Base Year Market Size (2025) | USD 2.11 Billion |
| Market Size (2026) | USD 2.54 Billion |
| Market Size (2031) | USD 7.82 Billion |
| Growth Rate (2026 - 2031) | 25.22 % |
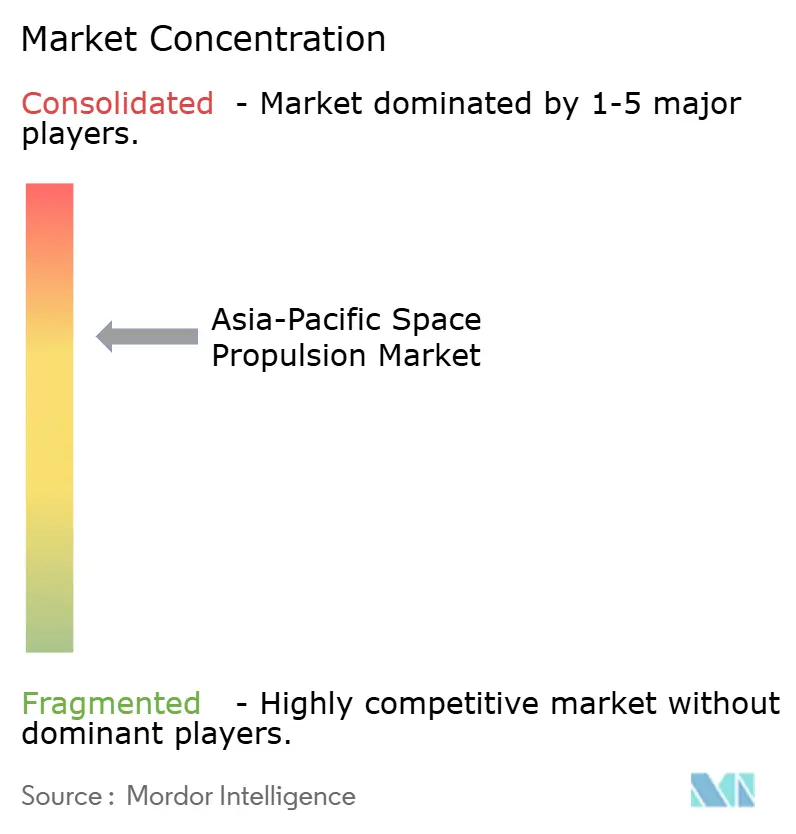
| Market Concentration | Medium |
Major Players *Disclaimer: Major Players sorted in no particular order Image © Mordor Intelligence. Reuse requires attribution under CC BY 4.0. | |
Asia-Pacific Space Propulsion Market Analysis by Mordor Intelligence
The Asia-Pacific space propulsion market size was valued at USD 2.11 billion in 2025 and is forecast to grow from USD 2.11 billion in 2026 to USD 7.82 billion by 2031, at a 25.22% CAGR during the forecast period (2026-2031). Large LEO constellation plans, national space programs, and commercial launch investment are widening the demand base. Chemical systems remain essential for launch vehicles and rapid maneuvers, while electric systems are becoming more common in satellite fleets. Growth will depend on suppliers capable of qualifying hardware, securing test access, and managing propellant logistics. The Asia-Pacific space propulsion market remains demanding because flight-ready systems require long development cycles and close coordination with satellite and launch vehicle programs. Companies with proven mission performance and strong relationships with public agencies have a clear advantage as procurement volumes rise.
Key Report Takeaways
- By propulsion type, liquid propulsion held 47.22% of the regional total in 2025, while electric propulsion is forecast to grow at a 28.42% CAGR through 2031.
- By component, thrusters and rocket motors held 51.11% of the regional total in 2025, while propellant feed systems are forecast to grow at a 26.12% CAGR through 2031.
- By platform, launch vehicles accounted for 53.56% of the regional total in 2025, while satellites are forecast to grow at a 28.92% CAGR through 2031.
- By end user, commercial users held 58.63% of the regional total in 2025 and are forecast to grow at a 26.52% CAGR through 2031.
- By geography, China held 63.77% of the Asia-Pacific space propulsion market in 2025 and is forecast to grow at a 30.63% CAGR through 2031.
Note: Market size and forecast figures in this report are generated using Mordor Intelligence’s proprietary estimation framework, updated with the latest available data and insights as of January 2026.
Asia-Pacific Space Propulsion Market Trends and Insights
Drivers Impact Analysis*
| DRIVER | (~) % IMPACT ON CAGR FORECAST | GEOGRAPHIC RELEVANCE | IMPACT TIMELINE |
|---|---|---|---|
| LEO constellation and satellite deployment | 7.10% | China core, with spillover to India, Japan, and South Korea | Short term (≤ 2 years) |
| National space sovereignty and defense programs | 5.30% | China, India, South Korea, and Japan | Medium term (2-4 years) |
| Commercial launch and reusable vehicle investment | 4.50% | China, South Korea, and India | Medium term (2-4 years) |
| Electric propulsion adoption for lifecycle efficiency | 4.00% | China, India, Japan, and Australia | Medium term (2-4 years) |
| Water, metal, and green propellant qualification pipeline | 2.30% | India, Australia, and Japan | Long term (≥ 4 years) |
| Localized propulsion supply chains and dual-use export resilience | 2.00% | China, India, and South Korea | Long term (≥ 4 years) |
| Source: Mordor Intelligence | |||
LEO Constellation and Satellite Deployment: The Primary Demand Engine
China’s Qianfan and Guowang programs are expanding the planned satellite base for the Asia-Pacific space propulsion market. Qianfan’s first phase targets 1,296 satellites by 2029, while the combined programs target more than 39,000 LEO satellites. Constellation operators need propulsion for orbit raising, station keeping, collision avoidance, and end-of-life disposal. Their procurement model also favors standardized systems that can be installed across common satellite buses. CAST’s Fifth Academy 502 Institute had recorded more than 26,000 hours of on-orbit operation across over 100 Hall-thruster-equipped satellites as of October 2025. It had also received orders for more than 300 systems from over 10.00 satellite integrators, with annual output planned to reach 1,400 systems by the end of 2026.[1]
The scale of these programs changes the production requirements for propulsion suppliers. Satellite builders need repeatable unit performance and predictable delivery schedules rather than individually engineered systems. This raises the importance of common component interfaces, controlled propellant supply, and qualified power processing units. It also supports the use of Hall-effect thrusters in satellites where modest thrust and efficient propellant use are more important than rapid maneuvers. The Asia-Pacific space propulsion market can therefore benefit from higher unit volumes even when the value of propulsion hardware per satellite declines. Suppliers that qualify a design across several satellite buses may gain a durable place in recurring constellation procurement.
National Space Sovereignty and Defense Programs: Propulsion as a Strategic Asset
Government programs treat propulsion capability as a strategic technology because it supports launch access, national missions, and defense applications. China, India, South Korea, and Japan are using public programs to strengthen domestic propulsion design and testing capability. These programs create demand for engines, attitude-control thrusters, and satellite propulsion that is less sensitive to short-term commercial launch cycles. They also help smaller suppliers demonstrate systems through government missions before approaching commercial customers. The Asia-Pacific space propulsion market benefits when national programs fund infrastructure and reduce the technical risk of new systems. The resulting flight record can improve a supplier's credibility for future export and commercial opportunities.
South Korea's lunar lander program shows how this support can extend across a complete propulsion system. In December 2025, Hanwha Aerospace signed a KRW 103.30 billion (USD 77.21 million) contract, as stated in the supplied material, for USD 7 million, to develop, assemble, and test the landing engine and attitude-control thrusters for a 2032 lunar lander.[2] The work covers a bipropellant MMH-NTO architecture and gives the company a role in a long-duration national program. India is pursuing a parallel approach through access to ISRO facilities and the IN-SPACe framework. These programs help domestic companies build technical heritage in green propulsion and other emerging designs. Government decisions on qualification, technology transfer, and domestic sourcing now carry as much weight as launch demand in shaping regional capability.
Commercial Launch and Reusable Vehicle Investment: Propulsion Economics at Scale
Commercial launch investment is increasing demand for engines and related propulsion hardware across China, India, and South Korea. Reusable vehicle programs place greater emphasis on engine life, thermal management, inspection, and restart capability. This changes product requirements because engines designed for repeated use must withstand cyclic loads rather than one flight. Commercial developers also need production capacity that can support the planned launch cadence. The Asia-Pacific space propulsion market gains when launch companies move from prototype programs to recurring vehicle production. This transition supports demand for main engines, upper-stage engines, attitude-control systems, valves, feed systems, and thermal-control hardware.
CAS Space conducted the inaugural Kinetica-2 Y1 flight from Jiuquan on March 30, 2026. The liquid-propellant vehicle used 9 engines and has a stated payload capacity of 12,000 kg to LEO.[3] The company also announced a Zhejiang Superfactory with a planned annual capacity of 12.00 Kinetica-2-class rockets. This project indicates a shift toward batch production of commercial launch vehicles in China. Localized supply chains can also limit disruption from dual-use export controls and improve access to qualified components. These conditions create opportunities for domestic propulsion suppliers to gain production experience alongside launch vehicle integrators.
Electric Propulsion Adoption for Lifecycle Efficiency: Mass Budget Wins
Electric propulsion is gaining importance because it can reduce the propellant mass required for satellite maneuvers. This is particularly relevant for all-electric and hybrid satellites used in large constellations. The supplied draft states that an all-electric satellite can carry 30% to 40% more payload mass than a chemically propelled satellite of the same total mass. This payload advantage can affect mission economics when operators procure satellites in large batches. The Asia-Pacific space propulsion market is therefore seeing demand for Hall-effect thrusters, gridded-ion thrusters, power processing units, and compatible propellant systems. Electric systems also support the longer operational life and orbit-management needs of commercial satellite fleets.
JAXA’s Engineering Test Satellite-9 uses a 6-kW-class Hall thruster subsystem developed through its research program since 2015. The system demonstrates medium-power electric propulsion for geostationary applications.[4] Krypton-based Hall thrusters can lower propellant costs relative to xenon systems, although the supplied material notes that power processing units must accommodate different ionization characteristics. This creates a component challenge because the regional supplier base for power processing units is smaller than the base for thrusters. Water, metal, and green propellant systems may create further opportunities after qualification. Adoption will depend on test capacity, in-orbit performance, and the ability to integrate these systems with satellite power architecture.
Restraints Impact Analysis*
| RESTRAINT | (~) % IMPACT ON CAGR FORECAST | GEOGRAPHIC RELEVANCE | IMPACT TIMELINE |
|---|---|---|---|
| Qualification and mission-assurance cost | -3.30% | Regional, with acute impact on India, South Korea, and Australia | Medium term (2-4 years) |
| Space debris and policy complexity | -2.40% | Global, concentrated in low Earth orbit corridors above 500.00 km | Medium term (2-4 years) |
| Fragmented standards and limited regional test capacity | -1.90% | Asia-Pacific-wide, with acute impact on Southeast Asia and Oceania | Long term (≥ 4 years) |
| Propellant logistics and cross-border export controls | -1.60% | Asia-Pacific-wide, especially India-United States and Korea-United States frameworks | Medium term (2-4 years) |
| Source: Mordor Intelligence | |||
Qualification and Mission-Assurance Cost: The Hidden Tax on Innovation
New propulsion systems face long qualification timelines before their first commercial flight. The supplied material states that green propellant, water electrolysis, and metal-propellant electric systems can require 3 to 5 years and tens of millions of USD for qualification. These requirements are difficult for smaller companies with limited financing and limited flight heritage. The Asia-Pacific space propulsion market also has limited access to accredited thermal-vacuum chambers capable of validating complete propulsion modules. Companies without their own facilities may face longer test queues and higher project costs. This can delay market entry even when a propulsion design has completed laboratory testing.
The qualification issue extends beyond hardware performance. Satellite integrators that use government rideshare opportunities must meet review processes for mission assurance, safety, and debris mitigation. Those requirements often favor suppliers with prior flight data and established relationships with program authorities. Fragmented technical standards make it harder for a component supplier to obtain a single approval across several national programs. Restricted access to test sites can limit the practical value of new propellant chemistry. The Asia-Pacific space propulsion market may consequently reward companies that combine technology development with early investment in test access and compliance capability.
Space Debris and Policy Complexity: A Regulatory Headwind Gaining Force
Crowded LEO corridors are making de-orbit capability an increasingly important requirement for satellites. Satellites operating above 500 km require propulsion capable of supporting disposal maneuvers at the end of a mission. This adds propulsion hardware, propellant, power, and integration work to spacecraft that might otherwise use simpler systems. China’s 2025-2027 action plan identifies de-orbit propulsion capability as a compliance priority in the supplied material. Japan’s Space Activities Act requires debris mitigation plans as part of the launch licensing process. The Asia-Pacific space propulsion market must therefore meet both mission-performance and regulatory requirements.
Policy complexity increases when operators procure equipment across national borders. Dual-use export controls under ITAR and the MTCR can delay component imports by 6 to 18 months, according to the supplied material. These delays can disrupt satellite production and launch schedules. They can also encourage companies in China and India to develop domestic suppliers, even where imported hardware may have been technically suitable. The requirement for accountable disposal may strengthen long-term demand for propulsion, but it also raises cost and qualification burdens. Companies that can provide compliant designs and documentation may be better placed to serve constellation operators.
*Our forecasts treat driver/restraint impacts as directional, not additive. The impact forecasts reflect baseline growth, mix effects, and variable interactions.
Segment Analysis
By Propulsion: Chemical Breadth Meets Electric Acceleration
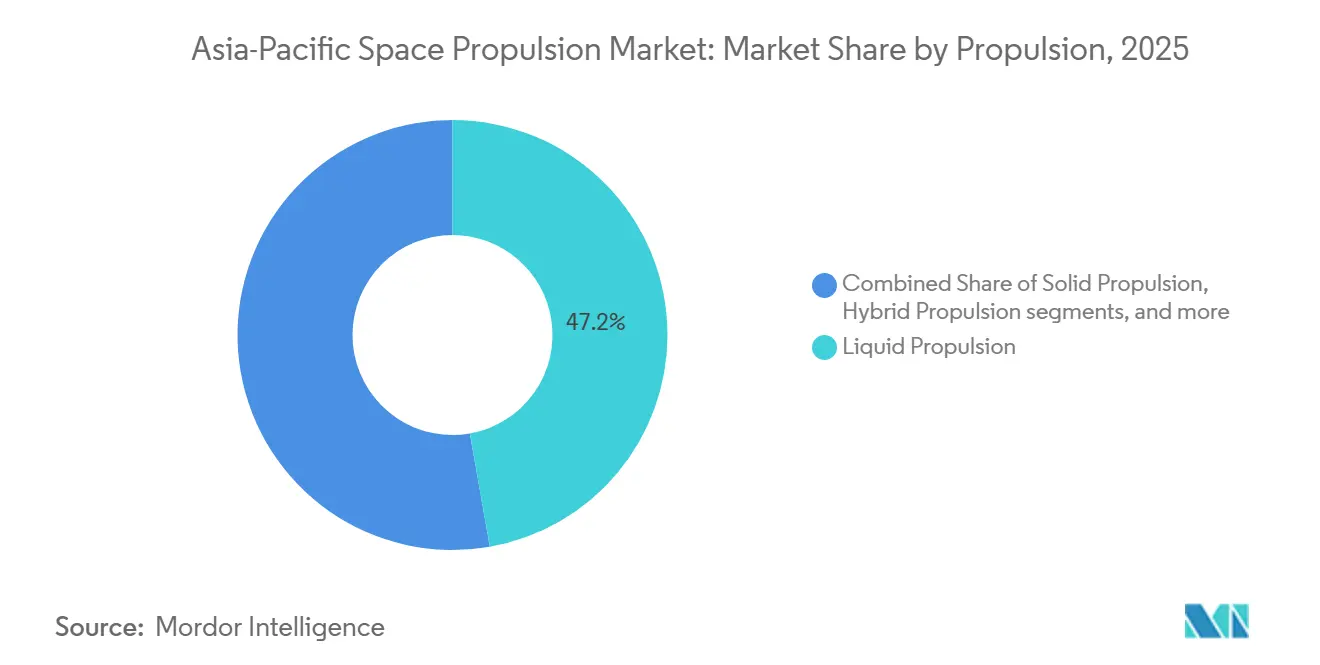
Liquid propulsion held 47.22% of the Asia-Pacific space propulsion market share in 2025. Bipropellant chemical systems remain important for launch-vehicle upper stages and for missions that require high-thrust maneuvers. China’s Long March series and India’s GSLV Mk III illustrate the continued role of liquid propulsion in medium and heavy launch systems. Solid propulsion remains relevant in military and tactical missions where storage and readiness are important. Hybrid systems are receiving research attention in Australia and Japan for upper-stage applications because of their operational safety characteristics. These chemical systems continue to serve mission profiles where electric propulsion cannot provide the required thrust level.
Electric propulsion is forecast to grow at a 28.42% CAGR through 2031, the highest rate within this segmentation. Hall-effect and gridded-ion thrusters support satellite operators that prioritize mass efficiency and long-duration orbit management. CAST’s 502 Institute introduced a krypton-compatible product line with power ranging from 300 W to 5,000 W, and planned an annual capacity of 1,400 systems by the end of 2026. Krypton systems can support a lower-cost propellant approach, but they require suitable power processing units. Electrospray and magnetoplasmadynamic thrusters serve precision small-satellite niches. The space propulsion industry is likely to use chemical and electric systems together because each approach addresses different mission requirements.

By Component: Thrusters Lead, Feed Systems Accelerate
Thrusters and rocket motors held 51.11% of the component segment in 2025. Thruster specifications influence satellite bus design by affecting available volume, power demand, thermal conditions, and propellant storage. This makes the thrust-generation hardware a central part of the spacecraft propulsion module. Launch vehicles also depend on engines and rocket motors for their primary mission. The Asia-Pacific space propulsion market, therefore, places substantial value on components that directly generate thrust. Suppliers with proven thruster performance can build relationships with satellite integrators and launch vehicle manufacturers.
Propellant feed systems are forecast to grow at a 26.12% CAGR through 2031. Alternative propellants require revised valves, tanks, lines, pressure controls, and other feed architectures. Constellation-scale production also requires lightweight, precise components that can be produced consistently at higher volumes. Power processing units are another critical component, as electric thrusters require systems that control voltage, current, and ionization. The supplier base for these units remains less developed than that for thrusters in the region. Nozzles and thermal-control systems have more standardized roles and can face pricing pressure as purchases move toward catalog-based procurement. The space propulsion industry will need component suppliers that can meet both flight-quality controls and volume-manufacturing requirements.
By Platform: Launch Vehicles Anchor, Satellites Define Future Trajectory
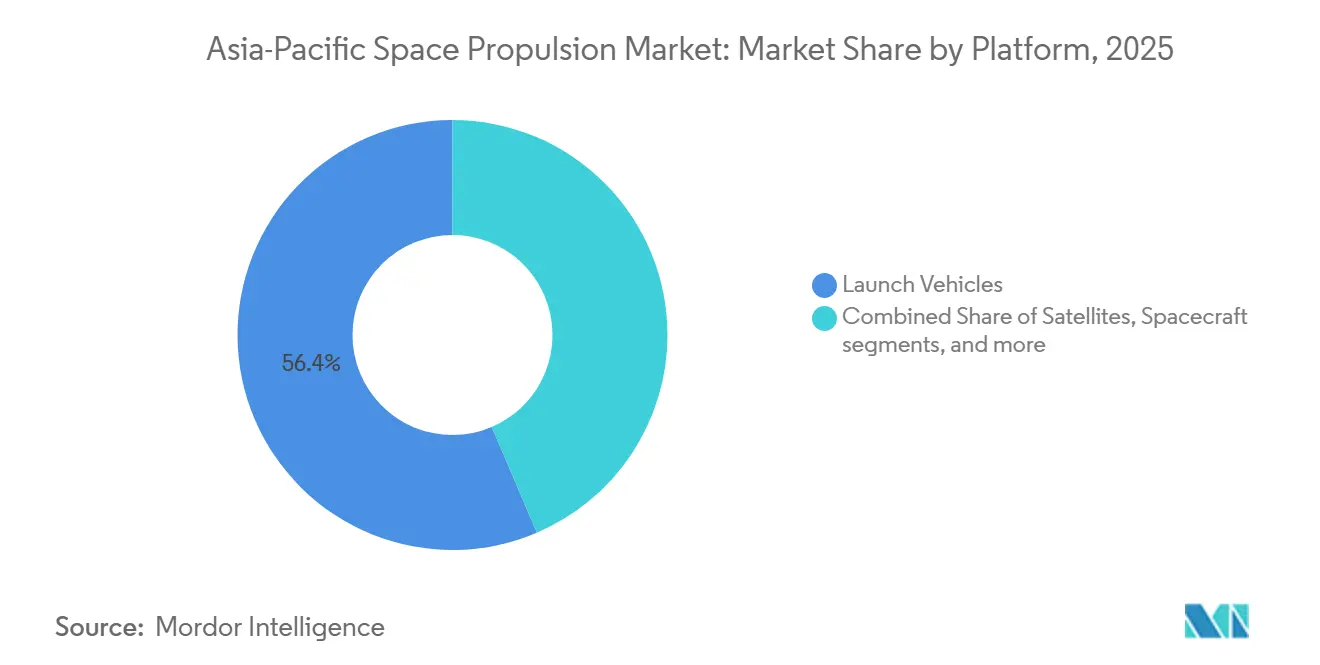
Launch vehicles accounted for 53.56% of the regional total in 2025. State and commercial launch programs in China require propulsion systems for main and upper stages, as well as for attitude control. This provides demand across engines, tanks, valves, nozzles, and feed systems. Launch vehicle propulsion systems have long development cycles because a failure can affect the entire mission. Its large share reflects the size and complexity of chemical propulsion systems used to place spacecraft into orbit. It also reflects the continued expansion of national and commercial launch capability across the region.
Satellites are forecast to grow at a 28.92% CAGR through 2031. Constellation deployment is shifting from planned satellite counts to large procurement batches, thereby increasing total demand for in-space propulsion. Each satellite may have a smaller propulsion unit than a launch vehicle, but large fleets can create considerable recurring demand. Satellite systems require propulsion for orbit raising, station keeping, collision avoidance, and disposal. Spacecraft, including crewed vehicles, orbital service platforms, and lunar landers, remain a smaller but strategic platform group. South Korea’s 2032 lunar lander work illustrates how deep-space programs can develop spacecraft-grade propulsion capability. The Asia-Pacific space propulsion market will therefore depend on both launch vehicle programs and satellite production rates.
By End User: Commercial Dominance with a Deepening Government Undercurrent
Commercial users held 58.63% of the regional total in 2025. The segment is also forecast to grow at a 26.52% CAGR through 2031. China’s constellation build-out is a major source of commercial demand, although private space activity is also developing in India and South Korea. Commercial buyers need reliable systems that are on schedule and suitable for standardized satellite or launch platforms. Their purchasing decisions place greater emphasis on manufacturing scale and cost control. This makes commercial procurement an important source of demand for propulsion suppliers that can move beyond low-volume development work.
Government and civil users continue to support national satellite programs, exploration projects, and research missions. ISRO, JAXA, and KARI act as anchor customers that can help suppliers establish flight heritage before commercial sales. In March 2026, Bellatrix Aerospace raised USD 20 million in a pre-Series B round after securing its first large overseas commercial propulsion customer. Military demand is less visible because propulsion technologies can be subject to export controls and classified programs. These programs can still support domestic technical capability and later commercial applications. Public infrastructure and missions lower the risk for private companies before they serve commercial customers. This keeps government procurement relevant even when commercial users represent the larger source of demand.
Geography Analysis
China held 63.77% of the Asia-Pacific space propulsion market share in 2025 and is forecast to grow at a 30.63% CAGR through 2031. Qianfan’s first phase targets 1,296 satellites by 2029, and its wider constellation activity supports demand for Hall-effect thrusters for orbit raising and station keeping. CAST’s Fifth Academy 502 Institute plans to scale Hall-thruster output to 1,400 systems annually by the end of 2026. CAS Space’s Kinetica-2 made its inaugural flight in March 2026 with 9 engines and a stated 12,000 kg LEO payload capacity. China combines strong domestic demand for satellites with state-linked and commercial launch-vehicle development. This gives the country the broadest production base in the regional propulsion landscape.
India and South Korea form an important secondary growth group in the Asia-Pacific space propulsion market. India’s IN-SPACe framework gives private companies access to ISRO test infrastructure and rideshare opportunities. This improves the route from ground testing to in-orbit demonstration for local propulsion developers. South Korea’s Hanwha Aerospace holds a KRW 103.30 billion (USD 77.21 million) contract, valued at USD 71 million for supplied materials, for the 2032 lunar lander propulsion system. In July 2025, Hanwha also received a KRW 24 billion (USD 18.11 million) technology transfer agreement, stated as USD 16.60 million, related to Nuri launch vehicle manufacturing and launch activity. These steps give South Korea a more formal path from public launch programs to private-sector participation. Both countries are building capability through policy support, test access, and public missions.
Japan and Australia support advanced propulsion research and specialized technologies. JAXA continues to develop medium-power electric propulsion through the ETS-9 program. ThrustMe signed commercial agreements worth more than EUR 10 million (USD 11.68 million) in April 2026 to equip 40 Japanese Earth observation satellites with iodine electric propulsion. Neumann Space is advancing metal-propellant pulsed plasma technology focused on orbital debris mitigation. New Zealand and Singapore contribute through launch services, satellite assembly, and regulatory environments rather than large-scale propulsion manufacturing. These countries can support supply chain diversification as regional space programs expand.
Competitive Landscape
The Asia-Pacific space propulsion market is moderately concentrated at the prime contractor level. China’s state-linked entities, including CASC and its academies, play a major role in domestic demand for launch vehicle propulsion. The commercial in-space propulsion segment is more fragmented because smaller companies can compete by focusing on specific technologies and satellite applications. Chinese manufacturers are building vertically integrated design, manufacturing, and test capabilities. Indian and South Korean entrants often use shared government test infrastructure to manage capital needs. This difference gives large Chinese organizations an advantage in production scale, while newer entrants seek positions in green propellant and electric propulsion.
Flight heritage remains an important competitive factor because propulsion hardware must meet strict mission-assurance requirements. Companies with validated performance can use that record when competing for government and commercial procurement. CAST’s Hall-thruster activity demonstrates the value of a large installed base and industrial output capacity. CAS Space’s Kinetica-2 program presents a separate strategy centered on repeated vehicle production for commercial launch services. Hanwha Aerospace’s lunar lander contract broadens its position from launch vehicle participation to deep-space propulsion. Bellatrix Aerospace is also pursuing partnerships and new funding as it scales electric and chemical satellite propulsion. The competitive picture is being shaped by national programs, production capacity, and the ability to prove systems in flight.
Western suppliers such as Moog Inc., Northrop Grumman Corporation, L3Harris Technologies, Inc., Safran SA, and Honeywell International Inc. retain positions through flight heritage and established government relationships. They face increasing pressure from domestic Asian suppliers as local alternatives qualify for similar mission profiles. In-orbit servicing and refueling remain open opportunities because the supplied material identifies no commercially operational regional refueling system. The rules for transferring propellant in orbit are also still developing. INNOSPACE completed a 420-second ground combustion test of its LiMEK-04 liquid methane engine in June 2026, a step toward reusable small-launch propulsion. Companies are also working on krypton Hall thrusters, water-electrolysis micro-propulsion, and green chemical systems. Suppliers are competing through test access, qualification history, manufacturing capacity, and their fit with new satellite and launch vehicle programs.
Asia-Pacific Space Propulsion Industry Leaders
-
China Aerospace Science and Technology Corporation
-
Indian Space Research Organisation
-
IHI Aerospace Co., Ltd.
-
Mitsubishi Electric Corporation
-
Hanwha Aerospace Co., Ltd.
- *Disclaimer: Major Players sorted in no particular order
Recent Industry Developments
- September 2026: Hanwha Aerospace began assembling a reusable launch vehicle demonstrator under KARI's leadership, targeting a 2028 flight test to demonstrate engine thrust control and vertical landing.
- June 2026: INNOSPACE completed a 420-second ground combustion test of its LiMEK-04 liquid methane engine for the Hanbit-Micro kick stage, validating a dual-propellant regenerative cooling architecture.
- March 2026: CAS Space conducted the inaugural Kinetica-2 flight from Jiuquan. The vehicle uses 9 engines, has a stated capacity of 12,000 kg to LEO, and is linked to a planned Zhejiang Super factory with an annual capacity of 12 rockets.
- March 2026: Bellatrix Aerospace closed a USD 20 million pre-Series B round after securing its first large overseas commercial propulsion customer.
Asia-Pacific Space Propulsion Market Report Scope
The Asia-Pacific space propulsion market comprises the regional industry involved in the design, manufacture, integration, testing, and maintenance of systems, engines, and components that accelerate and maneuver spacecraft, satellites, and launch vehicles in outer space. The market includes all hardware, software, and support services required to generate thrust, perform orbital maneuvers, control spacecraft attitude, and execute deep-space transfers.
The Asia-Pacific space propulsion market is segmented by propulsion type, component, platform, end user, and geography. By propulsion type, the market is segmented into solid propulsion, liquid propulsion, hybrid propulsion, electric propulsion, and others. By component, the market is segmented into thrusters and rocket motor, propellant feed systems, power processing units, nozzles, propulsion thermal-control systems, and others. By platform, the market is segmented into satellites, launch vehicles, spacecraft, and others. By end user, the market is segmented into commercial, government and civil, and military. The report also covers the market sizes and forecasts for the Asia-Pacific space propulsion market in seven countries across the region. For each segment, the market size is provided in terms of value (USD).
| Solid Propulsion | |
| Liquid Propulsion | Monopropellant |
| Bipropellant | |
| Hybrid Propulsion | |
| Electric Propulsion | Hall-Effect Thrusters |
| Gridded Ion Thrusters | |
| Electrospray Thrusters | |
| Pulsed Plasma Thrusters | |
| Magnetoplasmadynamic Thrusters | |
| Others |
| Thrusters and Rocket Motor |
| Propellant Feed Systems |
| Power Processing Units |
| Nozzles |
| Propulsion Thermal-Control Systems |
| Others |
| Satellites |
| Launch Vehicles |
| Spacecraft |
| Others |
| Commercial |
| Government and Civil |
| Military |
| Australia |
| China |
| India |
| Japan |
| New Zealand |
| Singapore |
| South Korea |
| Rest of Asia-Pacific |
| By Propulsion Type | Solid Propulsion | |
| Liquid Propulsion | Monopropellant | |
| Bipropellant | ||
| Hybrid Propulsion | ||
| Electric Propulsion | Hall-Effect Thrusters | |
| Gridded Ion Thrusters | ||
| Electrospray Thrusters | ||
| Pulsed Plasma Thrusters | ||
| Magnetoplasmadynamic Thrusters | ||
| Others | ||
| By Component | Thrusters and Rocket Motor | |
| Propellant Feed Systems | ||
| Power Processing Units | ||
| Nozzles | ||
| Propulsion Thermal-Control Systems | ||
| Others | ||
| By Platform | Satellites | |
| Launch Vehicles | ||
| Spacecraft | ||
| Others | ||
| By End User | Commercial | |
| Government and Civil | ||
| Military | ||
| By Geography | Australia | |
| China | ||
| India | ||
| Japan | ||
| New Zealand | ||
| Singapore | ||
| South Korea | ||
| Rest of Asia-Pacific | ||
Market Definition
- Application - Various applications or purposes of the satellites are classified into communication, earth observation, space observation, navigation, and others. The purposes listed are those self-reported by the satellite’s operator.
- End User - The primary users or end users of the satellite is described as civil (academic, amateur), commercial, government (meteorological, scientific, etc.), military. Satellites can be multi-use, for both commercial and military applications.
- Launch Vehicle MTOW - The launch vehicle MTOW (maximum take-off weight) means the maximum weight of the launch vehicle during take-off, including the weight of payload, equipment and fuel.
- Orbit Class - The satellite orbits are divided into three broad classes namely GEO, LEO, and MEO. Satellites in elliptical orbits have apogees and perigees that differ significantly from each other and categorized satellite orbits with eccentricity 0.14 and higher as elliptical.
- Propulsion tech - Under this segment, different types of satellite propulsion systems have been classified as electric, liquid-fuel and gas-based propulsion systems.
- Satellite Mass - Under this segment, different types of satellite propulsion systems have been classified as electric, liquid-fuel and gas-based propulsion systems.
- Satellite Subsystem - All the components and subsystems which includes propellants, buses, solar panels, other hardware of satellites are included under this segment.
| Keyword | Definition |
|---|---|
| Attitude Control | The orientation of the satellite relative to the Earth and the sun. |
| INTELSAT | The International Telecommunications Satellite Organization operates a network of satellites for international transmission. |
| Geostationary Earth Orbit (GEO) | Geostationary satellites in Earth orbit 35,786 km (22,282 mi) above the equator in the same direction and at the same speed as the earth rotates on its axis, making them appear fixed in the sky. |
| Low Earth Orbit (LEO) | Low Earth Orbit satellites orbit from 160-2000km above the earth, take approximately 1.5 hours for a full orbit and only cover a portion of the earth’s surface. |
| Medium Earth Orbit (MEO) | MEO satellites are located above LEO and below GEO satellites and typically travel in an elliptical orbit over the North and South Pole or in an equatorial orbit. |
| Very Small Aperture Terminal (VSAT) | Very Small Aperture Terminal is an antenna that is typically less than 3 meters in diameter |
| CubeSat | CubeSat is a class of miniature satellites based on a form factor consisting of 10 cm cubes. CubeSats weigh no more than 2 kg per unit and typically use commercially available components for their construction and electronics. |
| Small Satellite Launch Vehicles (SSLVs) | Small Satellite Launch Vehicle (SSLV) is a three-stage Launch Vehicle configured with three Solid Propulsion Stages and a liquid propulsion-based Velocity Trimming Module (VTM) as a terminal stage |
| Space Mining | Asteroid mining is the hypothesis of extracting material from asteroids and other asteroids, including near-Earth objects. |
| Nano Satellites | Nanosatellites are loosely defined as any satellite weighing less than 10 kilograms. |
| Automatic Identification System (AIS) | Automatic identification system (AIS) is an automatic tracking system used to identify and locate ships by exchanging electronic data with other nearby ships, AIS base stations, and satellites. Satellite AIS (S-AIS) is the term used to describe when a satellite is used to detect AIS signatures. |
| Reusable launch vehicles (RLVs) | Reusable launch vehicle (RLV) means a launch vehicle that is designed to return to Earth substantially intact and therefore may be launched more than one time or that contains vehicle stages that may be recovered by a launch operator for future use in the operation of a substantially similar launch vehicle. |
| Apogee | The point in an elliptical satellite orbit which is farthest from the surface of the earth. Geosynchronous satellites which maintain circular orbits around the earth are first launched into highly elliptical orbits with apogees of 22,237 miles. |
Research Methodology
Mordor Intelligence follows a four-step methodology in all our reports.
- Step-1: Identify Key Variables: In order to build a robust forecasting methodology, the variables and factors identified in Step-1 are tested against available historical market numbers. Through an iterative process, the variables required for market forecast are set and the model is built on the basis of these variables.
- Step-2: Build a Market Model: Market-size estimations for the historical and forecast years have been provided in revenue and volume terms. For sales conversion to volume, the average selling price (ASP) is kept constant throughout the forecast period for each country, and inflation is not a part of the pricing.
- Step-3: Validate and Finalize: In this important step, all market numbers, variables and analyst calls are validated through an extensive network of primary research experts from the market studied. The respondents are selected across levels and functions to generate a holistic picture of the market studied.
- Step-4: Research Outputs: Syndicated Reports, Custom Consulting Assignments, Databases & Subscription Platforms.


