
Asia-Pacific Satellite Manufacturing Market Size and Share
Market Overview
| Study Period | 2019 - 2031 |
|---|---|
| Forecast Data Period | 2026 - 2031 |
| Base Year Market Size (2025) | USD 6.92 Billion |
| Market Size (2026) | USD 8.62 Billion |
| Market Size (2031) | USD 25.93 Billion |
| Growth Rate (2026 - 2031) | 24.64 % |
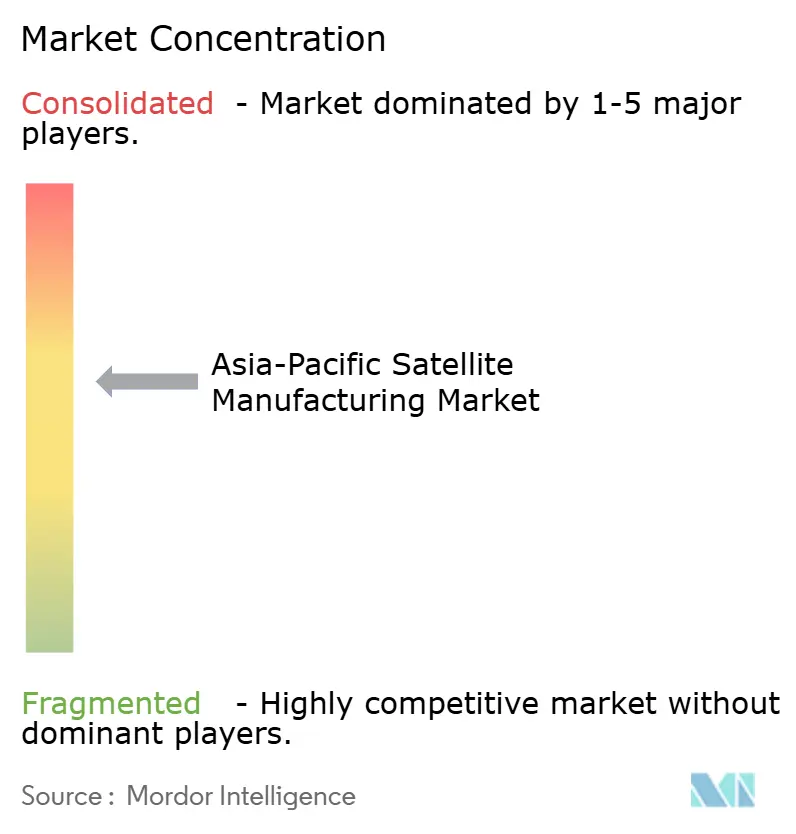
| Market Concentration | Medium |
Major Players *Disclaimer: Major Players sorted in no particular order Image © Mordor Intelligence. Reuse requires attribution under CC BY 4.0. | |
Asia-Pacific Satellite Manufacturing Market Analysis by Mordor Intelligence
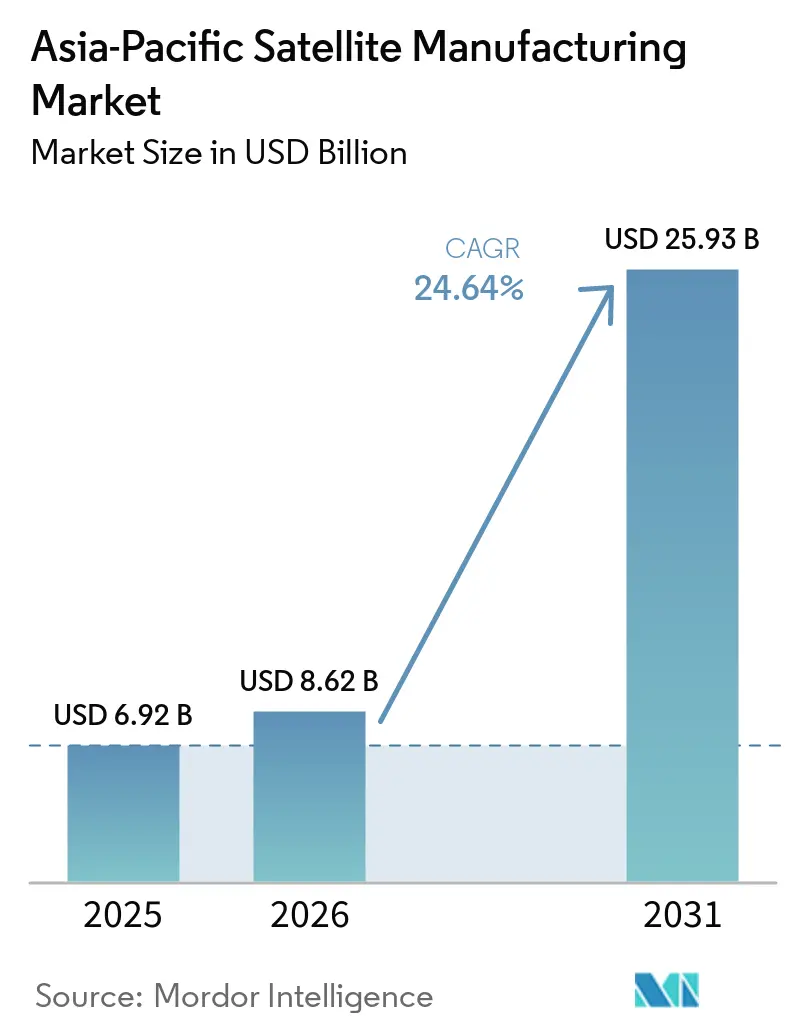
The Asia-Pacific satellite manufacturing market size was valued at USD 6.92 billion in 2025, and is projected to grow from USD 8.62 billion in 2026 to USD 25.93 billion by 2031, registering a CAGR of 24.64% between 2026 and 2031. The Asia-Pacific satellite manufacturing market is being shaped by government constellation programs, commercial broadband networks, and defense requirements for Earth observation. Communication missions remained central to current demand, while standardized spacecraft platforms are changing how manufacturers plan production. Government contracts are also helping suppliers build capabilities that can later serve commercial customers. The market faces constraints from licensing, export controls, spectrum coordination, and uneven testing capacity. Lower launch costs could make more constellations financially viable and broaden the manufacturing opportunity.
Key Report Takeaways
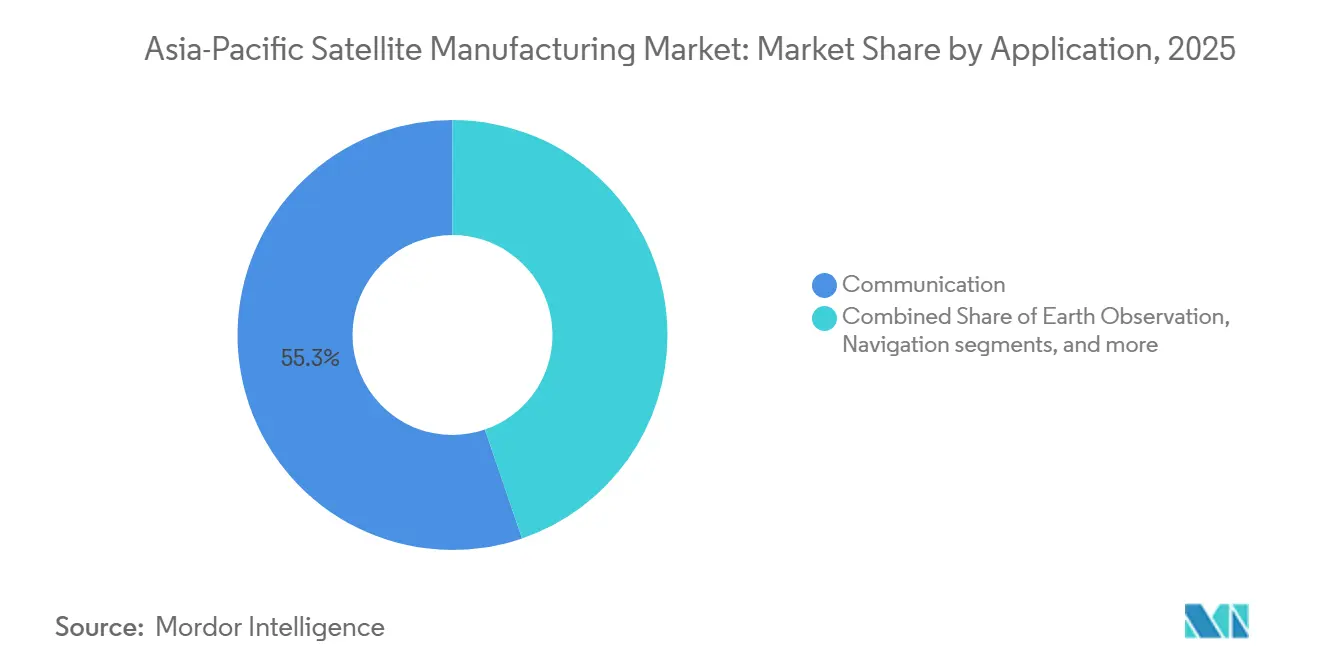
- By application, communication accounted for 55.25% of the Asia-Pacific satellite manufacturing market share in 2025, while Earth observation is forecast to expand at a 25.71% CAGR through 2031.
- By satellite mass, medium satellites accounted for 42.89% of the Asia-Pacific satellite manufacturing market share in 2025, while small satellites are forecast to grow at a 26.52% CAGR through 2031.
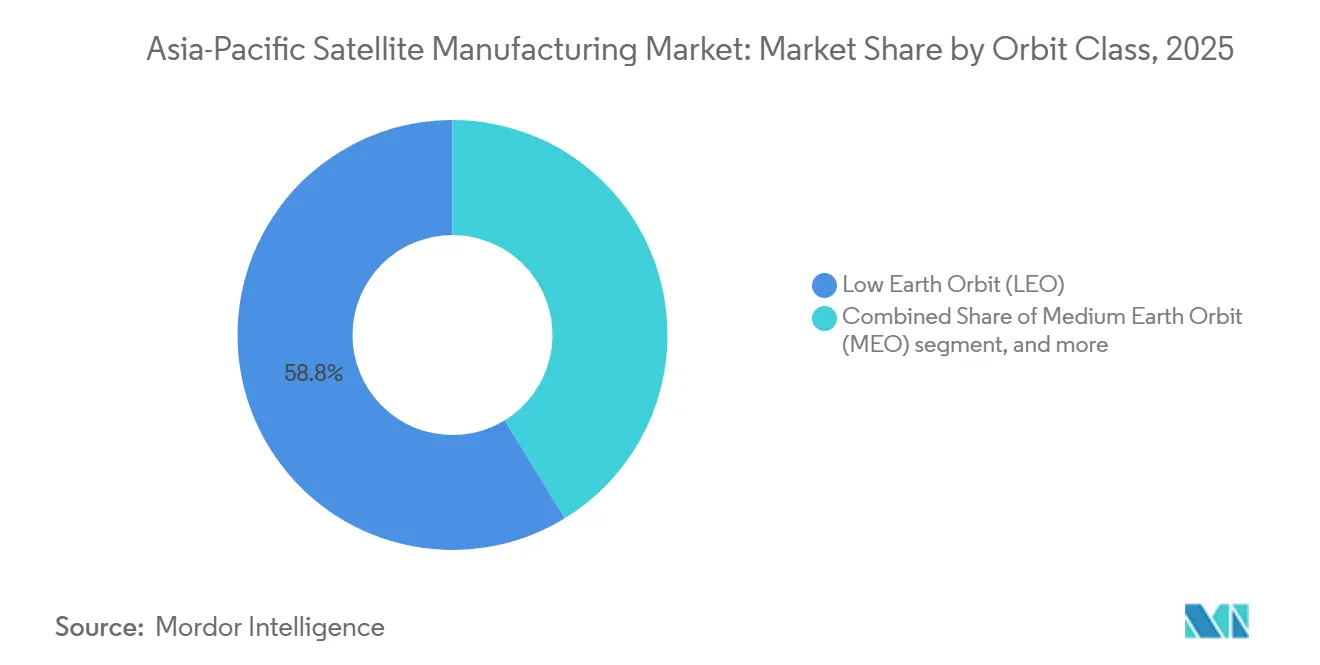
- By orbit class, LEO held 58.75% of the Asia-Pacific satellite manufacturing market share in 2025, while MEO is forecast to expand at a 25.83% CAGR through 2031.
- By end user, commercial operators held 45.32% of the Asia-Pacific satellite manufacturing market share in 2025 and are forecast to grow at a 26.91% CAGR through 2031.
- By geography, China accounted for 68.77% of the Asia-Pacific satellite manufacturing market share in 2025, while India is forecast to grow at a 28.42% CAGR through 2031.
Note: Market size and forecast figures in this report are generated using Mordor Intelligence’s proprietary estimation framework, updated with the latest available data and insights as of January 2026.
Asia-Pacific Satellite Manufacturing Market Trends and Insights
Drivers Impact Analysis*
| DRIVER | (~) % IMPACT ON CAGR FORECAST | GEOGRAPHIC RELEVANCE | IMPACT TIMELINE |
|---|---|---|---|
| Government-led constellation and indigenous manufacturing programs | 6.80% | China, India, South Korea, Japan | Long term (≥ 4 years) |
| LEO broadband, IoT, and non-terrestrial network deployment | 5.90% | China, India, Southeast Asia, ASEAN | Medium term (2-4 years) |
| Earth observation, navigation, and disaster-management demand | 4.20% | China, India, Japan, Australia | Medium term (2-4 years) |
| Satellite miniaturization and standardized bus production | 3.10% | China, South Korea, Japan, India | Short term (≤ 2 years) |
| Domestic control requirements for critical space assets | 2.50% | India, Japan, South Korea, Australia | Medium term (2-4 years) |
| Regional launch cadence compressing unit manufacturing costs | 1.50% | China, India | Short term (≤ 2 years) |
| Source: Mordor Intelligence | |||
Government-Led Constellation and Indigenous Manufacturing Programs
Public procurement remains a major driver of demand in the Asia-Pacific satellite manufacturing market, as sovereign constellations require domestic production capabilities. South Korea ratified a sovereign LEO communications strategy in July 2026, with a KRW 55 trillion (USD 40.88 billion) private-public investment commitment from Hanwha Group for a constellation of up to 512 satellites by 2035. The program aims to increase South Korea’s share of the global space economy from 0.7% to 3.0%. China’s GuoWang and Qianfan programs together target 28,000 satellites, creating a predictable pipeline for spacecraft suppliers. India’s IN-SPACe approved the first fully commercial Earth observation constellation under a public-private partnership model, with Allied Orbits committing INR 1,200 crore (USD 144.21 million) for 12 satellites planned for operation by 2029. These programs allow manufacturers to qualify suppliers, invest in facilities, and seek later commercial orders from a stronger base.[1]
LEO Broadband, IoT and Non-Terrestrial Network Deployment
The Asia-Pacific satellite manufacturing market is seeing increased demand for broadband, Internet of Things, and direct-to-device networks that use LEO spacecraft. Japan’s National Institute of Information and Communications Technology demonstrated satellite- and 5G-integrated network routing in October 2025. The demonstration examined adaptive routing and quality management across satellite connections.[2] Reliance Jio has received a positive technical assessment from IN-SPACe for a proposed 1,600-satellite LEO constellation. Manufacturers, therefore, face demand for platforms that can support evolving network requirements and software-defined functions. The wider use of standardized communications satellites can support larger production batches and reduce the importance of one-off spacecraft designs.
Earth Observation, Navigation and Disaster Management Demand
Demand for Earth observation is strengthening as governments use satellite data for disaster monitoring, civil planning, and defense missions. Japan has committed resources through its Space Strategy Fund for satellite constellations and next-generation technologies. The country’s Basic Policy 2025 targets JPY 8 trillion (USD 50.54 billion) in space-related economic activity in the early 2030s, compared with the 2020 reference level stated in the draft. South Korea launched the NeonSat constellation verification satellite in 2025 and planned 5 mass-produced units in 2026 and another 5 in 2027. The program links domestic spacecraft production with observation requirements and the Nuri launch vehicle.[3] The Asia-Pacific satellite manufacturing market benefits because civil and defense users can draw on related optical and synthetic aperture radar (SAR) capabilities.
Satellite Miniaturization and Standardized Bus Production
Standardized buses and factory-style assembly are changing the cost and delivery model for the Asia-Pacific satellite manufacturing market. GalaxySpace’s Nantong plant produces medium satellites in the 100 kg to 2,000 kg range on a three-day production cycle. The facility reduced full assembly, integration, and testing cycles to 5 days per pair of satellites, according to the supplied draft. Pixxel is developing its Gigapixel facility after its September 2026 USD 100 million Series C financing round. The facility is planned to reach a capacity of 400 satellites per year, while Pixxel’s existing Megapixel facility produces 100 satellites per year.[4] Standardized production can shorten order-to-launch schedules and direct competition toward throughput, quality control, and access to components.
Restraints Impact Analysis*
| RESTRAINT | (~) % IMPACT ON CAGR FORECAST | GEOGRAPHIC RELEVANCE | IMPACT TIMELINE |
|---|---|---|---|
| High capital, testing, and launch costs | -3.50% | Global, acute in Australia and Singapore | Short term (≤ 2 years) |
| Licensing, export-control, and frequency-coordination complexity | -2.80% | India, Japan, South Korea | Medium term (2-4 years) |
| Spectrum congestion and coordination delays for mega-constellations | -1.80% | China, India | Medium term (2-4 years) |
| Limited regional on-orbit servicing and debris-mitigation infrastructure | -1.20% | Regional | Long term (≥ 4 years) |
| Source: Mordor Intelligence | |||
High Capital, Testing and Launch Costs
Capital requirements remain a restraint for satellite projects, especially where manufacturers lack their own testing facilities. A 2025 study found that global launch costs fell from USD 87,023 per kg in 1960 to USD 3,868 per kg in 2025. The study projected a further decline to USD 1,600 per kg by 2030.[5] The supplied draft placed India’s domestic launch cost at USD 13,302 per kg in 2025, reflecting limited launch cadence and non-reusable vehicle architectures. China, Japan, and India have established thermal-vacuum, vibration, and electromagnetic-interference test facilities. Smaller regional economies often depend on external test capacity, which can extend spacecraft schedules and favor firms with strong financial resources.
Licensing, Export-Control and Frequency-Coordination Complexity
Licensing and compliance requirements can delay production plans in the Asia-Pacific satellite manufacturing market. India’s IN-SPACe authorization process and Japan’s Space Activities Act require reviews that can extend program timelines by 12 to 24 months, according to the supplied draft. Export controls can restrict access to radiation-hardened electronics for programs serving certain end customers. International Telecommunication Union filings covering more than 100,000 satellites also create a demanding coordination environment. Resolution 35 requires 10% deployment within 2 years, 50% within 5 years, and 100% within 7 years of the filing date. These milestones can place smaller operators at risk of losing spectrum priority before they achieve commercial scale.
*Our forecasts treat driver/restraint impacts as directional, not additive. The impact forecasts reflect baseline growth, mix effects, and variable interactions.
Segment Analysis
By Application: Communication Holds Current Demand While Earth Observation Expands
Communication satellites accounted for 55.25% of the Asia-Pacific satellite manufacturing market share in 2025. The segment was supported by established GEO broadband programs and expanding LEO broadband orders. Regional constellation plans are moving manufacturers toward batches of comparable communications platforms. These orders can provide manufacturers with steadier production planning than isolated mission contracts. The Asia-Pacific satellite manufacturing industry also relies on communication spacecraft for broadband access in underserved areas. Direct-to-device and non-terrestrial network applications increase demand for platforms that can adapt to changing standards. NICT's 2025 work on satellite and 5G integration illustrates the direction of network design in Japan. The communications segment remains closely linked to launch availability, spectrum coordination, and operator financing.
Earth observation is forecast to expand at a 25.71% CAGR through 2031, making it the fastest-growing application. Defense intelligence requirements are increasingly combined with civilian disaster monitoring and environmental observation needs. The Japanese MoD's constellation project assigned optical imagery work to Axelspace and SAR imagery work to Synspective through March 2031. The contract arrangement shows how government buyers can create reliable demand for specialized observation platforms. Navigation remains strategically important despite a more stable growth profile. Japan is expanding its QZSS constellation from 7 to 11 satellites, and NEC received a JAXA contract in October 2025 to develop the positioning mission payload. Space observation and specialized missions remain relatively small areas, but support research spending by university-linked and specialized manufacturers. The shift toward payload-led designs raises the technical requirements for new entrants.

By Satellite Mass: Medium Platforms Lead While Small Satellites Grow Fastest
Medium satellites accounted for 42.89% of the regional value in 2025. China’s batch-production programs and Japan’s defense constellation platforms supported this position. GalaxySpace shipped 22 medium satellites in 2025 from its Nantong facility. The facility used a three-day production cycle for this class of spacecraft, according to the supplied draft. Medium platforms can accommodate communications, imaging, and constellation missions without the scale of large GEO systems. This creates a practical balance between capability, launch options, and standardized production. The segment is also supported by manufacturers seeking repeatable designs for government and commercial buyers. Its scale places medium-sized satellites at the center of current production plans across the Asia-Pacific satellite manufacturing market.
Small satellites are forecast to expand at a 26.52% CAGR through 2031. Demand comes from SAR nanosatellite constellations and CubeSat programs across South Korea, Australia, India, and Japan. KAI and Hanwha Systems are competing for a KRW 1.42 trillion contract (equivalent to USD 1.02 billion) to produce 40 micro-SAR satellites by 2030. The competition shows South Korea’s shift toward structured small-satellite production. Large satellites remain necessary for GEO communications and classified defense missions. Their growth is slower because some missions are moving toward distributed constellations and smaller platforms. NEC’s planned 2027 optical communications demonstration with an Apex Aries bus also indicates interest in standardized commercial platforms. The category mix is shifting, but each mass class continues to serve distinct mission requirements.
By Orbit Class: LEO Leads Current Production While MEO Gains Strategic Relevance
LEO satellites accounted for 58.75% of the Asia-Pacific satellite manufacturing market size in 2025. The concentration reflects investment in sub-2,000 km constellations for broadband, Earth observation, and communications. China's GuoWang and Qianfan programs together target more than 28,000 satellites. India also has a developing pipeline of LEO broadband and Earth observation constellations. LEO production benefits from short replacement cycles and the use of repeatable spacecraft designs. These factors support factory methods and larger component orders. They also make production plans sensitive to launch readiness and spectrum coordination. The Asia-Pacific satellite manufacturing market, therefore, depends on manufacturers' ability to meet high-volume orders while ensuring mission assurance.
MEO is forecast to expand at a 25.83% CAGR through 2031. Navigation augmentation programs are a primary source of demand for this orbit class. Defense planners also regard MEO as one way to diversify orbital exposure beyond congested LEO bands. GEO platforms remain relevant for high-throughput communications and meteorological missions in China and India. The supplied draft stated that the ITU's equivalent power flux density framework is being reviewed before WRC-27. This review may affect direct-to-device network planning and prompt some agencies to consider alternative orbit architectures. Orbital diversity can therefore become a procurement decision that addresses both operational risk and mission performance.
By End User: Commercial Operators Lead Current Value and Future Growth
Commercial operators held 45.32% of regional value in 2025 and are forecast to expand at a 26.91% CAGR through 2031. This position makes commercial users both the largest current end-user group and the fastest-growing group. Pixxel's September 2026 USD 100 million Series C round showed continued institutional support for commercial spacecraft production. The funding is intended to support the Gigapixel manufacturing facility, the Honeybee hyperspectral constellation, and sovereign Earth observation systems. Commercial orders can improve factory utilization when they are combined with government-backed anchor demand. They may also shorten the time manufacturers need to move from prototype work to repeated production. The Asia-Pacific satellite manufacturing industry is consequently becoming more dependent on access to private capital and long-term operator contracts.
Government and civil users include meteorological agencies, scientific missions, and development-oriented Earth observation programs. India's Allied Orbits arrangement is designed to place a privately managed constellation in line with public demand. Military users are influencing platform requirements beyond their direct procurement volume. The Japanese MoD's project, South Korea's SAR competition, and India's interest in sovereign SAR capabilities are examples from the supplied draft. Defense requirements can raise the standards for secure communications, imaging, and supply-chain control. Manufacturers can then apply those capabilities to civil and commercial missions. The overlap between civilian and military demand is narrowing in platform design. This raises capability requirements across the end-user base while giving qualified suppliers several potential revenue sources.
Geography Analysis
China accounted for 68.77% of the regional value in 2025, giving it the largest regional position. Its position is tied to state-directed capital, integrated industrial clusters, and a domestic mega-constellation pipeline. The supplied draft described the Wenchang super factory as a site capable of producing 1,000 satellites per year. It entered trial production in mid-2026 and is located near Hainan’s commercial launch site. Co-location can reduce the number of transport steps between manufacturing and launch operations. China also has commercial companies seeking external capital and export opportunities. GalaxySpace delivered the Lingzhi-09 CubeSat to Thailand’s GISTDA in August 2026, according to the supplied draft. This move showed an effort to extend Chinese satellite manufacturing into Southeast Asian customer programs.
India is forecast to expand at a 28.42% CAGR through 2031, the highest country growth rate in the regional forecast. The country is moving beyond launch services toward a broader manufacturing base. The supplied draft stated that India’s space economy reached USD 9 billion, and private investment increased from USD 100.5 million in FY2021-22 to USD 618.5 million by March 2026. It also stated that NSIL revenue exceeded INR 3,000 crore (USD 311.55 million) in FY2024-25. NSIL had launched 141 satellites, including 138 for international customers. ICEYE has identified India as a potential manufacturing hub for SAR platforms and is working with Agnikul Cosmos, as described in the draft provided. Domestic-control policies and private investment are supporting the development of local supply chains.
Japan’s Basic Policy 2025 set a JPY 8 trillion target for space-related economic activity in the early 2030s and allocated JPY 1 trillion (USD 6.32 billion) through the Space Strategy Fund. South Korea’s LEO program includes a KRW 55 trillion (USD 40.88 billion) public-private commitment and plans to build cleanrooms in the Southern Advanced Industrial Belt by 2030. Australia is building sovereign capability through the UTS and Space Machines Company Optimus Factory. The facility was established in June 2025 and can produce more than 20 spacecraft per year in the 300 kg class. Singapore remains important for coordinating ground-station and constellation services in Southeast Asia. Vietnam’s LOTUSat-1 program, developed by NEC and Sumitomo Corporation under Japanese official development assistance, provides a technology-transfer model that other Southeast Asian governments are discussing. These countries provide specialized demand, supply-chain links, and collaboration routes outside the two largest regional markets.
Competitive Landscape
The Asia-Pacific satellite manufacturing market is moderately fragmented at the regional level, although national markets are typically dominated by a small group of established suppliers. China combines state-owned primes such as CASC with commercial firms including GalaxySpace, MinoSpace, and Chang Guang Satellite Technology. GalaxySpace filed for IPO tutoring in March 2026 at a CNY 32 billion (USD 4.77 billion) valuation, according to the supplied draft. MinoSpace's STAR Market IPO application was accepted in May 2026. Chang Guang Satellite Technology refiled for an IPO in January 2026 after raising CNY 5 billion (USD 745.81 million) in equity. These actions suggest that commercial producers are seeking capital to expand capacity and support long-duration constellation programs. They also place greater emphasis on revenue generation alongside state-supported orders.
India includes private companies such as Pixxel and Dhruva Space, as well as NSIL technology transfer programs. The supplied draft stated that 118 technology transfer agreements helped private companies build capability without requiring them to replicate ISRO's full research investment. Pixxel's September 2026 financing is a clear example of a company using external capital to develop a larger production site and hyperspectral constellation. Japan's Tri-Sat Constellation combines Mitsubishi Electric, SKY Perfect JSAT, and Mitsui in a special-purpose company supporting the MoD's project. Axelspace and Synspective provide optical and SAR imagery, respectively, in the project. In South Korea, Hanwha Systems operates the Jeju Space Center and is competing for a micro-SAR satellite order. Strategic partnerships, specialized payload capabilities, and access to public programs remain central means of building competitive positions.
Supply-chain localization is a major opportunity for firms making radiation-hardened electronics, inter-satellite laser terminals, and precision optical payloads. Manufacturers also seek stronger onboard processing capabilities to reduce downlink volumes and improve response times for observation applications. Companies that secure multi-year defense imagery contracts can use the resulting revenue visibility to fund capacity that also serves commercial customers. Airbus received an order from Eutelsat in January 2026 for 340 additional OneWeb LEO satellites, bringing its total order count to 440 spacecraft. The order demonstrates the importance of serial production lines for large constellation requirements. Inovor Technologies also signed a joint development agreement with IHI Corporation and Meisei Electric in October 2025 for a maritime domain awareness radio observation satellite. The Asia-Pacific satellite manufacturing market remains competitive because suppliers must combine production scale, access to technology, regulatory readiness, and trusted local partnerships. The Asia-Pacific satellite manufacturing market also requires suppliers to align local sourcing and mission assurance with rapidly changing constellation plans.
Asia-Pacific Satellite Manufacturing Industry Leaders
-
Axelspace Corporation
-
Satrec Initiative Co., Ltd.
-
Chang Guang Satellite Technology Co. Ltd.
-
Indian Space Research Organisation
-
China Aerospace Science and Technology Corporation
- *Disclaimer: Major Players sorted in no particular order
Recent Industry Developments
- September 2026: Pixxel (India) closed a USD 100 million Series C round co-led by Temasek and Seraphim, with participation from 360 ONE Asset and IMM Investment, bringing total funding to USD 195 million. Capital is earmarked for the Gigapixel satellite manufacturing facility, with a capacity of 400 satellites per year, the Honeybee hyperspectral constellation, and sovereign EO system development for international defense and civil customers.
- January 2026: Airbus Defence and Space was awarded a contract by Eutelsat for 340 additional OneWeb LEO satellites, bringing total orders to 440 spacecraft, with production at Airbus’s Toulouse facility on a newly installed serial production line and deliveries commencing by the end of 2026.
- October 2025: Inovor Technologies signed a joint development agreement with IHI Corporation and Meisei Electric for a maritime domain awareness radio observation satellite project, backed by the South Australian Government Economic Recovery Fund.
- June 2025: UTS and Space Machines Company established Australia’s largest industrial-scale spacecraft manufacturing facility, the Optimus Factory, with a capacity of more than 20 spacecraft per year in the 300 kg class, targeting Australian defense and commercial applications.
Asia-Pacific Satellite Manufacturing Market Report Scope
The satellite manufacturing market includes the design, engineering, production, assembly, integration, and testing of satellites and their major subsystems for deployment in Earth orbit or beyond. It covers the manufacture of satellite platforms/buses, payloads, propulsion systems, power systems, thermal and structural components, avionics, communication systems, and other spacecraft subsystems.
The Asia-Pacific satellite manufacturing market report is segmented by application, satellite mass, orbit class, end user, and geography. By application, the market is segmented by communication, Earth observation, navigation, space observation, and others. By satellite mass, the market is segmented into small, medium, and large. By orbit class, the market is segmented into low Earth orbit (LEO), medium Earth orbit (MEO), and geostationary orbit (GEO). By end user, the market is segmented into commercial, government and civil, and military. The report also covers the market sizes and forecasts for the Asia-Pacific satellite manufacturing market in six countries across the region. For each segment, the market size is provided in terms of value (USD).
| Communication |
| Earth Observation |
| Navigation |
| Space Observation |
| Others |
| Small |
| Medium |
| Large |
| Low Earth Orbit (LEO) |
| Medium Earth Orbit (MEO) |
| Geostationary Orbit (GEO) |
| Commercial |
| Government and Civil |
| Military |
| China |
| India |
| Japan |
| South Korea |
| Australia |
| Singapore |
| Rest of Asia-Pacific |
| By Application | Communication |
| Earth Observation | |
| Navigation | |
| Space Observation | |
| Others | |
| By Satellite Mass | Small |
| Medium | |
| Large | |
| By Orbit Class | Low Earth Orbit (LEO) |
| Medium Earth Orbit (MEO) | |
| Geostationary Orbit (GEO) | |
| By End User | Commercial |
| Government and Civil | |
| Military | |
| By Geography | China |
| India | |
| Japan | |
| South Korea | |
| Australia | |
| Singapore | |
| Rest of Asia-Pacific |
Market Definition
- Application - Various applications or purposes of the satellites are classified into communication, earth observation, space observation, navigation, and others. The purposes listed are those self-reported by the satellite’s operator.
- End User - The primary users or end users of the satellite is described as civil (academic, amateur), commercial, government (meteorological, scientific, etc.), military. Satellites can be multi-use, for both commercial and military applications.
- Launch Vehicle MTOW - The launch vehicle MTOW (maximum take-off weight) means the maximum weight of the launch vehicle during take-off, including the weight of payload, equipment and fuel.
- Orbit Class - The satellite orbits are divided into three broad classes namely GEO, LEO, and MEO. Satellites in elliptical orbits have apogees and perigees that differ significantly from each other and categorized satellite orbits with eccentricity 0.14 and higher as elliptical.
- Propulsion tech - Under this segment, different types of satellite propulsion systems have been classified as electric, liquid-fuel and gas-based propulsion systems.
- Satellite Mass - Under this segment, different types of satellite propulsion systems have been classified as electric, liquid-fuel and gas-based propulsion systems.
- Satellite Subsystem - All the components and subsystems which includes propellants, buses, solar panels, other hardware of satellites are included under this segment.
| Keyword | Definition |
|---|---|
| Attitude Control | The orientation of the satellite relative to the Earth and the sun. |
| INTELSAT | The International Telecommunications Satellite Organization operates a network of satellites for international transmission. |
| Geostationary Earth Orbit (GEO) | Geostationary satellites in Earth orbit 35,786 km (22,282 mi) above the equator in the same direction and at the same speed as the earth rotates on its axis, making them appear fixed in the sky. |
| Low Earth Orbit (LEO) | Low Earth Orbit satellites orbit from 160-2000km above the earth, take approximately 1.5 hours for a full orbit and only cover a portion of the earth’s surface. |
| Medium Earth Orbit (MEO) | MEO satellites are located above LEO and below GEO satellites and typically travel in an elliptical orbit over the North and South Pole or in an equatorial orbit. |
| Very Small Aperture Terminal (VSAT) | Very Small Aperture Terminal is an antenna that is typically less than 3 meters in diameter |
| CubeSat | CubeSat is a class of miniature satellites based on a form factor consisting of 10 cm cubes. CubeSats weigh no more than 2 kg per unit and typically use commercially available components for their construction and electronics. |
| Small Satellite Launch Vehicles (SSLVs) | Small Satellite Launch Vehicle (SSLV) is a three-stage Launch Vehicle configured with three Solid Propulsion Stages and a liquid propulsion-based Velocity Trimming Module (VTM) as a terminal stage |
| Space Mining | Asteroid mining is the hypothesis of extracting material from asteroids and other asteroids, including near-Earth objects. |
| Nano Satellites | Nanosatellites are loosely defined as any satellite weighing less than 10 kilograms. |
| Automatic Identification System (AIS) | Automatic identification system (AIS) is an automatic tracking system used to identify and locate ships by exchanging electronic data with other nearby ships, AIS base stations, and satellites. Satellite AIS (S-AIS) is the term used to describe when a satellite is used to detect AIS signatures. |
| Reusable launch vehicles (RLVs) | Reusable launch vehicle (RLV) means a launch vehicle that is designed to return to Earth substantially intact and therefore may be launched more than one time or that contains vehicle stages that may be recovered by a launch operator for future use in the operation of a substantially similar launch vehicle. |
| Apogee | The point in an elliptical satellite orbit which is farthest from the surface of the earth. Geosynchronous satellites which maintain circular orbits around the earth are first launched into highly elliptical orbits with apogees of 22,237 miles. |
Research Methodology
Mordor Intelligence follows a four-step methodology in all our reports.
- Step-1: Identify Key Variables: In order to build a robust forecasting methodology, the variables and factors identified in Step-1 are tested against available historical market numbers. Through an iterative process, the variables required for market forecast are set and the model is built on the basis of these variables.
- Step-2: Build a Market Model: Market-size estimations for the historical and forecast years have been provided in revenue and volume terms. For sales conversion to volume, the average selling price (ASP) is kept constant throughout the forecast period for each country, and inflation is not a part of the pricing.
- Step-3: Validate and Finalize: In this important step, all market numbers, variables and analyst calls are validated through an extensive network of primary research experts from the market studied. The respondents are selected across levels and functions to generate a holistic picture of the market studied.
- Step-4: Research Outputs: Syndicated Reports, Custom Consulting Assignments, Databases & Subscription Platforms.


