
India Construction Equipment Market Size and Share
India Construction Equipment Market Analysis by Mordor Intelligence
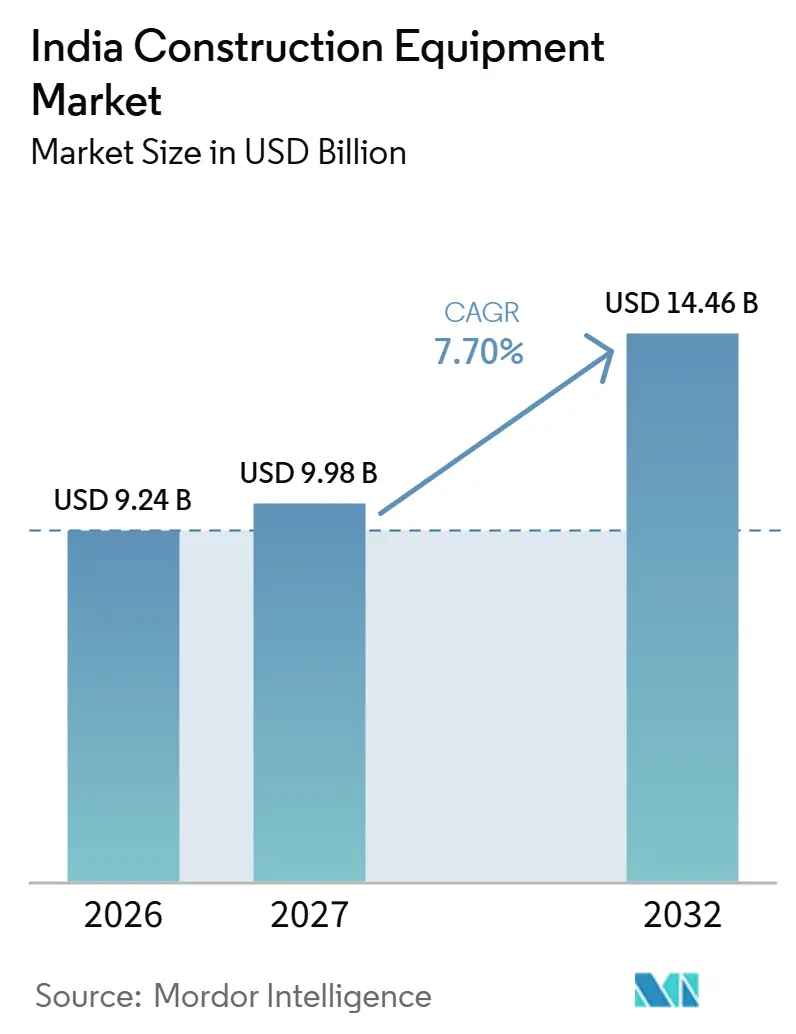
The India construction equipment market size is expected to increase from USD 9.24 billion in 2026 to USD 9.98 billion in 2027 and reach USD 14.46 billion by 2032, growing at a CAGR of 7.7% over 2027-2032.
Construction of infrastructure and housing in India creates equipment work extending from initial excavation into specialized project stages. Road-building demand gains from active work programs, while steel-cost pressure and unavailable workfronts can prevent contractors from using additional machines. Locally made economy models and equipment tailored to demanding jobs give suppliers different ways to serve buyers’ price and operating requirements. Mining expansion in states such as Jharkhand adds a heavier-duty demand tier through high-capacity excavators and haul trucks, which rewards suppliers that differentiate by task rather than by price alone. Price competition alone cannot unlock sites held back by land access or higher construction-input costs, so executable work rather than the project pipeline decides which machine offers convert.
Key Report Takeaways
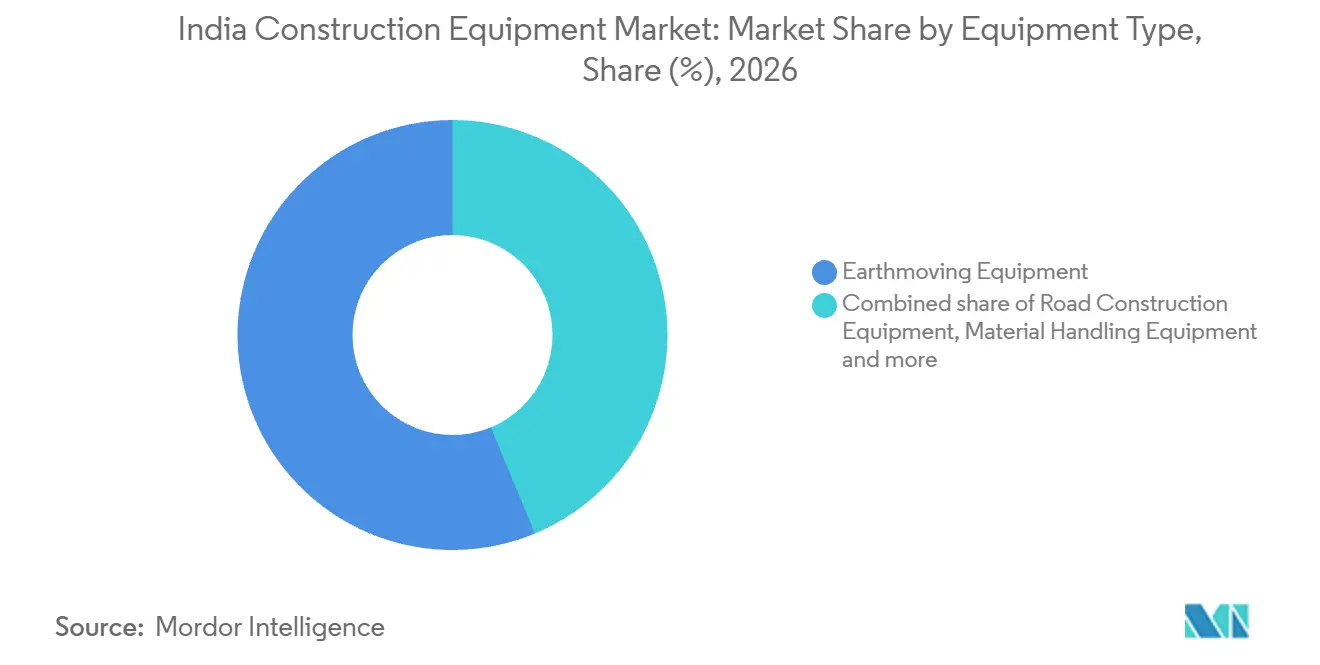
- By equipment type, earthmoving equipment held a 56.26% India construction equipment market share in 2026, while road construction equipment is forecast to grow fastest at a 9.75% CAGR over 2027-2032.
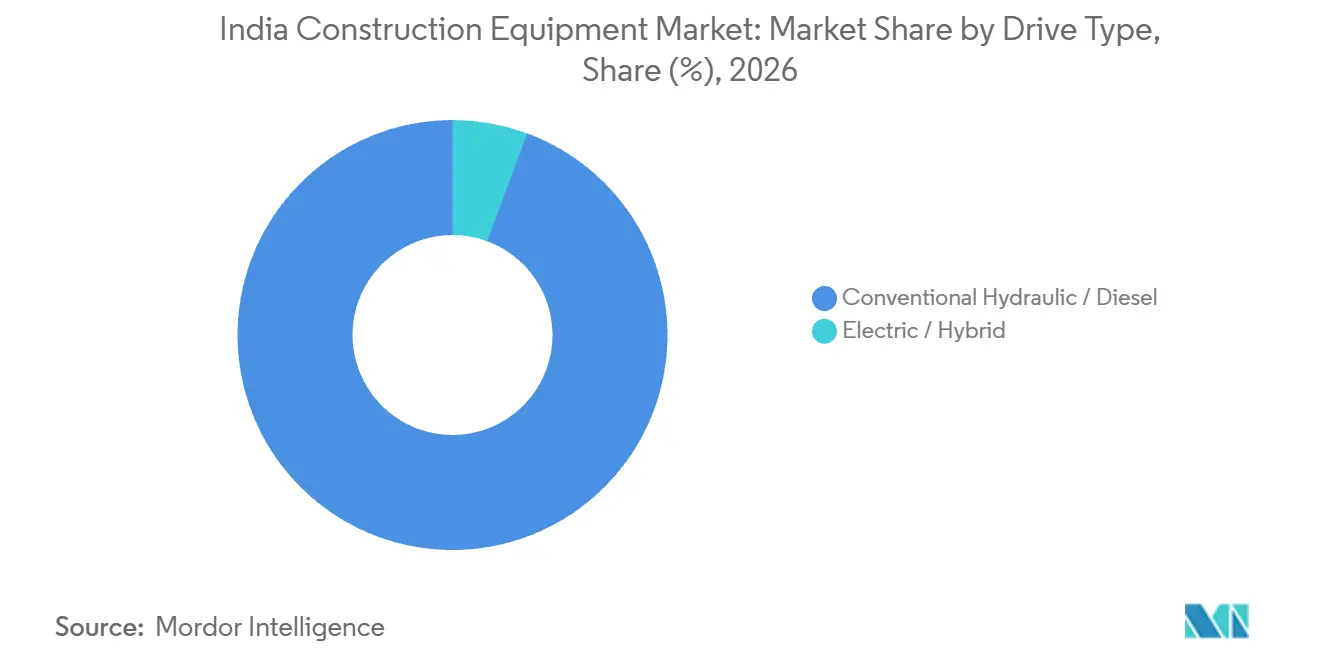
- Across drive types, conventional hydraulic/diesel equipment accounted for a 94.35% share of the India construction equipment market size in 2026, and electric/hybrid equipment is forecast to lead growth at a 15.2% CAGR over 2027-2032.
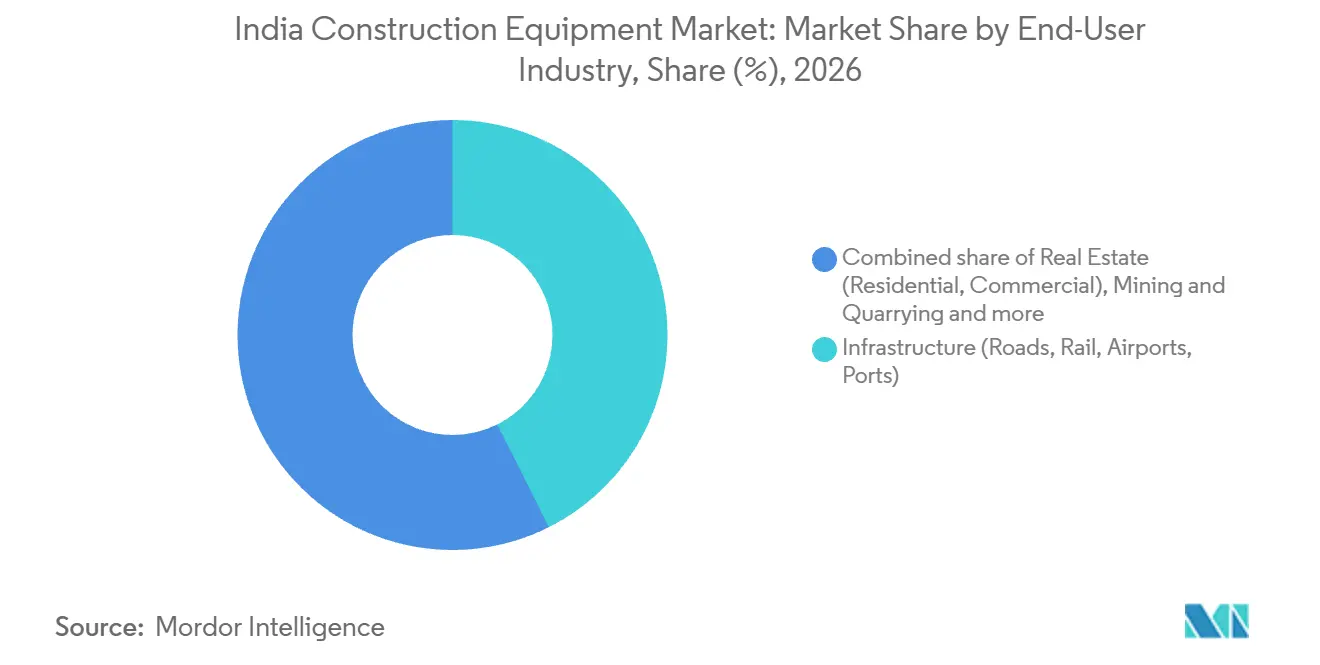
- Among end-user industries, infrastructure held the largest share at 42.6% in 2026, while mining and quarrying is forecast to grow fastest at a 10.4% CAGR over 2027-2032.
- By power output rating, 101-200 HP equipment led with a 37.5% market share in 2026, with equipment above 400 HP forecast to grow fastest at an 11.3% CAGR over 2027-2032.
- Within ownership models, contractor-owned equipment represented 70.27% of the market in 2026, while rental fleets are forecast to grow fastest at a 12.3% CAGR over 2027-2032.
- Geographically, South India held a 32.04% market share in 2026, and North-East India is forecast to grow fastest at a 12.3% CAGR over 2027-2032.
Note: Market numbers in this report are based on Mordor Intelligence's proprietary estimation framework, which combines nine months of actuals with Q4 projections for base year 2026.
Market Trends and Insights
Drivers Impact Analysis of India Construction Equipment Market*
| Driver | (~) % Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
|---|---|---|---|
| Government-led Mega Infrastructure Projects Under National Infrastructure Pipeline (NIP) Stimulating Equipment Demand | +3% | Ghansoli, Vikhroli, Maharashtra | Long term (≥ 4 years) |
| Rapid Urbanization Propelling High-rise Residential Construction in Tier II & III Cities | +1.8% | Coimbatore, Tamil Nadu | Medium term (2-4 years) |
| Acceleration of Mining Sector Reforms Increasing Demand for High-Capacity Excavators | +1.7% | Pakri Barwadih, Jharkhand | Medium term (2-4 years) |
| Fast-Track Execution of Bharatmala Corridors Using PM GatiShakti Planning Boosting Road Equipment Orders | +2% | Nationwide | Medium term (2-4 years) |
| Proliferation of Equipment Rental Platforms Expanding Access for SME Contractors | +1% | Nationwide | Short term (≤ 2 years) |
| OEM Investment in Localized Manufacturing & CKD Assembly Lowering Lead Times & Costs | +0.8% | Pune manufacturing facility | Medium term (2-4 years) |
| Source: Mordor Intelligence | |||
Government-led Mega Infrastructure Projects Under National Infrastructure Pipeline (NIP) Stimulating Equipment Demand
Government-led megaprojects support equipment demand as individual construction packages enter physical execution. As of August 2026, the Ministry of Statistics and Programme Implementation monitored 1,731 ongoing Central Sector infrastructure projects across 17 central ministries and departments through PAIMANA.[1] On July 19, 2026, a second tunnel boring machine began excavation from Sawli in Ghansoli toward Vikhroli for the Mumbai-Ahmedabad Bullet Train’s underground tunnel in Maharashtra. For earthmoving and road-equipment suppliers, the relevant opportunity lies in site preparation and surface works associated with major construction programs. Demand depends on those packages entering execution, rather than the monitored project count translating automatically into machinery orders.
Rapid Urbanization Propelling High-rise Residential Construction in Tier II & III Cities
High-rise housing creates an equipment opportunity in upper-floor concrete placement. Radiance Realty Developers India Ltd. reported that Pour 3 in Tower 2 of its Riverwoods apartment project in Coimbatore completed the 13th-floor roof slab in May 2026. The American Concrete Institute’s technical guide addresses truck-mounted concrete pumps and separate placing booms, emphasizing planning for equipment placement and pipeline routing. The project comprises 2 towers of basement, stilt and 13 floors with 377 apartments, so slab pours of this kind recur through each tower. Suppliers covering both earthmoving and concrete equipment can address successive work packages within a development, broadening their relevance to residential builders beyond the initial excavation phase.
Acceleration of Mining Sector Reforms Increasing Demand for High-Capacity Excavators
Coal-production scale sustains excavation requirements for mine operators, creating a demand base for high-capacity equipment. India’s captive and commercial coal blocks produced about 210.46 million metric tons in FY 2025-26, exceeding 200 million metric tons for the first time. BEML handed a new BRS21 electric rope shovel with a 21-cubic-meter bucket to Northern Coalfields Ltd. at Nigahi Mines, Singrauli, on April 29, 2025. The shovel was designed for overburden removal in opencast mines. This connects the large-machine opportunity to material movement around coal extraction, extending the equipment requirement beyond handling saleable coal alone.
Fast-Track Execution of Bharatmala Corridors Using PM GatiShakti Planning Boosting Road Equipment Orders
Road equipment suppliers face a construction opportunity shaped by network connections as well as the length of individual corridors. By March 2026, Bharatmala projects covering 26,425 kilometers had been awarded and 22,590 kilometers had been constructed. On February 4, 2026, the Network Planning Group evaluated 7 road projects proposed by the Ministry of Road Transport and Highways for conformity with PM GatiShakti principles. Its evaluation covered integrated multimodal infrastructure and last-mile connectivity to economic and social nodes. Connecting works create a potential equipment opportunity beyond main-corridor construction, conditional on those proposed projects advancing to execution.
Restraints Impact Analysis of India Construction Equipment Market*
| Restraint | (~) % Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
|---|---|---|---|
| Volatile Steel Prices Inflating OEM Production Costs & Customer Capex Budgets | -1% | Nationwide | Short term (≤ 2 years) |
| Persistent Delays in Land Acquisition Slowing Equipment Utilization Rates on Projects | -0.8% | Bengaluru suburban rail workfronts | Medium term (2-4 years) |
| Limited Charging Infrastructure Hindering Adoption of Electric & Hybrid Machines | -0.3% | Mine sites across India | Long term (≥ 4 years) |
| Regulatory Uncertainty Around CEV Stage V Emission Norms Adding Compliance Burden | -0.5% | Nationwide | Short term (≤ 2 years) |
| Source: Mordor Intelligence | |||
Volatile Steel Prices Inflating OEM Production Costs & Customer Capex Budgets
Steel-related cost pressure can weaken equipment demand through the economics of the projects that employ the machines. In August 2026, Shalabh Chaturvedi, an Indian Construction Equipment Manufacturers’ Association (ICEMA) vice president and CASE executive, described cost pressure on contractors with earlier bids. He said higher steel and construction-input costs had weakened their project economics and slowed execution in parts of India’s road-construction sector. Road construction was one of the most important sources of construction-equipment demand in that account. Slower execution can reduce the immediate productive work available to additional road equipment, even when the underlying contract survives. For contractors whose bids predated the cost increase, cheaper machinery would address only the equipment expense, leaving higher construction-input costs to weigh on margins and the execution of awarded road work.
Persistent Delays in Land Acquisition Slowing Equipment Utilization Rates on Projects
Land access can prevent a construction contract from translating into productive machinery hours, even after a contractor has mobilized. Reports on August 1, 2025 said Larsen & Toubro (L&T), the project contractor, had terminated its Bengaluru Suburban Railway Project contract for Corridors 2 and 4. The contractor said K-RIDE had handed over only 8.28% of the encumbrance-free workfront since August 2022, leaving machinery idle.[2] An awarded contract can leave a contractor carrying machinery costs without corresponding construction progress. Adding machines would deepen that exposure while workfront access remains the binding constraint.
*Our forecasts treat driver/restraint impacts as directional, not additive. The impact forecasts reflect baseline growth, mix effects, and variable interactions.
India Construction Equipment Market Segment Analysis
By Equipment Type:
Core Earthmoving Scale Meets Specialized Road DemandEarthmoving equipment accounted for a 56.26% share of the India construction equipment market size in 2026, making it the largest segment. ICEMA recorded total FY 2025-26 earthmoving sales of 97,236 units, including exports, down 2% year over year. That combination distinguishes the category’s established scale from the direction of annual shipments, so leadership does not imply every supplier benefits from expanding unit demand. Earthmoving suppliers face softer shipment volumes across the combined domestic and export sales base, even as the category anchors domestic market value.
Road construction equipment is the fastest-growing segment, with a forecast CAGR of 9.75% over 2027-2032. On August 26, 2026, L&T Construction & Mining Machinery partnered with FAYAT Road Equipment Division India to market BOMAG road milling machines, soil stabilizers, and cement spreaders. The agreement also covered sales, after-sales support, and spare-parts supply. For road contractors, pairing specialized machines with a commercial support channel connects machine supply with support after delivery. The partnership extends the commercial relationship into the machine’s service life, making support coverage part of the offer for specialized roadwork.



By Drive Type:
Conventional Platforms Lead as Electric Loaders Enter Port WorkConventional hydraulic/diesel equipment represented a 94.35% India construction equipment market share in 2026, making it the largest segment. L&T Construction & Mining Machinery crossed the 5,000th cumulative India sale milestone for the Komatsu PC210LC/PC210-10M0 excavator family in FY 2025-26. The models are hydraulic excavators with direct-injection engines and biodiesel compatibility. This gives conventional-drive equipment a commercial base in an established model family, where the milestone reflects accumulated adoption rather than one year’s procurement. Biodiesel compatibility gives this established engine family a fuel-adaptation route within the conventional-drive category.
Electric/hybrid equipment is the fastest-growing segment, with a forecast CAGR of 15.2% over 2027-2032. In February 2025, Deendayal Port Authority supported Swayam Shipping Services Pvt Ltd’s deployment of 4 SDLG L956HEV electric wheel loaders at Kandla. The deployment aligned with the government’s Harit Sagar Green Port Guidelines. For port-equipment users, this places electrification within a defined port operation, rather than leaving the equipment offering at the development stage. The Kandla arrangement combines authority support with a private operator’s deployment, giving electrification an institutional route into port work.

By End-User Industry:
Transport Programs Anchor a Broader Mining OpportunityInfrastructure, covering roads, rail, airports, and ports, was the largest segment with a 42.6% market share in 2026. The National Highways Authority of India constructed 5,313 kilometers of national highways in FY 2025-26, about 15% above its 4,640-kilometer target. Indian Railways had 514 sanctioned infrastructure projects spanning 40,000 kilometers for new lines, gauge conversion, and track doubling as of April 1, 2026. These activities give equipment suppliers exposure to both completed road delivery and a sanctioned rail work program, with different application requirements and project stages. That breadth can spread a supplier’s construction opportunities across transport systems rather than concentrate its equipment proposition on one type of public works.
Mining and quarrying is the fastest-growing segment, with a forecast CAGR of 10.4% over 2027-2032. The Ministry of Mines reported 30 mineral blocks operationalized in FY 2025-26, including iron ore, limestone, bauxite, and manganese. NMDC produced 53.15 million metric tons of iron ore in FY 2025-26, up 21% year over year. This combines newly operational mineral assets with rising output at an established producer, giving equipment suppliers more than one route into the mining buyer base. The commercial opening spans developers moving assets into operation and mine operators sustaining higher production, with equipment offers differentiated by the stage and scale of each site.
By Power Output Rating:
Midrange Platforms and High-Capacity HaulageEquipment rated 101-200 HP held the largest share, at 37.5% in 2026. L&T Construction & Mining Machinery reported the 1,000th Komatsu PC205 sale in India in FY 2025-26. Komatsu India specifies the PC205-10M0 at 148 HP gross power at 2,000 rpm. The specification connects an established commercial model to a defined midrange power band. The PC205 milestone gives service and parts planning a defined sales base within this power band.
Equipment rated above 400 HP is the fastest-growing segment, with a forecast CAGR of 11.3% over 2027-2032. L&T Construction & Mining Machinery commissioned a 1,200-horsepower Komatsu HD785-7 dump truck for Tata Steel’s Noamundi iron ore mine in Jharkhand in 2025. It handed the machine over on August 18, 2025, with a payload capacity of 100 metric tons. The model combined variable horsepower control, automatic retard speed control, and KOMTRAX Plus telematics. Payload capacity, speed control, and telematics make the mine’s haulage task the relevant comparison, with horsepower serving as a capacity screen rather than a complete specification.
By Ownership Model:
In-House Fleets Coexist with Rental ExpansionContractor-owned equipment was the largest segment, with a 70.27% market share in 2026. H.G. Infra Engineering reported a 2,900+ fleet and equipment base in FY 2025-26 and described project execution as backed by a large in-house equipment fleet. This links ownership directly to contractor execution capability, rather than treating equipment as a separately sourced service for every job. Contractor ownership couples control over execution capacity with direct exposure to idle-machine costs when work slows.
Rental fleets are the fastest-growing segment, with a forecast CAGR of 12.3% over 2027-2032. Aggcon Equipments International operated a 337-unit construction-equipment rental fleet across 27 Indian states and 5 union territories as of March 31, 2025. Sanghvi Movers deployed 76 cranes in India under its FY 2025-26 capital expenditure program through December 2025. This combines a multi-category rental operator with capacity additions by a crane specialist, showing distinct routes for expanding rented construction capability. Specialist fleet additions put the capital commitment with the rental operator, while contractors obtain access through rental arrangements.
Geography Analysis
South India Construction Equipment Market
South India accounted for a 32.04% share of the India construction equipment market size in 2026, making it the largest geography. According to the Ministry of Rural Development, Tamil Nadu completed 1,926 kilometers of Pradhan Mantri Gram Sadak Yojana rural roads in FY 2025-26. The Department for Promotion of Industry and Internal Trade reviewed issues across 5 infrastructure projects in Karnataka, 2 in Kerala, and 3 in Telangana in September 2025. Together, the completed rural roads and multi-state project reviews show a construction base spread across several southern states, giving equipment suppliers exposure beyond one state’s road program.
North-East India Construction Equipment Market
North-East India is the fastest-growing geography, with a forecast CAGR of 12.3% over 2027-2032. In March 2026, the National Highways Authority of India reported 18 bids for the Kaliabor-Numaligarh highway project in Assam and scheduled its award for FY 2025-26. Assam completed 131 kilometers of rural roads under the Pradhan Mantri Gram Sadak Yojana in FY 2025-26, down from 277 kilometers in FY 2024-25. The same FY 2025-26 program table recorded 1,522 kilometers sanctioned in the state. Assam’s lower completed mileage shows that growth in the region depends on sanctioned works advancing to construction, so bid counts mark interest rather than realized equipment demand.
In North India, the Cabinet-approved Zirakpur-Panchkula bypass through Punjab and Haryana faced a July 2026 court-directed resurvey, and NHAI had proposed an alternative alignment by October 17. West India’s road infrastructure included the March 2025 foundation stone for a 4-lane bridge over Gujarat’s Narmada Canal on NH-147. In East India, Dilip Buildcon was appointed mine developer and operator for NALCO’s Pottangi bauxite mine in Odisha on December 9, 2025 and signed the agreement on December 20. In Central India, 1,586 kilometers of Bharatmala Phase I roads had been constructed in Madhya Pradesh by February 2025, supporting a highway-connectivity role. These regions span conditional road schemes, contracted mine-linked infrastructure, and completed highways, making project status central to distinguishing potential machinery work from delivered construction.
Regulatory Framework and Outlook
The comparison covers selected jurisdictions, India’s national vehicle regime and Tamil Nadu, from the perspective of manufacturers and suppliers of construction-equipment vehicles. At the national level, Rule 115A(10) applies CEV Stage V emissions requirements from January 1, 2025. Tamil Nadu’s Act 30 of 2023 covers construction-equipment vehicles specified in the First Schedule, with annual-or-lifetime tax wording and lifetime rates in the Tenth Schedule. These frameworks affect different commercial decisions, connecting machine compliance with a buyer’s vehicle-registration and tax obligations.
Regulatory Table of India Construction Equipment Market
| Decision factor | India | Tamil Nadu |
|---|---|---|
| Primary authority | Ministry of Road Transport and Highways | Regional Transport Officer or Additional Regional Transport Officer |
| Key instruments or direction | Central Motor Vehicles Rules, Rule 115A(10); G.S.R. 542(E), June 2026 | Act 30 of 2023, First and Tenth Schedules; September 2025 motor-grader judgment |
| Commercial effect | CEV Stage V emissions compliance for construction-equipment vehicles | Tax licensing for scheduled vehicles; lifetime tax applied to a new motor grader |
| Current policy attractiveness | Medium | Medium |
| Future direction of policy attractiveness | No change | No change |
| Source: Mordor Intelligence | ||
The national Medium rating balances a defined compliance obligation with continuity of its implementation date after the June 2026 amendment. Tamil Nadu’s Medium rating reflects defined tax licensing alongside the lifetime treatment applied by the Madras High Court to a contractor’s new motor grader in September 2025. The state’s June 19, 2026 draft addressed optional advance-registration-number fees, including government allotments for any vehicle class. That limited proposal supports continuity in the core tax position, while the Madras High Court’s September 2025 motor-grader ruling makes payment timing commercially relevant to quotations for that equipment.
Value Chain Stages
The value chain compares machine manufacturing, regional distribution, and support after delivery, with suppliers capturing value at different points in the equipment life cycle. JCB India Ltd. manufactures earthmoving and construction equipment in India for domestic and export markets and supports a local supplier network. L&T Construction & Mining Machinery appointed NuComet Enterprises as its authorized dealer for Kerala, as reported in its April 2025 Earthmover News.[3]
Value Chain Analysis Table of India Construction Equipment Market
| Primary activity | Key participants | Value capture | Bottleneck | Resilience response |
|---|---|---|---|---|
| Machine manufacturing | Equipment manufacturers such as JCB India Ltd. and Tata Hitachi Construction Machinery Co. Pvt. Ltd. | New-machine sales | Coordinating supplier inputs with machine production | Align local supplier releases with factory schedules |
| Regional sales and distribution | Authorized dealers such as NuComet Enterprises and Yantraman Automac | Machine sales and distribution income | Matching regional sales coverage with customer support | Develop dealer coverage alongside workshop capability |
| Parts supply and machine service | OEM parts operators such as JCB India Ltd. and service providers such as SANY India | Parts sales and maintenance services | Connecting repair capability with parts availability | Coordinate warehouses, workshops, and mobile support |
| Source: Mordor Intelligence | ||||
Dealer capability determines whether regional reach extends beyond selling new machines. Yantraman Automac’s Vadodara facility opened with a 5-bay workshop, one workshop van, and a parts van. JCB India’s warehouses supply parts to its dealerships and outlets across India. Combining stocked parts with workshop and mobile capacity creates a path to recurring service earnings and can reduce reliance on a distant factory for support.
Competitive Landscape
Market Concentration
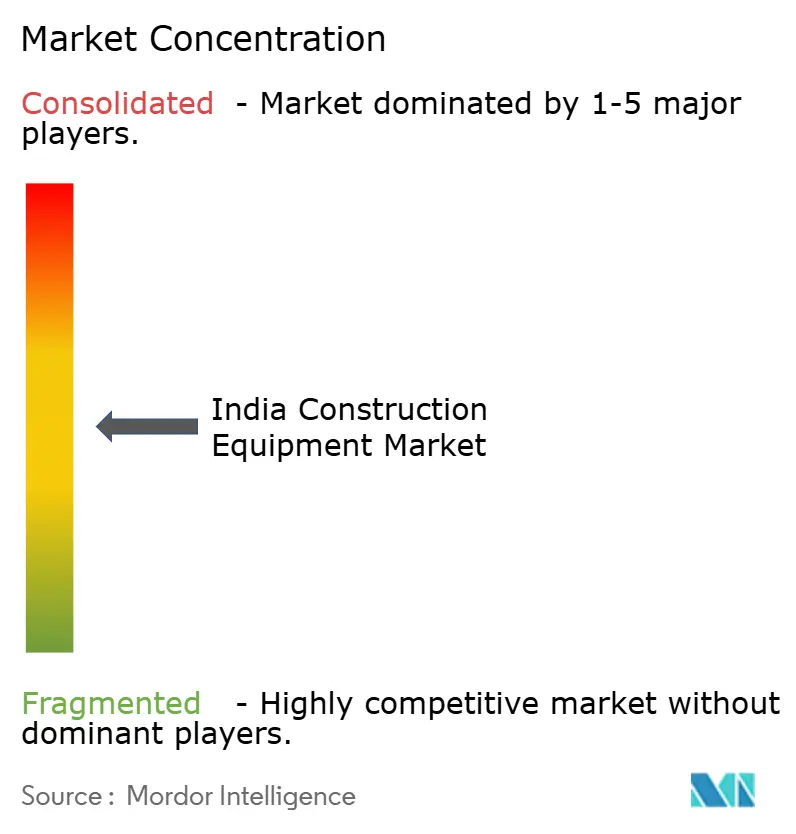
Competition centers on established equipment manufacturers and dealer-supported brands, with barriers around production capability, market reach, and customer support. Caterpillar Inc., Komatsu India Pvt. Ltd., Volvo Construction Equipment India, Tata Hitachi Construction Machinery Co. Pvt. Ltd., and JCB India Ltd. are major participants. GMMCO partners with Caterpillar for Indian sales and support, while JCB manufactures for domestic customers and exports. On March 5, 2025, Tata Hitachi handed over 6 SHINRAI Prime machines, 8 ZAXIS 220LC Ultra excavators, and 2 ZAXIS 140H Ultra excavators to Ramalingam Constructions Company. Dealer coverage and domestic production shape access to Indian buyers alongside the ability to supply several models.
Tata Hitachi’s January 2025 start of sales of India-made economy models added 2 hydraulic excavator models and one backhoe loader model alongside its high-performance premium equipment. This gives buyers a choice of price and capability positions within one manufacturer’s range, making local production part of a differentiated portfolio. For a challenger, low acquisition price alone offers less separation when the incumbent already sells an economy range.
CEV Stage V emissions requirements apply across all engine power bands for construction-equipment vehicles, establishing a common compliance baseline for manufacturers. In March 2025, Volvo Construction Equipment handed an EC380DL UHR high-reach demolition excavator to United Saw Services in Jeedimetla, Hyderabad. The machine had 23 meters of reach and was intended for the planned demolition of a fire-damaged, 3-story, 50,000-square-foot building. In May 2026, ICEMA panel convener Vivek Hajela said the CEV Stage V transition had raised construction-equipment prices by 12 to 15% on average. With Stage V compliance common to manufacturers, Volvo’s competitive distinction lies in task-specific reach for planned demolition, while Hajela’s price estimate describes the industry average.
India Construction Equipment Industry Leaders
-
Caterpillar Inc.
-
Komatsu India Pvt. Ltd.
-
Volvo Construction Equipment India
-
Tata Hitachi Construction Machinery Co. Pvt. Ltd.
-
JCB India Ltd.
- *Disclaimer: Major Players sorted in no particular order
India Construction Equipment Market Companies Covered in this Report
- JCB India Ltd.
- Tata Hitachi Construction Machinery Co. Pvt. Ltd.
- Caterpillar Inc.
- Komatsu India Pvt. Ltd.
- Volvo Construction Equipment India
- Larsen & Toubro Construction & Mining Equipment
- SANY Heavy Industry India
- XCMG Construction Machinery Co. Ltd.
- HD Construction Equipment India
- BEML Ltd.
- Action Construction Equipment Ltd.
- Kobelco Construction Equipment India
- CNH Industrial (CASE Construction)
- Doosan Bobcat India
- Zoomlion Heavy Industry Science & Technology
- LiuGong India
- Mahindra Construction Equipment
- Wirtgen India (John Deere)
- Schwing Stetter India
- Putzmeister India
Key Opportunities for Market Participants
The opportunities compare equipment supply for active highway works with earlier engagement around fully and partially explored coal blocks. The road ministry reported 5,580 kilometers of National High-Speed Corridors under implementation across India on July 22, 2026. The Ministry of Coal’s 16th auction round offered 25 coal blocks on September 17, 2026. The commercial distinction is between construction already under implementation and mine development that must progress through an operationalization schedule.
Market Opportunities Table of India Construction Equipment Market
| Opportunity | Why now | Buyer / lead segment | Recommended play | Main barrier | Likely beneficiaries |
|---|---|---|---|---|---|
| Project-linked earthmoving packages for highway works | National High-Speed Corridors were under implementation in July 2026 | Highway construction contractors | Phase machine delivery against active construction work packages | Aligning fleet commitments with work-package execution | Earthmoving manufacturers such as JCB India Ltd. |
| Integrated equipment packages for fully explored coal blocks | The 2026 schedule shortened operationalization from 51 to 40 months | Developers of fully explored coal blocks | Bundle machine selection, delivery, and commissioning around development milestones | Coordinating equipment readiness with mine operationalization | Mining-equipment suppliers and mine-development contractors |
| Temporary rental access for partially explored coal blocks | The 2026 schedule shortened operationalization from 66 to 52 months | Developers of partially explored coal blocks | Rent equipment for initial work, with expansion options as development advances | Development work before full operating-fleet use | Equipment rental operators and development-stage contractors |
| Source: Mordor Intelligence | |||||
The central opening is to match equipment commitments to the buyer’s development exposure. Active highway works support deployment-led offers, while the distinct mine-operationalization windows favor staged commercial engagement. Equipment agreements can combine milestone-based delivery with temporary rental access, allowing a buyer to separate early work from commitment to a full operating fleet. This lets suppliers pursue the mine-development pipeline without making the entire sales case depend on an assumed operating start date.
Recent Industry Developments in India Construction Equipment Market
- Aug 2026: L&T Construction & Mining Machinery partnered with FAYAT Road Equipment Division India to market BOMAG road milling machines, soil stabilizers, and cement spreaders in India, including after-sales support and spare-parts supply.
- Jun 2026: The Ministry of Road Transport and Highways issued G.S.R. 542(E), dated June 30, restating January 1, 2025 as the CEV Stage V applicability date for construction-equipment vehicles under Rule 115A(10).
India Construction Equipment Market Report Scope and Research Methodology
Market Definition and Coverage
The India construction equipment market measures annual spending on new, factory-built construction machines sold for use in India. It covers equipment acquired by owners and rental fleets across India.
Scope exclusions: Separately sold aftermarket parts, separately sold attachments, used, rebuilt, or remanufactured machines, hand-operated construction tools, and aftermarket service or equipment rental fees are excluded.
Segments Covered in This Report
- By Equipment Type
- Earthmoving Equipment
- Excavator
- Backhoe Loader
- Wheeled Loader
- Bulldozer
- Motor Grader
- Compaction Roller
- Road Construction Equipment
- Asphalt Paver & Finishers
- Cold Planers & Milling Machines
- Material Handling Equipment
- Mobile Cranes
- Forklift & Telehandler
- Aerial Work Platforms
- Concrete Equipment
- Transit Mixer
- Concrete Pump
- Batching Plant
- Material Processing & Crushing Equipment
- Jaw & Cone Crushers
- Screening Plants
- Pile-Driving & Drilling Rigs
- Earthmoving Equipment
- By Drive Type
- Conventional Hydraulic / Diesel
- Electric / Hybrid
- By End-User Industry
- Infrastructure (Roads, Rail, Airports, Ports)
- Real Estate (Residential, Commercial)
- Mining & Quarrying
- Industrial & Energy
- By Power Output Rating
- less than 100 HP
- 101-200 HP
- 201-400 HP
- greater than 400 HP
- By Ownership Model
- Rental Fleet
- Contractor-Owned
- By Geography
- North India
- South India
- West India
- East India
- Central India
- North-East India
Data Sources, Market Sizing, and Validation
Desk Research
Public research draws on sources such as the Economic Survey of India for infrastructure investment context, Union Budget releases from the Press Information Bureau for public capital expenditure plans, the parliamentary committee report on the Ministry of Heavy Industries for construction-equipment policy, and ICEMA sales data reported by NBMCW for annual industry shipments. These sources help distinguish planned spending, equipment-sector policy, and observed shipments when assessing demand for new machines in India.
Company annual reports, exchange filings, investor presentations, and reputable business and trade press provide supplementary evidence on product portfolios, capacity, dealer reach, and reported sales, with conflicting figures checked against the original publication where available. These sources are not exhaustive, and further sources inform collection, validation, and clarification.
Primary Interviews and Surveys
Planned interviews with Indian construction-equipment manufacturers, authorized dealers, contractor and rental-fleet procurement leads, and infrastructure or mining equipment users would test secondary findings on purchase timing, utilization, realized transaction prices, and regional demand. Where respondents or published evidence do not establish a segment or regional split, analysts would record the gap, compare independent shipment, project, and company signals, and use the most supportable range when building the estimate.
Distribution of primary research fieldwork respondents
| Company type | Respondent position | Region |
|---|---|---|
| Top tier: 35% | CXOs: 20% | |
| Mid tier: 45% | Functional/Unit leaders: 35% | |
| Smaller Players: 20% | Managers: 45% |
Market-Sizing & Forecasting
Analysts build a top-down estimate of annual new-machine sales revenue in India, using infrastructure capital expenditure and project execution to gauge construction demand, equipment shipments and mining output to track machine needs, and steel and equipment price movements to assess transaction values. A multivariate regression relates these indicators to historical market value, while CEV Stage V product changes and fleet replacement inform the forecast. Segment shares are derived from equipment sales evidence by machine type, drive, end-user, power band, ownership model, and Indian region. Selective supplier roll-ups and sampled average selling price times unit volume checks test the total and larger segments, with unmatched products or regions held as explicit gaps for further source checks. Indian market and procurement experts would challenge the direction and timing of individual forecast inputs before analysts settle the model.
Data Validation & Update Cycle
Analysts triangulate the estimate against independent shipment reports, company disclosures, infrastructure execution, and mining activity, then trace material variances to period, product, price, or coverage differences. They review outliers and reconcile segment totals before sign-off, seek clarification or re-contact respondents when a material conflict remains, refresh the model annually, revisit it after material policy or execution changes, and complete a fresh source and consistency pass before delivery.
Mordor Intelligence's India Construction Equipment Market Size Compared Against Other Published Estimates
Published estimates can differ in the transactions and products they count and the inputs used to model demand. The India construction equipment market measures annual spending on new, factory-built construction machines sold for use in India.
Key Gap Drivers include the study's defined coverage and market-specific modeling choices. Analysts build a top-down estimate of annual new-machine sales revenue in India, using infrastructure capital expenditure and project execution to gauge construction demand, equipment shipments and mining output to track machine needs, and steel and equipment price movements to assess transaction values.
Benchmark comparison
| Source | Market Size | Gaps in Research Methodology |
|---|---|---|
| Mordor Intelligence | USD 9.98 B (2027) | |
| Global Consultancy A | USD 15.37 B (2025) | At its 2025 base, this estimate is 54.0% above this report's 2027 value of USD 9.98 B, 2 years later. Its total includes a 31% services component, while this market measures first-sale revenue for new machines. |
| Global Consultancy B | USD 8.5 B (2023) | At its 2023 base, this estimate is 14.8% below this report's 2027 value of USD 9.98 B, 4 years later. Its published 2023 base precedes the comparison year, and its forecast assumes continued market growth. |
Mordor Intelligence's analysts triangulate the estimate against independent shipment reports, company disclosures, infrastructure execution, and mining activity, then trace material variances to period, product, price, or coverage differences.
Key Questions Answered in the Report
What is the India construction equipment market size forecast for 2032?
The size is forecast to reach USD 14.46 billion by 2032, from USD 9.98 billion in 2027, with a 7.7% CAGR over 2027-2032.
What is driving construction-equipment demand in India?
Infrastructure activity is a major driver, with 1,731 ongoing Central Sector projects monitored as of August 2026. Housing construction and mining operations also support equipment use.
Which construction-equipment category has the largest share in India?
Earthmoving equipment led with a 56.26% market share in 2026.
Which companies are major construction-equipment suppliers in India?
Major participants include Caterpillar Inc., Komatsu India Pvt. Ltd., Volvo Construction Equipment India, Tata Hitachi Construction Machinery Co. Pvt. Ltd., and JCB India Ltd.
What can constrain construction-equipment demand in India?
Steel-input cost pressure and restricted land access can slow project execution. L&T, acting as the project contractor, cited idle machinery when it terminated its Bengaluru rail contract, as reported on August 1, 2025.
Which Indian region leads construction-equipment demand, and where is growth fastest?
South India held 32.04% of the market in 2026, while North-East India is forecast to grow fastest at a 12.3% CAGR over 2027-2032.